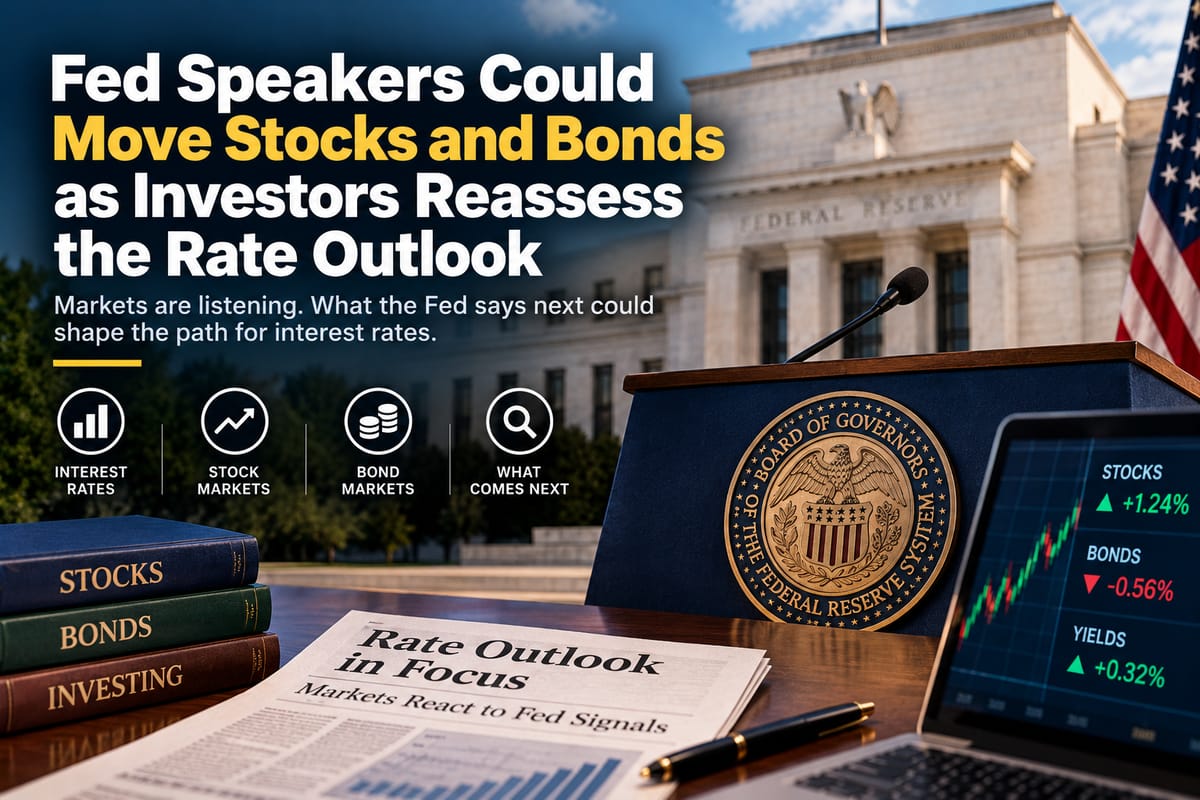
Fed Speakers Could Move Stocks and Bonds as Investors Reassess the Rate Outlook
With inflation still elevated and financial markets already adjusting to the possibility of additional tightening, even small differences in language from policymakers could influence Treasury yields, stock valuations and expectations for the next rate decision.
Household Budgets Remain Under Pressure as Energy Costs Rise Faster Than Grocery Prices
For households already operating with limited financial flexibility, these increases can change the way monthly income is allocated. A larger fuel bill can mean less money available for groceries, savings, debt payments, entertainment or unexpected expenses.
How Investors Interpret Economic Data
Understanding how investors interpret economic data can make financial market movements easier to understand.
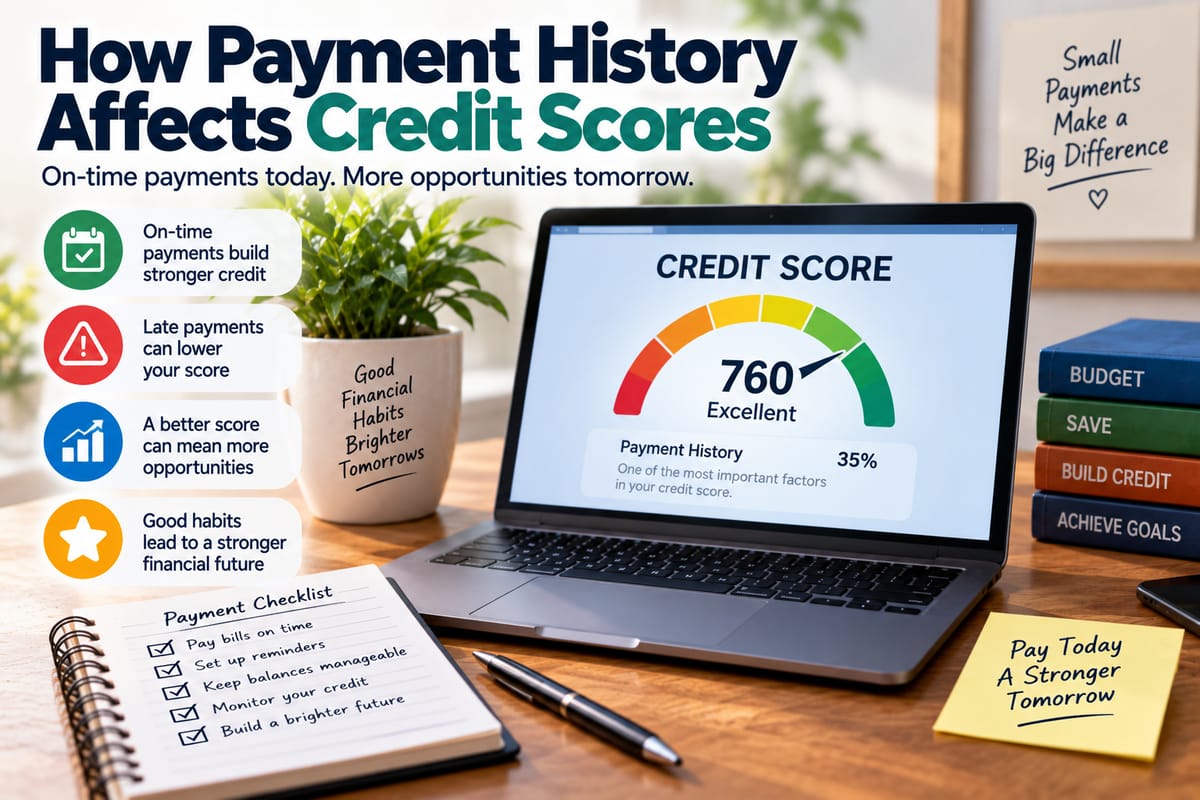
How Payment History Affects Credit Scores
Understanding payment history is therefore essential for anyone who uses credit cards, loans, mortgages, or other forms of borrowing.
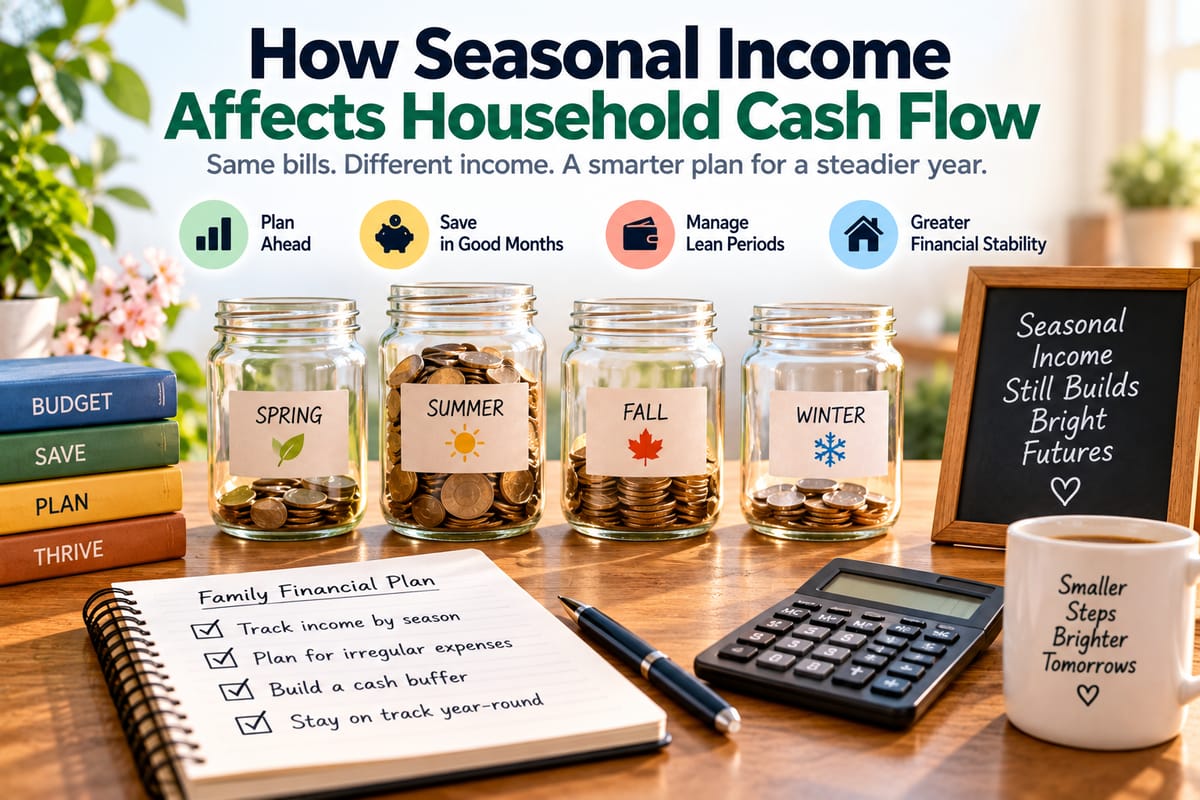
How Seasonal Income Affects Household Cash Flow
Understanding this timing difference can make it easier for families to plan ahead, build reserves, adjust spending, and avoid treating a high-income month as though it represents normal income for the entire year.
How to Budget With Irregular Income
Instead of building a budget around a fixed paycheck, households with variable earnings can focus on essential expenses, minimum income expectations, cash reserves, flexible spending limits, and longer-term financial goals. The objective is to create a system that works during both strong and weak income months.
How to Price Professional Services Properly
Understanding these factors can make pricing more deliberate and help professionals avoid constantly guessing what they should charge.
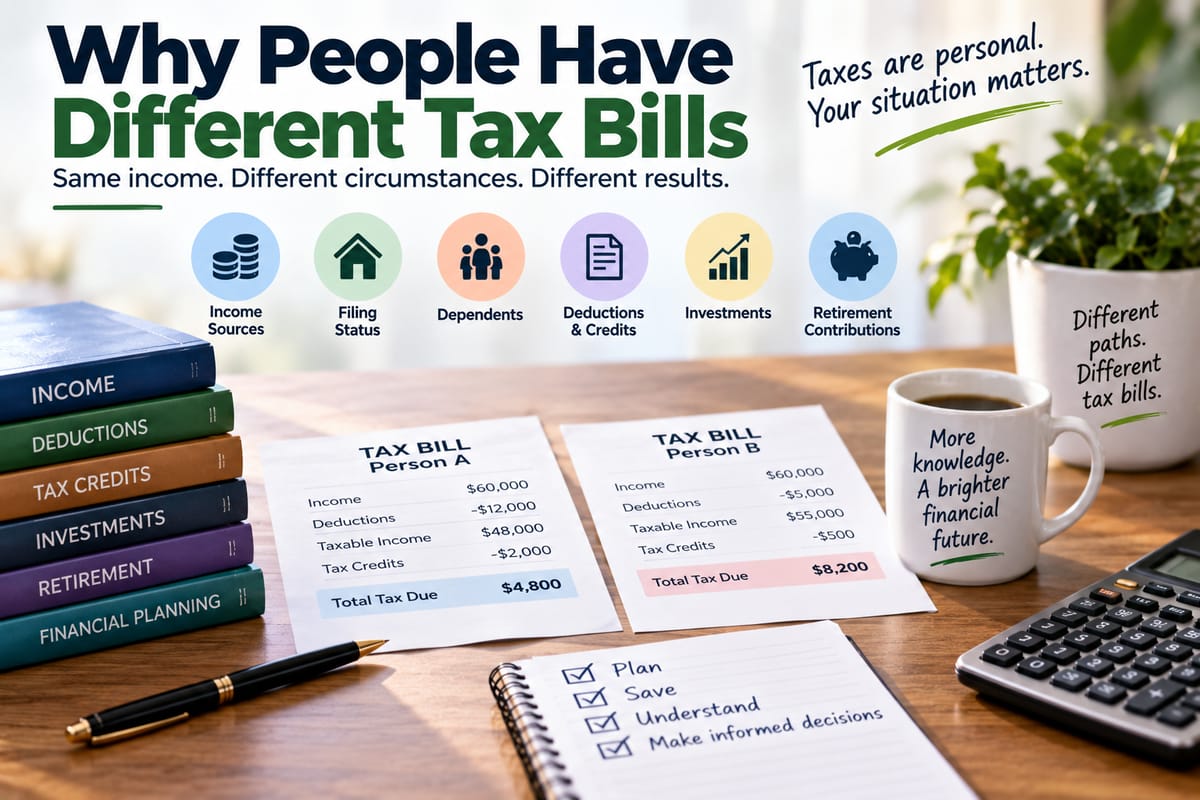
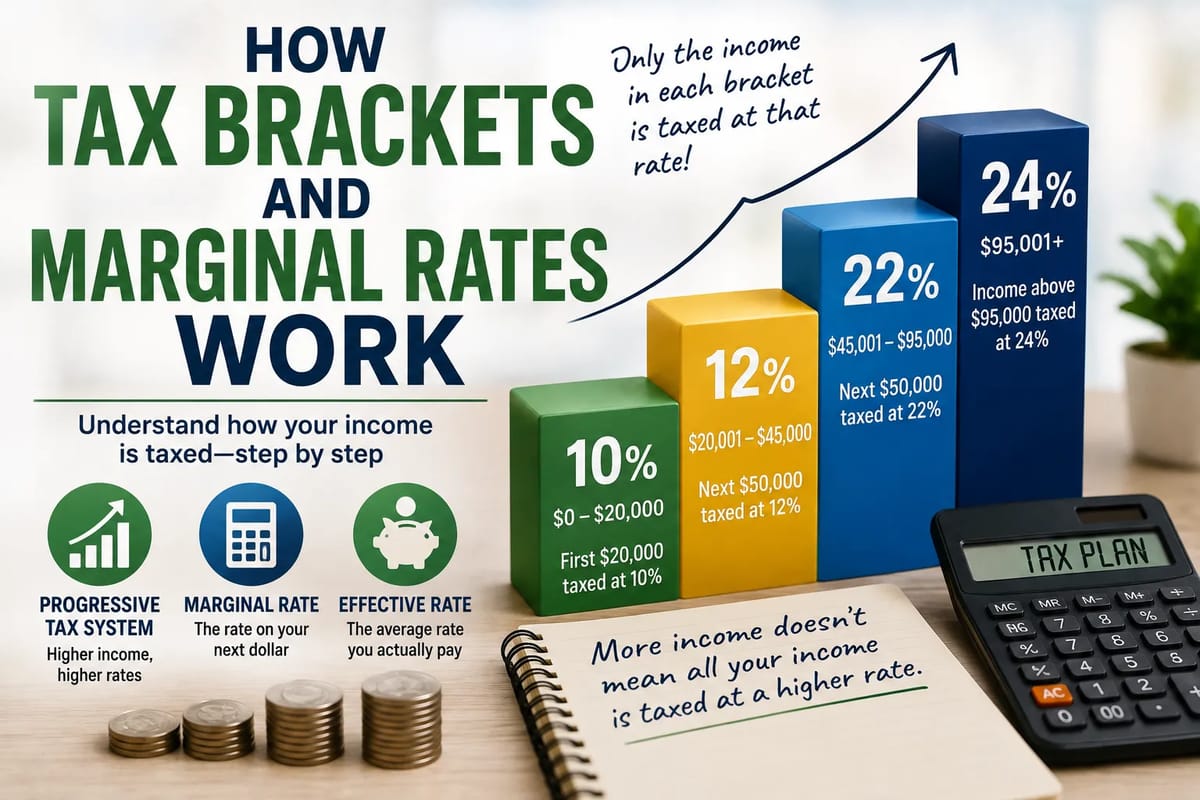
Why People Have Different Tax Bills
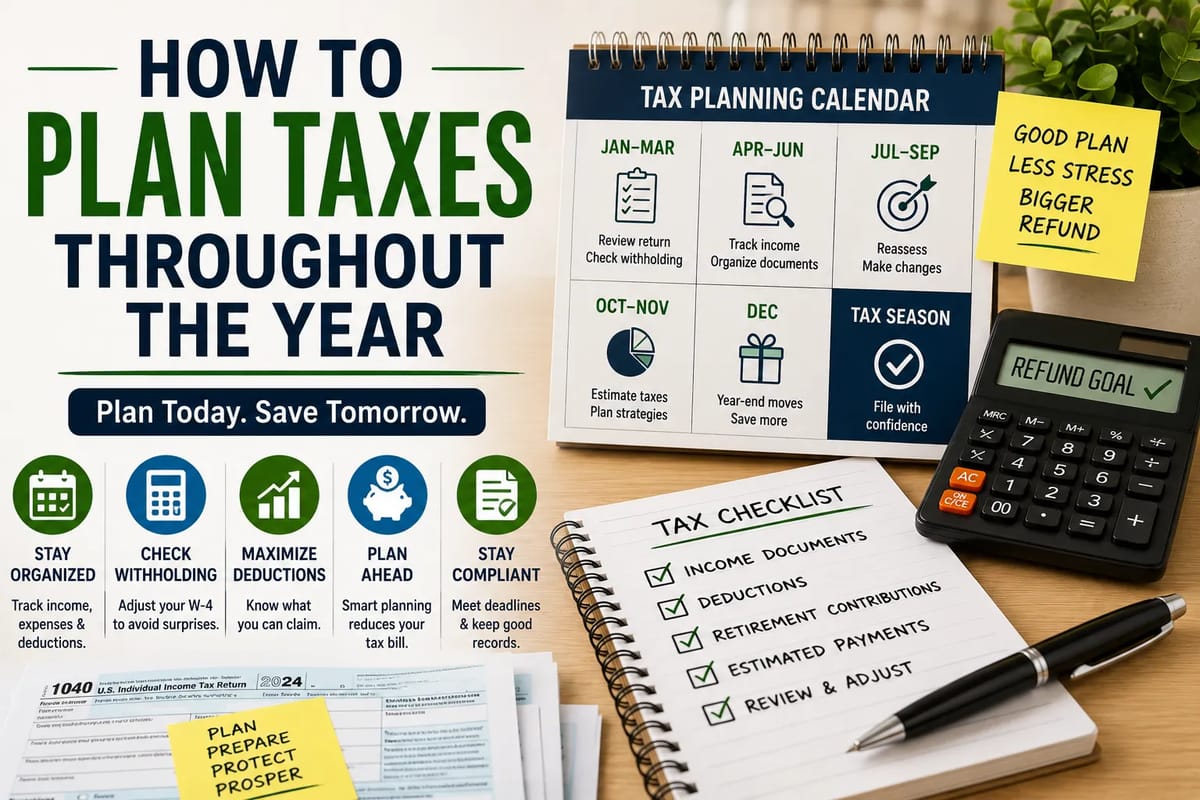
Filing status, taxable income, deductions, credits, types of income, retirement contributions, dependents, and other financial circumstances can all affect the final amount. Understanding these differences makes tax bills easier to interpret and can help households make more informed financial decisions throughout the year.
Popular Posts