How Cash Buffers Support Household Finances
Understanding how cash buffers work can make budgeting more practical, especially for families dealing with irregular income, changing expenses, or multiple financial commitments.
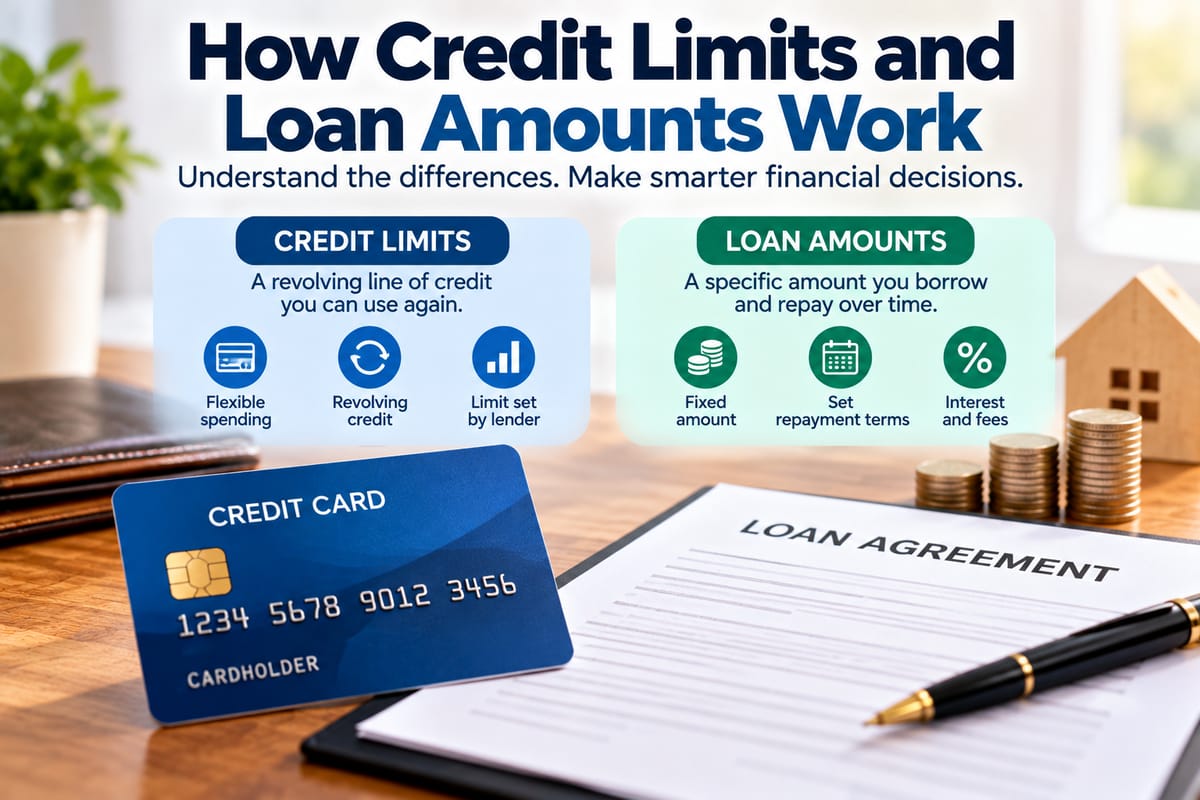
How Credit Limits and Loan Amounts Work
Understanding how credit limits and loan amounts work can make borrowing easier to manage. It can also help borrowers understand why two people applying for similar financial products may receive very different offers.
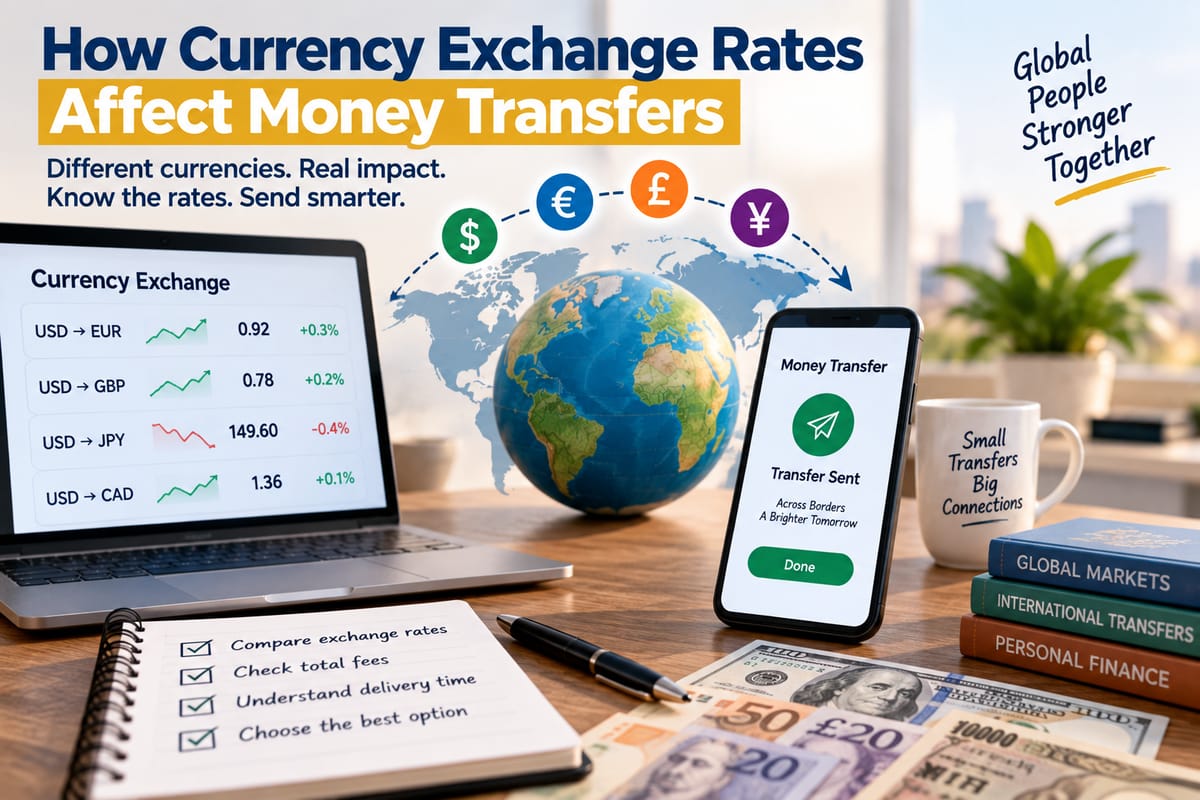
How Currency Exchange Rates Affect Money Transfers
Understanding how exchange rates work can help people estimate the value of international transfers, compare transfer options, and recognize why the amount sent may differ from the amount received.
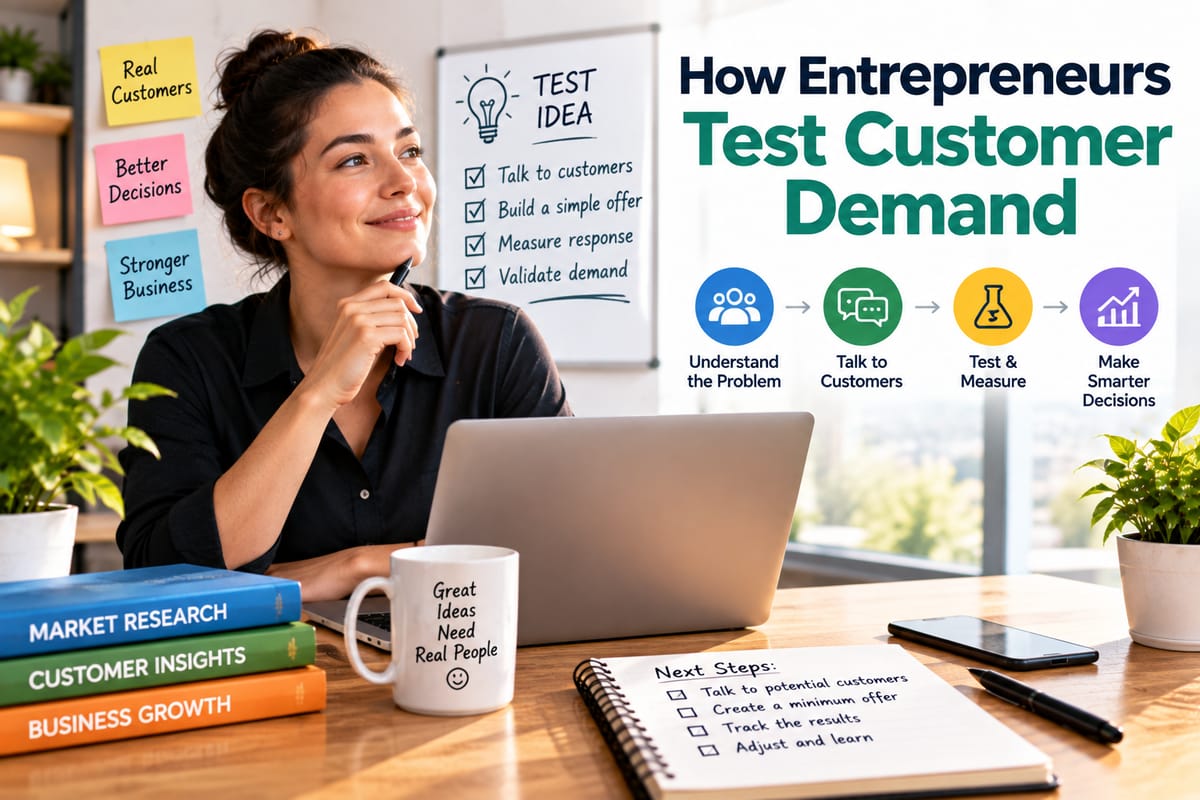
How Entrepreneurs Test Customer Demand
A product can be technically impressive and still struggle to attract customers. A service can solve a genuine problem but target people who are unwilling or unable to pay for it. Testing customer demand helps entrepreneurs reduce this uncertainty before investing substantial amounts of time and money.
How Volatility Differs Across Asset Classes
Understanding how volatility differs across asset classes can help explain why different investments behave differently during periods of uncertainty.
New Consumer Data Show Why Emergency Savings Matter as Financial Buffers Shrink
The numbers point to a broader issue: financial resilience is not determined simply by whether someone has a savings account. The size of that balance, the stability of household income and the ability to rebuild savings after an emergency all matter.
U.S. Flash PMI Data Could Test the Market's Growth Outlook
Against that backdrop, the preliminary PMI readings could influence expectations for growth, interest rates, Treasury yields, the dollar and risk assets.
What Are Self-Employment Taxes and How Do They Work?
Self-employment taxes are separate from federal income tax. A person may owe both based on their business or freelance income, which makes understanding the difference important when planning how much money to set aside throughout the year.
Popular Posts