How Cash Buffers Support Household Finances
Household finances do not always follow a perfectly predictable pattern. Paychecks may arrive on different dates, bills can vary from month to month, and unexpected expenses can appear without much warning. Even when a household earns enough money over the course of a year, timing differences can create periods when available cash feels unusually tight.
A cash buffer can help bridge that gap.
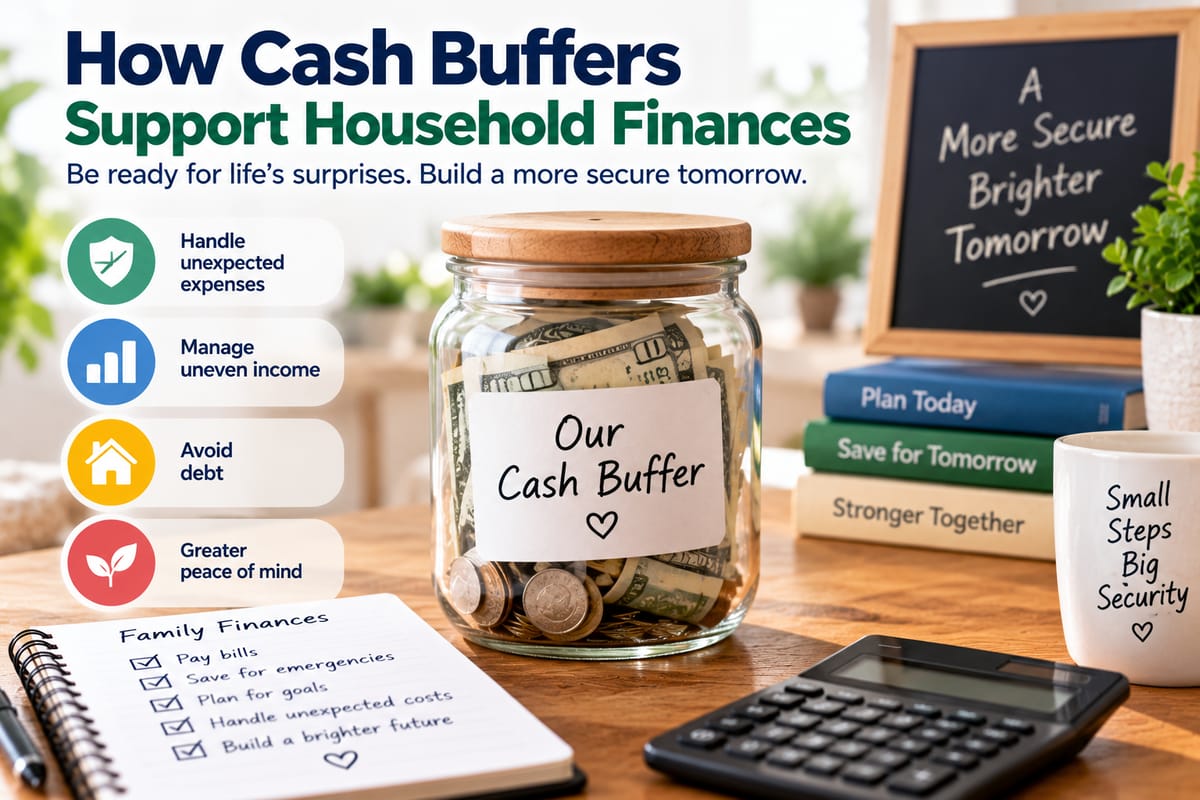
A cash buffer is money deliberately kept available for ordinary financial fluctuations, short-term surprises, or timing differences between income and expenses. It is not necessarily the same thing as a long-term emergency fund. Instead, it can serve as a layer of financial flexibility that helps a household avoid turning every unexpected expense into a crisis.
Understanding how cash buffers work can make budgeting more practical, especially for families dealing with irregular income, changing expenses, or multiple financial commitments.
What Is a Cash Buffer?
A cash buffer is a reserve of readily available money that remains in a household’s finances after planned spending and savings have been accounted for.
For example, a family might normally receive enough income each month to cover its bills, groceries, transportation, and savings goals. However, if a utility bill is higher than expected or a routine expense arrives earlier than planned, the household may need additional cash temporarily.
Instead of relying immediately on credit or disrupting another financial goal, the family can use part of its cash buffer.
Once the temporary expense has passed, the buffer can be rebuilt.
The key idea is financial breathing room.
A cash buffer gives a household somewhere to absorb small fluctuations without forcing every part of the budget to change.
Cash Buffer vs. Emergency Fund
Cash buffers and emergency savings are related, but they serve different purposes.
A cash buffer is generally intended for short-term financial fluctuations and manageable surprises. An emergency fund is designed to provide greater protection against significant or prolonged financial disruptions.
Consider the difference:
| Cash Buffer | Emergency Fund |
|---|---|
| Handles smaller or short-term disruptions | Handles major financial emergencies |
| Helps manage timing differences | Provides broader financial protection |
| Often used and replenished regularly | Ideally preserved for serious emergencies |
| May cover routine unexpected costs | May cover job loss, major repairs, or prolonged income disruption |
| Usually kept highly accessible | Also generally kept accessible |
A household may therefore benefit from having both.
For families determining how much should be reserved for larger emergencies, How Much Emergency Savings Should Families Have provides a useful framework for thinking about emergency savings separately from everyday cash flexibility.
Why Cash Flow Can Create Financial Pressure
One of the biggest reasons households benefit from cash buffers is that income and expenses do not always arrive at the same time.
Imagine a household where:
- A salary arrives near the end of the month.
- Rent is due at the beginning of the month.
- Utility bills arrive at different times.
- School expenses occur at irregular intervals.
- Groceries are purchased throughout the month.
- Transportation costs fluctuate.
The household may have sufficient income overall but still experience periods when the available balance becomes uncomfortable.
A cash buffer can help smooth these differences.
This is especially important for households with variable or seasonal income. How to Manage Uneven Household Cash Flow explores how families can plan when income does not arrive in a consistent pattern.
How a Cash Buffer Supports a Household Budget
A budget tells a household where its money is expected to go.
A cash buffer helps account for the fact that real life does not always follow the plan perfectly.
Suppose a family creates a monthly budget of $3,500 and expects its income and expenses to match closely. One month, an electricity bill is $100 higher than expected.
Without a buffer, the household may need to:
- Reduce another planned expense.
- Delay a savings contribution.
- Use a credit card.
- Borrow money.
- Move money from another financial goal.
With a buffer, the additional $100 can potentially be absorbed without changing the rest of the month’s plan.
The buffer therefore works alongside the budget rather than replacing it.
For households that want to establish a broader spending framework, How to Build a Family Budget provides a foundation for organizing income, expenses, savings, and financial priorities.
A Buffer Can Reduce the Need for Short-Term Borrowing
Small financial surprises can become expensive when a household has no readily available cash.
A relatively minor expense might lead someone to use a credit card and carry the balance forward. If the balance is not repaid promptly, interest can increase the eventual cost.
A cash buffer can reduce the frequency with which households need to borrow for relatively manageable expenses.
This does not mean every expense should automatically be paid from cash reserves. Rather, a buffer provides another option when a cost is unexpected but financially manageable.
The difference can be significant because borrowing often creates a second problem: the household must deal with both the original expense and the resulting repayment obligation.
Cash Buffers Can Help With Irregular Bills
Some household expenses are predictable but do not occur every month.
Examples include:
- Annual insurance premiums
- School-related expenses
- Vehicle maintenance
- Property taxes
- Membership renewals
- Home maintenance
- Seasonal clothing
- Holiday spending
- Professional fees
These expenses may not technically be emergencies, yet they can still disrupt a monthly budget if the household only plans around regular bills.
A cash buffer can provide short-term flexibility, while a dedicated sinking fund can be used for expenses that are known in advance.
The distinction is useful:
Known future expense: Plan and save specifically for it.
Unexpected short-term expense: A cash buffer may absorb it.
Major financial emergency: Emergency savings may be appropriate.
This structure helps prevent one account from being expected to solve every financial problem.
How Large Should a Cash Buffer Be?
There is no single amount that works for every household.
The appropriate size depends on factors such as:
- Income stability
- Payment frequency
- Monthly essential expenses
- Household size
- Number of financial dependents
- Typical bill fluctuations
- Access to other savings
- Frequency of unexpected expenses
- Whether income is seasonal or irregular
A household with highly predictable income and expenses may need a smaller operating buffer than one where income changes significantly from month to month.
The objective is not necessarily to accumulate as much cash as possible.
It is to maintain enough accessible money to make normal financial fluctuations easier to handle without creating unnecessary financial strain.
Starting With a Small Buffer
Building a cash buffer can seem difficult when a household already has many expenses.
Fortunately, it does not have to be created all at once.
A family could start with a modest target and gradually increase it.
For example:
- Set an initial target of $100.
- Add small amounts after each payday.
- Avoid spending the money unless necessary.
- Increase the target once the first milestone is reached.
- Adjust the target when household circumstances change.
The exact currency and amount will depend on the household.
What matters is creating a deliberate reserve rather than waiting until there is enough money left over by accident.
Using a Buffer Without Losing Control
A cash buffer works best when the household has clear rules for using it.
Without boundaries, the buffer can gradually become ordinary spending money.
A household might decide that the buffer can be used for:
- Unexpected utility increases
- Minor household repairs
- Necessary replacement items
- Short-term transportation problems
- Small medical or family expenses
- Timing gaps between income and bills
It might not be intended for:
- Routine entertainment
- Impulse purchases
- Planned vacations
- Regular grocery spending
- Lifestyle upgrades
The specific rules are up to each household, but the principle is simple: the buffer should have a purpose.
Rebuilding the Buffer After Using It
Using a cash buffer is not a financial failure.
That is what the money is there for.
The important step is rebuilding it afterward.
Suppose a family has a $500 buffer and uses $200 for an unexpected home repair. The remaining $300 still provides some protection, but the original target has not been restored.
The household can temporarily direct additional money toward rebuilding the reserve.
For example:
- Normal buffer contribution: $50 per month
- Temporary rebuilding contribution: $100 per month
- Amount used: $200
- Rebuilding period: Two months
Once the buffer returns to its target level, the household can return to its normal contribution.
This makes the buffer a replenishable financial tool rather than a one-time savings account.
Where to Keep a Cash Buffer
Accessibility is an important consideration.
Money intended to handle short-term household fluctuations should generally be easy to access when needed.
Some households may keep their buffer in a separate savings account so that it remains distinct from money intended for everyday spending.
Others may use a dedicated cash reserve within a broader household banking structure.
The important considerations include:
- Easy access
- Clear separation from routine spending
- Low risk of losing the principal
- Reasonable liquidity
- Visibility when reviewing household finances
The best location depends on the household’s banking arrangements and financial needs.
Keeping the Buffer Separate From Everyday Spending
One common problem is allowing reserve money to become indistinguishable from spending money.
If a household sees an extra $500 in its checking account, it can be tempting to treat the entire balance as available for discretionary purchases.
A separate savings balance can create a psychological boundary.
For example:
Checking account: Money for current bills and spending.
Cash buffer: Money for short-term financial surprises.
Emergency savings: Money for significant emergencies.
Long-term savings: Money for future goals.
The accounts do not necessarily need to be completely separate, but clearly defining their purposes can make financial decisions easier.
Cash Buffers and Irregular Income
A cash buffer can be particularly useful for people whose income varies.
Freelancers, contractors, commission-based workers, seasonal employees, business owners, and households with multiple income sources may not receive the same amount every pay period.
In these situations, a buffer can help smooth the difference between stronger and weaker income periods.
For example, a household might receive:
- $4,000 during a strong month
- $2,800 during an average month
- $2,200 during a slow month
If essential monthly spending is relatively stable, maintaining some cash from stronger months can reduce pressure during weaker ones.
This is different from spending more simply because income happens to be higher in a particular month.
Instead, the household can use stronger periods to strengthen its financial position before less predictable periods arrive.
Building a Buffer During High-Income Months
When income is variable, it can be useful to treat unusually strong months differently from ordinary months.
Rather than immediately increasing lifestyle spending, a household can divide the additional income among several purposes.
For example:
- Regular expenses
- Cash buffer
- Emergency savings
- Long-term goals
- Debt reduction
- Planned irregular expenses
- Discretionary spending
This approach can help convert temporary income increases into greater financial stability.
It also reduces the risk of allowing lifestyle expenses to rise permanently based on income that may not continue.
Using Financial Tools to Monitor the Buffer
Tracking a cash buffer does not have to involve complicated spreadsheets.
Many households can monitor their reserve using ordinary banking tools, budgeting applications, spreadsheets, or other financial management systems.
The important information includes:
- Current buffer balance
- Target balance
- Recent withdrawals
- Recent contributions
- Upcoming unusual expenses
- Time needed to rebuild the reserve
For a broader overview of tools that can help households organize their finances, the Complete Guide to Money Management Tools can help explain how different financial tracking and planning tools fit into everyday money management.
Cash Buffers Can Make Budgeting More Flexible
A strict budget can sometimes create the impression that every month should look exactly the same.
Real households rarely operate that way.
Expenses move up and down. Bills change. Children have unexpected needs. Cars require maintenance. Household equipment eventually needs replacement.
A cash buffer allows a budget to accommodate some of these changes without being completely rebuilt each time something unexpected occurs.
This creates a more flexible approach to budgeting:
Plan for normal spending.
Reserve cash for fluctuations.
Save separately for known future expenses.
Maintain emergency savings for major disruptions.
Each layer has a different job.
Avoiding an Excessively Large Cash Buffer
While having accessible cash can provide flexibility, there can also be a point where keeping additional money in a low-yield account becomes less useful for a household’s broader financial goals.
The appropriate balance depends on circumstances.
A household may want enough cash to handle ordinary uncertainty without accumulating an unnecessarily large amount that could otherwise be directed toward other priorities.
This is particularly relevant when a household has:
- High-interest debt
- Important long-term savings goals
- Major planned purchases
- Retirement contributions
- Other financial priorities
The goal is not simply to maximize the cash balance. It is to create an appropriate level of liquidity within the household’s overall financial plan.
Reviewing the Buffer Over Time
A cash buffer should not necessarily remain the same forever.
Household circumstances change.
A family might experience:
- A new child
- A job change
- A move
- Higher rent or mortgage costs
- Changes in transportation expenses
- A new income source
- A period of self-employment
- Higher education expenses
- Changes in household size
When these changes occur, the previous buffer target may no longer make sense.
A household can review the reserve periodically and ask:
- Are our monthly expenses higher than before?
- Has our income become less predictable?
- Are we using the buffer frequently?
- Are we rarely touching it?
- Are we rebuilding it quickly enough?
- Are we keeping enough money for known upcoming expenses?
- Is our emergency fund separate and adequate for its intended purpose?
These questions can help keep the buffer aligned with actual household needs.
A Simple Example of a Household Cash Buffer
Consider a household with monthly essential expenses of $3,000.
Its income is relatively stable, but several bills fluctuate throughout the year.
The family decides to establish a $600 cash buffer.
During one month:
- Electricity costs $75 more than expected.
- A household appliance requires a $150 repair.
- Transportation costs increase by $50.
The total unexpected spending is $275.
The family uses part of its buffer rather than borrowing the money.
The remaining buffer is:
$600 − $275 = $325
Over the next few months, the household adds additional money until the buffer returns to $600.
Meanwhile, its emergency savings remain untouched because the expenses were relatively small and temporary.
This example illustrates the purpose of a cash buffer: it absorbs manageable financial disruptions without turning every surprise into a larger financial event.
Cash Buffers Are About Stability, Not Perfection
Household financial planning does not require every month to unfold exactly according to a spreadsheet.
Unexpected expenses are part of everyday life.
A cash buffer recognizes this reality by creating space between a household’s planned finances and the unpredictable details that occur in practice.
It can help manage timing differences, absorb smaller surprises, support irregular income, and reduce dependence on short-term borrowing.
The most effective approach is usually to give the buffer a clear purpose, keep it accessible, monitor its balance, and replenish it after use.
Building More Breathing Room Into Household Finances
A household does not need a massive reserve to benefit from the basic idea behind a cash buffer. Even a modest amount can create useful flexibility when an ordinary expense turns out to be slightly higher than expected.
Over time, the process becomes part of a broader financial system: budgeting handles regular spending, dedicated savings handle known future costs, a cash buffer handles short-term fluctuations, and emergency savings provide protection against larger disruptions.
That structure can make household finances easier to navigate because every pool of money has a defined role.
The result is not a promise that unexpected expenses will disappear. Instead, a cash buffer gives the household more room to respond when real life does not go exactly according to plan.