How Families Can Distinguish Needs From Wants When Spending
Every household faces spending decisions that seem simple at first but become complicated when money is limited. Food, housing, transportation, utilities, school expenses, clothing, entertainment, subscriptions, and personal purchases can all compete for the same income.
One of the most useful skills families can develop is the ability to distinguish needs from wants before spending money. The distinction is not about deciding that wants are always bad or that every need deserves unlimited spending. Instead, it gives households a practical way to determine what should be funded first when resources are limited.
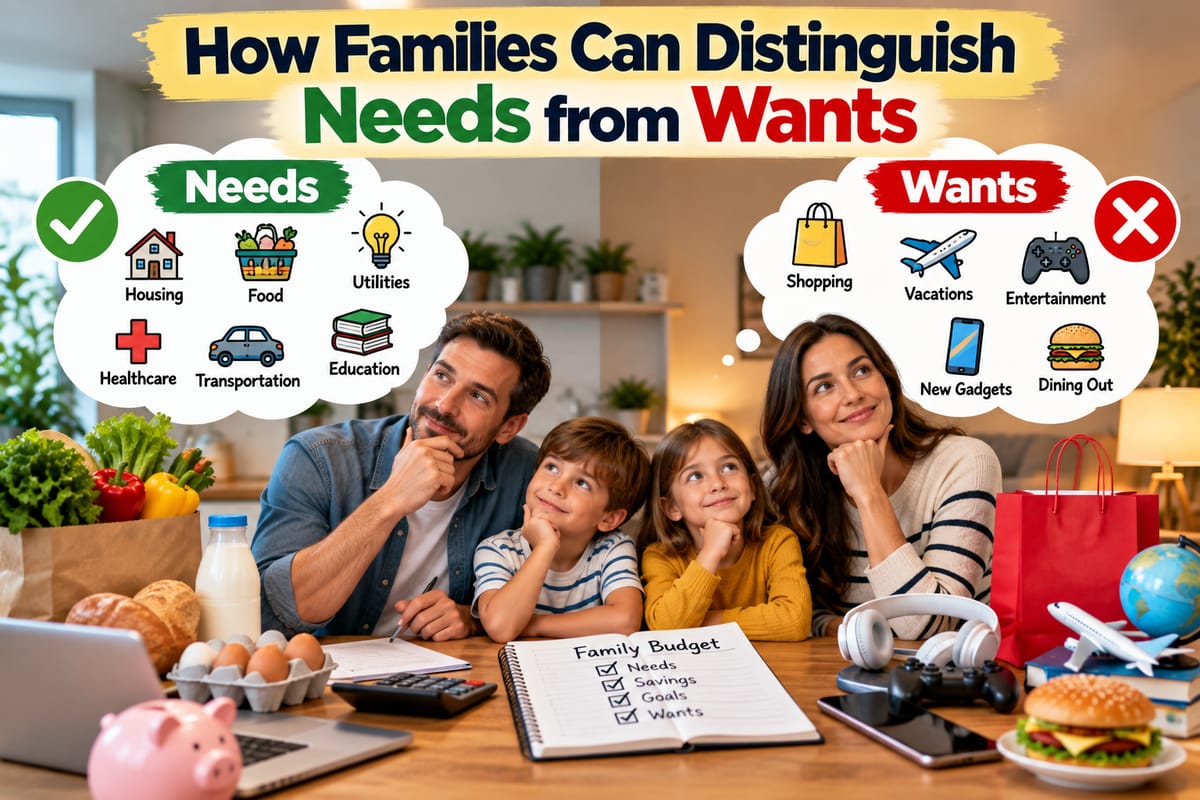
Needs generally relate to things required for health, safety, basic functioning, and essential responsibilities. Wants are purchases that can improve comfort, convenience, enjoyment, or lifestyle but are not essential to meeting those basic requirements.
The challenge is that the line between the two is not always obvious. A smartphone may be a luxury for one household but an important work or school tool for another. A car might be optional in a city with reliable public transportation but essential for a family living far from work, schools, or medical services.
Learning to make these distinctions can help families spend more deliberately, reduce unnecessary purchases, and make room for important financial goals.
What Is a Need?
A need is generally something a household requires to maintain basic living conditions, health, safety, or essential responsibilities.
Common household needs may include:
- Housing
- Basic food
- Utilities
- Essential transportation
- Necessary healthcare
- Basic clothing
- Education-related necessities
- Insurance where appropriate
- Required debt payments
- Essential communication services
- Household and personal hygiene products
The exact list varies from family to family.
For example, heating may be a critical need in a cold climate but less important in a warm one. Transportation may be essential for someone who works in an area without public transit, while another person may be able to walk, cycle, or use public transportation.
The important question is not simply whether something is useful. It is whether the household can reasonably function without it.
What Is a Want?
A want is generally something a person or family would like to have but could live without.
Wants can include:
- Restaurant meals
- Entertainment
- Premium subscriptions
- Designer clothing
- New electronics before existing devices need replacement
- Expensive vacations
- Upgraded vehicles
- Decorative purchases
- Gaming products
- Luxury services
- Convenience purchases
Wants are not necessarily irresponsible.
Families need recreation, enjoyment, social experiences, and opportunities to relax. Spending money on these things can be part of a healthy household budget.
The key is understanding where wants fit within the family’s available resources rather than treating every desirable purchase as an immediate priority.
Why the Difference Matters
Distinguishing needs from wants becomes particularly important when income is limited or expenses are rising.
If a household treats every purchase as equally important, money can disappear quickly without supporting the family’s most important objectives.
A family may spend heavily on convenience purchases while struggling to cover an upcoming school expense. Another household might regularly upgrade electronics while carrying expensive debt or having little emergency savings.
Separating needs from wants creates a hierarchy.
Essential expenses can be addressed first. Important financial goals can receive appropriate funding next. Discretionary spending can then be considered using whatever remains.
This approach is especially useful when families are trying to balance current spending with longer-term financial security.
Needs and Wants Are Not Always Universal
One of the biggest mistakes families can make is assuming that every purchase falls into the same category for everyone.
Consider a laptop.
For one household, replacing an older laptop might be a want because the existing device still performs all necessary tasks. For another household, a reliable computer might be a need because a parent works remotely or a child requires it for school.
The same applies to transportation.
A second vehicle may be unnecessary for one family but essential for another if parents work different schedules and public transportation is unavailable.
Even internet access can change categories. A high-speed connection used primarily for entertainment may be discretionary, while a reliable connection required for remote employment or education can become an essential household expense.
The context matters.
Ask What Happens If We Do Not Buy It?
One of the simplest ways to evaluate a purchase is to ask:
What happens if we do not buy this right now?
If the answer involves an immediate problem with food, shelter, health, safety, work, education, or another essential responsibility, the purchase may be a need.
If the answer is primarily that someone will be disappointed, inconvenienced, or unable to enjoy something immediately, it may be a want.
This question does not automatically settle every decision, but it creates useful distance between an actual requirement and an emotional impulse.
Use a Priority System Instead of a Simple Yes-or-No Rule
Needs and wants do not have to be treated as two completely separate categories.
A more practical system is to create several levels of priority.
Priority 1: Essential Needs
These are expenses that should generally be addressed first.
Examples include:
- Housing
- Basic food
- Essential utilities
- Necessary healthcare
- Required transportation
- Critical insurance
- Minimum debt obligations
Priority 2: Important Financial Responsibilities
These may not be immediate survival needs but can strongly affect household stability.
Examples include:
- Emergency savings
- Retirement contributions
- Necessary repairs
- Education savings
- Paying down high-cost debt
- Replacing essential household equipment
Priority 3: Valuable Wants
These purchases provide genuine value but can usually be delayed or adjusted.
Examples might include:
- Family outings
- Hobbies
- Moderate travel
- Restaurant meals
- Entertainment
- Home improvements that are primarily cosmetic
Priority 4: Optional Purchases
These are items that may provide enjoyment but have little effect on the household’s essential needs or long-term objectives.
Examples include impulse purchases, unnecessary upgrades, duplicate items, and convenience spending that could easily be avoided.
This approach allows families to enjoy their money without allowing optional purchases to crowd out essential priorities.
Build the Distinction Into the Family Budget
A family budget provides a practical framework for separating needs and wants.
When households create a budget, they can identify recurring expenses, estimate variable costs, and decide how much money is available for discretionary spending.
Families that are new to budgeting can use How to Build a Family Budget as a starting point for organizing income and expenses.
A useful household budget might divide spending into categories such as:
| Category | Examples | Typical Priority |
|---|---|---|
| Housing | Rent, mortgage, basic maintenance | Essential |
| Food | Groceries, basic meals | Essential |
| Utilities | Electricity, water, basic communication | Essential |
| Transportation | Necessary fuel, transit, vehicle costs | Essential |
| Healthcare | Medical care, prescriptions | Essential |
| Financial goals | Savings, debt reduction | Important |
| Entertainment | Movies, games, streaming | Discretionary |
| Dining out | Restaurants, takeout | Discretionary |
| Luxury purchases | Premium products and upgrades | Optional |
The exact categories will differ between households, but the exercise makes spending patterns easier to see.
Watch for Wants Disguised as Needs
Marketing and convenience can make wants feel essential.
A product may be advertised as something people “need” to save time, improve their lifestyle, or keep up with others. That does not necessarily make it a household necessity.
Before purchasing, ask:
- Do we already own something that performs this function?
- Does the existing item still work?
- Is the purchase required now?
- What problem does it actually solve?
- Could we delay the purchase?
- Is there a less expensive alternative?
- Would we still want it if nobody else knew we bought it?
These questions can expose purchases driven primarily by impulse or social pressure.
Convenience Is Not the Same as Necessity
Convenience spending is one of the easiest areas for families to overlook.
Buying prepared meals, paying for delivery, subscribing to multiple services, or choosing premium versions of everyday products can save time or effort.
Those benefits can be real.
The issue is whether the convenience fits within the household’s priorities.
For example, paying for occasional food delivery during an exceptionally busy week may be reasonable. Ordering delivery several times a week without accounting for the cost can gradually consume money that could have been used elsewhere.
The goal is not to eliminate convenience. It is to recognize its cost and decide whether the benefit is worth it.
Look at Recurring Wants
Small recurring expenses can have a larger impact than occasional purchases.
A single subscription might seem inexpensive. Several subscriptions can become a meaningful monthly expense.
Families should periodically review:
- Streaming services
- Gaming subscriptions
- Premium apps
- Memberships
- Cloud storage
- Delivery programs
- Fitness services
- Digital publications
- Automatic product subscriptions
If a household no longer uses a service, canceling it can be an easy way to reduce spending.
Families looking for practical ways to identify these leaks can also explore How to Reduce Unnecessary Household Spending.
Distinguish Replacement From Upgrading
Another useful test involves household products that already exist.
Replacing something because it no longer works is different from replacing something because a newer version is available.
For example:
- A broken refrigerator may require replacement.
- A functioning refrigerator with a newer model available may not.
- Worn-out shoes may need replacing.
- Buying another pair because a new style is fashionable may be a want.
- A damaged phone may need replacement.
- Upgrading a functioning phone every year is usually discretionary.
This distinction can help families avoid turning ordinary upgrades into recurring essential expenses.
Consider the Total Cost, Not Just the Purchase Price
A purchase can create additional expenses after the initial transaction.
For example, buying a car may involve:
- Fuel
- Insurance
- Maintenance
- Repairs
- Parking
- Registration
- Financing costs
A larger home can mean higher:
- Utilities
- Property-related costs
- Maintenance expenses
- Furnishing costs
Even a relatively inexpensive hobby can become costly when equipment, memberships, transportation, and replacement supplies are considered.
Before classifying something as affordable, families should consider the full cost of ownership.
Use a Waiting Period for Wants
A waiting period can help reduce impulse spending.
For inexpensive wants, a family might wait until the next day before buying. For larger purchases, waiting a week or even a month can provide more perspective.
During the waiting period, ask:
- Do we still want it?
- Have we found a better use for the money?
- Is there a less expensive alternative?
- Does it support one of our financial goals?
- Is the current item genuinely inadequate?
- Will we still use it several months from now?
If the desire disappears, the family may have avoided an unnecessary expense.
If the purchase remains important after careful consideration, it can be made intentionally rather than impulsively.
Connect Spending Decisions to Family Goals
Needs-versus-wants decisions become easier when a family has clearly defined financial objectives.
Suppose a household is saving for a home, education, an emergency fund, debt repayment, or another major objective. Every discretionary purchase can then be considered in relation to that goal.
For example, spending $100 on an optional purchase does not merely mean losing $100. It also means that the same $100 cannot be used toward another objective at that moment.
Families working on this process can review How Families Can Set, Prioritize and Achieve Household Financial Goals for a broader approach to setting household priorities.
The goal is not to reject every want. It is to understand the trade-off.
Teach Children the Difference Between Needs and Wants
Children can learn this concept through everyday decisions.
A parent might explain that groceries are needed while a particular snack or toy is wanted. Clothing may be necessary, while a premium brand may be optional.
Simple conversations can help children understand that money is limited and choices have consequences.
For example, if a child has a fixed amount of spending money, they can decide between:
- Buying something immediately
- Saving for a larger item
- Spending part of the money and saving the rest
These decisions introduce concepts such as delayed gratification, opportunity cost, and prioritization.
The lesson should not be that wanting something is wrong. Instead, children can learn that wants are choices that need to fit within available resources.
Make Room for Wants in the Budget
A household budget that contains nothing enjoyable can be difficult to maintain.
If families attempt to eliminate all discretionary spending, they may eventually abandon the budget altogether.
Instead, households can deliberately allocate money for wants.
A family might create a monthly entertainment amount, personal spending allowance, dining-out budget, or vacation fund.
Once the amount has been set aside, family members can spend it without repeatedly questioning every small purchase, provided the spending stays within the agreed limit.
This creates a healthier distinction between planned discretionary spending and unplanned spending.
How Families Can Make Decisions When Money Is Tight
When resources are limited, families may need to make difficult choices between competing needs.
For example, a household might need to decide whether to repair an appliance, replace worn clothing, pay an upcoming bill, or cover another necessary expense.
In these situations, the question is no longer simply “Is this a need?”
Several needs may compete for the same money.
Families can compare:
- How urgent the expense is.
- What happens if it is delayed.
- Whether there is a temporary alternative.
- Whether the expense protects health or safety.
- Whether the cost can be reduced.
- Whether another expense can be postponed.
For a deeper framework, How Families Can Make Financial Decisions With Limited Resources explores how households can prioritize competing financial demands when they cannot fund everything at once.
Common Mistakes Families Make
Several habits can make it harder to distinguish needs from wants.
Treating Every Preference as a Necessity
A person may strongly prefer a particular product, brand, or service without actually needing it.
Preference and necessity are different.
Ignoring Small Purchases
Small purchases can become significant when repeated frequently.
A family should look at spending patterns rather than judging each transaction independently.
Using Credit to Make Wants Feel Affordable
A purchase may appear manageable because the immediate payment is small. However, interest and future payments can make the real cost substantially higher.
Comparing Lifestyle Spending With Other Families
Another household may have a different income, debt level, savings position, or financial priorities.
Trying to match another family’s spending can lead to decisions that do not fit one’s own circumstances.
Assuming Cheap Means Affordable
A low price does not automatically make something financially appropriate.
A household can still overspend by repeatedly buying inexpensive items that are unnecessary.
A Simple Needs-and-Wants Checklist
Before making a discretionary purchase, families can run through a short checklist:
1. Do we need it now?
If the purchase can safely wait, there may be an opportunity to reconsider it.
2. What happens if we do not buy it?
Identify the actual consequence rather than the emotional reaction.
3. Do we already own something that works?
Existing alternatives can eliminate the need for another purchase.
4. Does it support a household priority?
Consider savings, debt reduction, education, housing, health, and other goals.
5. What is the total cost?
Include maintenance, subscriptions, accessories, transportation, and financing where applicable.
6. Is there a less expensive alternative?
Compare options before committing.
7. Will we still value it later?
A waiting period can reveal whether the purchase has lasting value.
A Practical Family Spending Example
Imagine a family has money left after covering its essential monthly bills.
One family member wants a new television, another wants to eat at a restaurant, and the household is also trying to build an emergency fund.
All three options may be desirable, but they have different financial implications.
The family could first determine whether the television is actually needed. If the existing television works, it is likely a want. The restaurant meal is also a want. The emergency fund, meanwhile, represents a financial priority.
The family could choose to save most of the available money while setting aside a smaller amount for the restaurant meal.
This does not mean the family has rejected enjoyment. It means the household has given different priorities different amounts of money.
That is the central purpose of distinguishing needs from wants.
Make the Process a Regular Family Habit
Needs-versus-wants decisions become easier when families review spending regularly instead of waiting for a financial problem.
A monthly review can ask:
- Which expenses increased?
- Which purchases were necessary?
- Which purchases were optional?
- Which recurring services are no longer valuable?
- Did we make progress toward our goals?
- Are there expenses we can reduce?
- Are our priorities still the same?
As circumstances change, the classification can change too.
A want can become a need when circumstances change, while something previously considered essential can become optional.
The objective is not to create permanent labels for every expense. It is to create a habit of thinking carefully before money leaves the household.
Turning Spending Choices Into Better Financial Habits
Distinguishing needs from wants gives families a practical framework for making everyday financial decisions.
It encourages households to cover essential expenses first, protect important financial priorities, and then use remaining resources for enjoyment and convenience. It also makes it easier to identify unnecessary spending without treating every nonessential purchase as irresponsible.
The most useful approach is not to eliminate wants. Families can enjoy meals out, hobbies, entertainment, travel, technology, and other discretionary purchases when those expenses fit within their resources.
The key is knowing what each purchase represents, understanding its opportunity cost, and making the decision deliberately.
Over time, that awareness can turn ordinary shopping decisions into a stronger household money-management habit—one where spending reflects what the family actually needs, what it genuinely values, and what it is working toward next.