Joint or Separate Bank Accounts for Couples
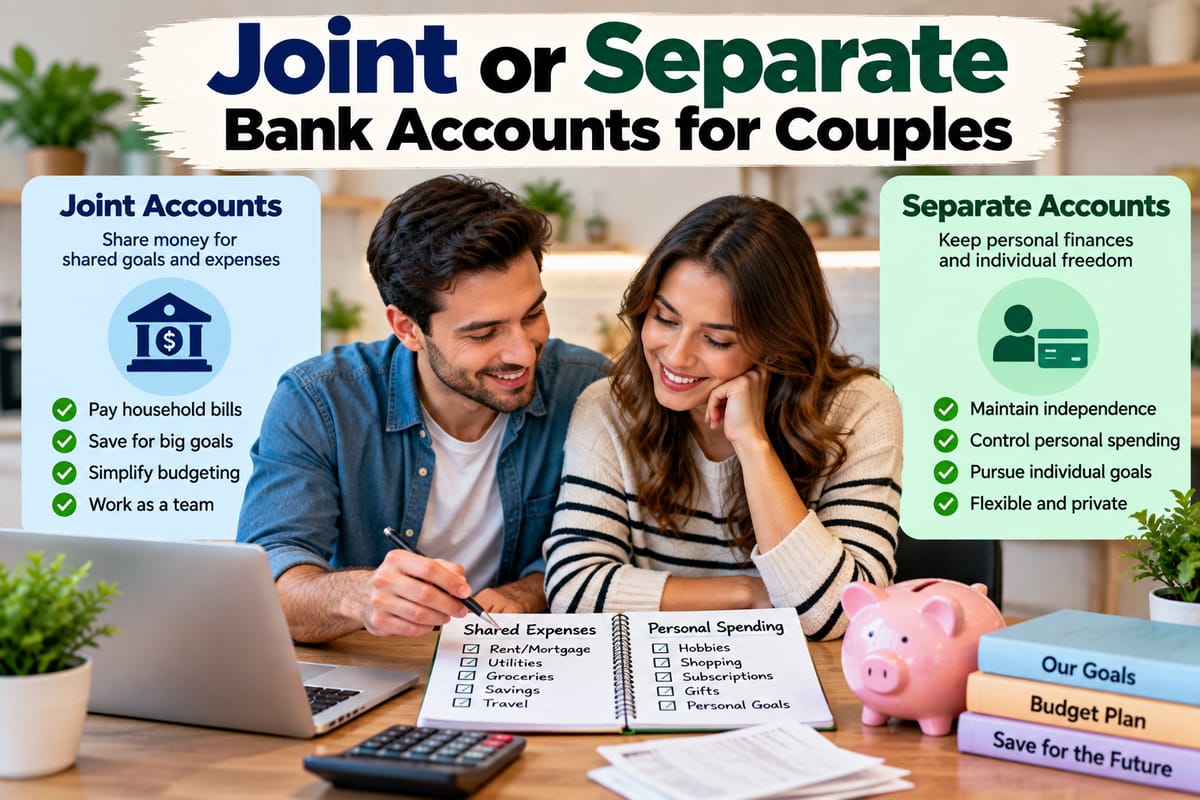
Deciding whether couples should use joint or separate bank accounts is one of the most practical financial decisions partners can make together. There is no single arrangement that works for every household because couples have different incomes, spending habits, financial goals, responsibilities, and preferences for managing money.
Some couples prefer to combine nearly everything into joint accounts. Others keep their finances largely separate. Many choose a hybrid approach, maintaining individual accounts while also contributing to a shared account for household expenses and common goals.
The important issue is not simply whether an account is joint or separate. It is whether the system gives both partners a clear understanding of their responsibilities, provides enough flexibility for individual spending, and supports the couple’s shared financial priorities.
For a broader look at managing money as partners, the Complete Guide to Couples and Money Management explores the wider financial decisions couples may need to make together.
What Is a Joint Bank Account?
A joint bank account is an account owned by two or more people.
For couples, a joint account can provide a shared place to manage money used for household expenses and common financial objectives.
Depending on the bank and account agreement, both account holders may be able to:
- Deposit money
- Withdraw funds
- Make payments
- Transfer money
- View transactions
- Manage recurring bills
- Access account statements
The exact rights and responsibilities associated with a joint account depend on the financial institution and account agreement.
A joint account can make household money management simpler because both partners can see the same pool of funds.
What Are Separate Bank Accounts?
Separate accounts are accounts held individually by each partner.
Each person generally manages their own account and decides how to use money held there, subject to the applicable account terms.
Separate accounts can allow partners to maintain financial independence while still working together on household responsibilities.
For example, one partner might receive their salary into their personal account while the other does the same. They can then contribute agreed amounts toward rent, utilities, groceries, savings, and other shared expenses.
Separate accounts do not necessarily mean that a couple keeps their finances secret from each other.
The arrangement can work effectively when both partners understand the household’s overall financial situation.
Why Couples Choose Joint Accounts
Some couples prefer joint accounts because they simplify shared finances.
When income is pooled, both partners can see the money available for household expenses and goals.
Potential advantages include:
- Easier bill management
- Greater visibility into household cash flow
- Simpler budgeting
- Shared access to household funds
- Easier coordination of savings
- Fewer calculations when dividing expenses
- A stronger sense of shared financial responsibility
For couples who view most income and expenses as shared, a joint account can provide a straightforward structure.
Why Couples Choose Separate Accounts
Separate accounts can provide greater individual control.
Each partner may have different spending preferences, hobbies, financial priorities, or approaches to money. Maintaining an individual account can allow each person to manage some spending without requiring approval for every purchase.
Potential benefits include:
- Greater personal autonomy
- Easier individual budgeting
- Privacy for discretionary purchases
- Independence in managing personal expenses
- Clear ownership of certain funds
- Flexibility when incomes differ
Separate accounts can be particularly useful for couples who value financial independence while still sharing major household responsibilities.
The Hybrid Approach
A hybrid system combines joint and separate accounts.
For example, each partner could maintain:
- An individual checking account
- A joint household account
- A joint savings account
Each person deposits money into their personal account. An agreed amount is then transferred to the joint account to cover shared expenses.
The joint account might pay for:
- Housing
- Utilities
- Groceries
- Insurance
- Child-related expenses
- Transportation
- Shared subscriptions
- Household repairs
The couple can also contribute to joint savings for goals such as an emergency fund, vacation, home purchase, or other major expenses.
Meanwhile, each partner retains some personal money for discretionary spending.
How Couples Can Decide Which Structure Fits
Rather than choosing an account structure based on what other couples do, partners can start by examining their own circumstances.
Useful questions include:
- How do we want to handle household expenses?
- Are our incomes similar or significantly different?
- Do we have children?
- What financial obligations do we each bring into the relationship?
- Do we have individual debts?
- What financial goals do we share?
- How much financial independence does each partner value?
- How comfortable are we with fully shared finances?
- How often do we want to review our money?
- What happens if one partner temporarily earns less?
The answers can help determine whether joint, separate, or hybrid accounts make the most practical sense.
Joint Accounts Can Make Shared Expenses Simpler
One of the strongest arguments for joint accounts is convenience.
Suppose a couple has a joint account funded with money intended for household expenses.
Instead of calculating who pays each individual bill, the couple can use the shared account for agreed expenses.
For example:
| Expense | Payment source |
|---|---|
| Rent or mortgage | Joint account |
| Electricity | Joint account |
| Groceries | Joint account |
| Internet | Joint account |
| Shared insurance | Joint account |
| Personal hobbies | Individual accounts |
| Personal shopping | Individual accounts |
| Individual subscriptions | Individual accounts |
This arrangement can reduce the number of financial calculations required each month.
Separate Accounts Can Make Personal Spending Easier
Personal spending can become a source of tension when couples have very different preferences.
One partner may enjoy eating at restaurants, while another prefers saving money. One might spend more on hobbies, while the other prioritizes travel.
Separate personal accounts can provide a defined amount of financial independence.
For example, after contributing to household expenses and savings, each partner might retain money in their individual account for discretionary purchases.
This does not mean that partners stop communicating about money. It simply establishes a boundary around certain personal spending.
Income Differences Matter
Couples do not always earn the same amount.
If one partner earns substantially more than the other, splitting every household bill 50/50 may place a larger relative burden on the lower-income partner.
For some couples, proportional contributions may be more practical.
For example, suppose one partner earns 60% of the household’s combined income and the other earns 40%.
The couple could agree to contribute toward shared expenses using a similar proportion.
Another approach is to combine income in a joint account and treat household resources as shared.
There is no universal formula. The important point is to discuss how contributions should work before resentment develops.
Equal Contributions Versus Proportional Contributions
Consider a household with $4,000 in monthly shared expenses.
If both partners contribute $2,000, the arrangement is equal in dollar terms.
But if one partner earns $3,000 per month and the other earns $7,000, each contributing $2,000 represents very different percentages of their individual income.
A proportional system might instead divide contributions according to income.
For example:
- Partner A earns 30% of combined income.
- Partner B earns 70% of combined income.
- Shared expenses are divided using the same proportions.
This is only one possible method. Some couples may prefer equal contributions, while others may treat all income as shared.
The important part is agreeing on the approach openly.
Financial Transparency Is Essential
Regardless of account structure, couples benefit from knowing the broad financial picture.
Keeping separate accounts should not mean hiding:
- Debt
- Major financial obligations
- Significant purchases
- Income
- Financial commitments
- Major savings goals
- Accounts that materially affect household finances
Financial transparency allows partners to make decisions based on accurate information.
For practical ideas on creating openness around household finances, How to Build Financial Transparency at Home provides a useful framework.
Separate Does Not Have to Mean Secret
There is an important difference between financial independence and financial secrecy.
A couple can maintain separate accounts while openly discussing their overall financial situation.
For example, each partner may control their personal account, but both know:
- How much each person earns
- What major household bills cost
- How much debt the household carries
- What the family is saving for
- How much emergency savings exists
- What financial commitments affect the household
The couple simply chooses not to pool every dollar.
This can provide autonomy without creating unnecessary uncertainty.
Joint Does Not Mean Every Purchase Requires Permission
A joint account can also work without requiring partners to monitor every small transaction.
Couples can establish spending rules.
For example, they might agree that routine household expenses can be paid from the joint account without discussion, while purchases above a certain amount require a conversation.
The threshold will differ between households.
A couple with substantial disposable income may use a higher threshold than a household operating on a tight budget.
The purpose is to create reasonable expectations rather than micromanage each other’s spending.
Establish Rules for Joint Accounts
Before opening or actively using a joint account, couples should discuss how it will operate.
Important questions include:
- What money will go into the account?
- Which expenses will be paid from it?
- How much can either person spend without consulting the other?
- How will large purchases be handled?
- Will both partners monitor transactions?
- How often will the account be reviewed?
- What happens if one person earns less temporarily?
- How will savings contributions work?
Clear rules can prevent disagreements later.
Discuss Money Regularly
Account structure alone cannot solve communication problems.
A couple can have perfectly organized bank accounts and still experience financial conflict if partners rarely discuss money.
Regular conversations can cover:
- Upcoming bills
- Spending
- Savings
- Debt
- Major purchases
- Changes in income
- Financial goals
- Unexpected expenses
For more discussion of this broader relationship, Why Financial Communication Matters at Home examines how communication can affect household financial decision-making.
Create Shared Financial Goals
Whether accounts are joint or separate, couples often have goals that require cooperation.
These might include:
- Building an emergency fund
- Buying a home
- Paying off debt
- Saving for education
- Starting a business
- Preparing for retirement
- Taking a major vacation
- Replacing a vehicle
- Preparing for future family expenses
A joint savings account can be useful for some shared goals, while individual accounts can continue to handle personal objectives.
The account structure should support the goals rather than becoming the goal itself.
Joint Savings Accounts
A joint savings account can provide a dedicated place for money intended for shared objectives.
For example, a couple might establish separate savings categories for:
- Emergency savings
- Home repairs
- Travel
- Annual insurance payments
- Major purchases
- Education
- Other planned expenses
Some banks offer multiple savings products or account features that can help organize these goals.
The appropriate account depends on factors such as accessibility, fees, interest, withdrawal rules, and the couple’s objectives.
Emergency Savings and Account Structure
Emergency savings deserve particular attention because they are intended for unexpected needs.
A couple might keep emergency funds in a joint account if the money is intended to protect the household as a whole.
Alternatively, each partner might maintain some individual savings alongside shared emergency funds.
The important issue is that both partners understand:
- How much emergency savings exists
- Where it is held
- What qualifies as an emergency
- Who can access it
- How the fund will be replenished after use
This avoids confusion when an unexpected expense occurs.
Consider Existing Debt
Couples may enter a relationship with different financial histories.
One partner might have student loans, credit card balances, personal loans, or other obligations while the other has relatively little debt.
Combining accounts does not automatically combine every financial obligation.
Couples should understand the legal and financial implications of joint accounts and jointly held debt in their jurisdiction before changing ownership or combining financial products.
The practical goal is to ensure that both partners understand how individual obligations interact with household finances.
Bank Account Types Matter
The decision is not simply “joint versus separate.”
There are different types of bank accounts, each designed for particular purposes.
These can include:
- Checking accounts
- Savings accounts
- Money market accounts
- Certificates of deposit
- Specialized savings products
- Other deposit accounts
The features, fees, interest rates, withdrawal rules, and access arrangements can vary.
For a broader explanation of these products, the Complete Guide to Bank Accounts and Account Types can help couples understand the different options before choosing an account structure.
How a Hybrid System Can Work
A hybrid system might look like this:
Individual Account — Partner A
Used for:
- Personal spending
- Individual subscriptions
- Personal hobbies
- Personal savings goals
Individual Account — Partner B
Used for:
- Personal spending
- Individual subscriptions
- Personal hobbies
- Personal savings goals
Joint Checking Account
Used for:
- Housing
- Utilities
- Groceries
- Shared transportation
- Household expenses
Joint Savings Account
Used for:
- Emergency savings
- Major purchases
- Shared goals
This structure creates three useful boundaries:
Household money: shared responsibilities and goals.
Personal money: individual discretionary spending.
Shared savings: money reserved for objectives that belong to both partners.
What If One Partner Is a Stay-at-Home Parent?
A household may have one partner earning most or all of the income while another partner handles substantial unpaid responsibilities.
In such situations, completely separate finances can sometimes make access to household money more complicated.
Couples should consider whether both partners have reasonable access to money needed for household and personal expenses.
The person earning the income should not automatically be treated as the only person with financial authority simply because their name appears on a paycheck.
The arrangement should reflect the couple’s shared responsibilities and agreed financial structure.
What If One Partner Earns Irregular Income?
Some people work as freelancers, contractors, business owners, seasonal workers, or commission-based employees.
Their income may vary considerably from month to month.
A joint account can make household budgeting easier if income is pooled, but the couple may need a system for handling unusually high and low income periods.
For example, during a high-income month, they could prioritize:
- Building cash reserves
- Funding irregular expenses
- Paying necessary bills
- Increasing savings
During a low-income month, the household can rely on previously established reserves where appropriate.
The account structure should accommodate the reality of the household’s cash flow.
Consider Automatic Transfers
Automation can simplify a joint-and-separate system.
For example, on payday:
Partner A’s income → Individual account → Joint account contribution
Partner B’s income → Individual account → Joint account contribution
Then:
Joint account → Household bills
Joint savings → Shared goals
Automation reduces the need to remember every transfer manually.
However, couples should review automatic transfers periodically to ensure they still match their income, expenses, and goals.
Review the Arrangement as Circumstances Change
The account structure that works early in a relationship may not work forever.
Circumstances can change because of:
- Marriage
- Children
- Career changes
- Relocation
- Business ownership
- Retirement
- Major changes in income
- New debt
- Homeownership
- Health-related expenses
- Changes in financial goals
A couple should be willing to adjust its system when circumstances change.
There is no requirement that a couple choose one account structure permanently.
Common Mistakes Couples Make
Assuming There Is One Correct System
Different households have different needs.
A system that works well for one couple may create unnecessary friction for another.
Combining Everything Without Discussing Expectations
Opening a joint account does not automatically establish rules about spending, savings, or responsibilities.
Those expectations need to be discussed.
Keeping Everything Separate Without a Shared Plan
Separate accounts can work, but the household still needs a method for managing common expenses and goals.
Hiding Financial Information
Privacy and secrecy are different. Partners need enough transparency to make informed household decisions.
Splitting Every Expense Exactly in Half
A 50/50 arrangement may not always reflect differences in income or responsibilities.
Ignoring Irregular Expenses
Annual insurance, repairs, school costs, taxes, travel, and other non-monthly expenses can disrupt a system that only accounts for regular bills.
Never Reviewing the Arrangement
Income, expenses, and priorities change. Account structures should be reviewed periodically.
Questions Couples Should Discuss Before Choosing
A useful conversation might begin with the following questions:
- What does money represent to each of us?
- What expenses do we consider shared?
- What expenses do we consider personal?
- How should household bills be divided?
- Should contributions be equal or proportional?
- How much personal spending should each person control?
- What financial goals do we share?
- What financial information should we disclose?
- How will we handle large purchases?
- How will we handle financial emergencies?
- How often will we review our accounts?
- What changes would cause us to reconsider the system?
These questions are often more important than whether the couple ultimately chooses one joint account or several separate accounts.
A Simple Comparison
| Feature | Joint Accounts | Separate Accounts | Hybrid System |
|---|---|---|---|
| Shared expense management | Simple | Requires coordination | Simple for shared bills |
| Individual autonomy | Lower | Higher | Moderate to high |
| Household visibility | High | Can be lower | High if transparent |
| Personal spending flexibility | May require agreed rules | High | High |
| Budget coordination | Centralized | Requires more planning | Shared expenses centralized |
| Suitable for shared goals | Convenient | Requires coordination | Convenient |
| Financial independence | Lower | Higher | Balanced |
| Administrative complexity | Low | Can be higher | Moderate |
These are structural differences rather than guarantees. The actual experience depends on how the couple manages the accounts.
There Is No Requirement to Choose One Extreme
Couples sometimes approach this decision as though they must choose between putting every dollar into one account or keeping all finances completely separate.
A hybrid approach demonstrates that there is a middle ground.
Partners can share what they need to share while retaining individual control over some money.
For example, a couple might decide that housing, food, utilities, savings, and childcare are joint responsibilities, while hobbies, gifts, personal shopping, and individual interests are handled separately.
The exact boundaries can be customized.
The Most Important Part Is the Agreement Behind the Accounts
Bank accounts are tools. They do not determine how a couple communicates, shares responsibilities, or makes decisions.
A joint account can work well when both partners understand the rules. Separate accounts can work well when partners maintain transparency about household finances. A hybrid system can combine shared responsibilities with individual independence.
The strongest arrangement is usually the one that reflects the couple’s actual circumstances rather than following a universal formula.
Partners can start by listing shared expenses, individual obligations, income sources, savings goals, and preferred levels of financial independence. From there, they can decide which money should be shared, which should remain individual, and how often the system should be reviewed.
As financial circumstances change, the arrangement can change too. What matters most is that both partners understand how their money system works, have reasonable access to the resources they are responsible for, and participate in the financial decisions that affect their household.