How Credit Limits and Loan Amounts Work
Credit can make it possible to pay for major purchases, manage unexpected expenses and spread costs over time. But borrowing is not unlimited. Credit cards typically come with credit limits, while loans are approved for specific amounts based on factors such as income, credit history, existing debts and the lender’s policies.
Understanding how credit limits and loan amounts work can make borrowing easier to manage. It can also help borrowers understand why two people applying for similar financial products may receive very different offers.
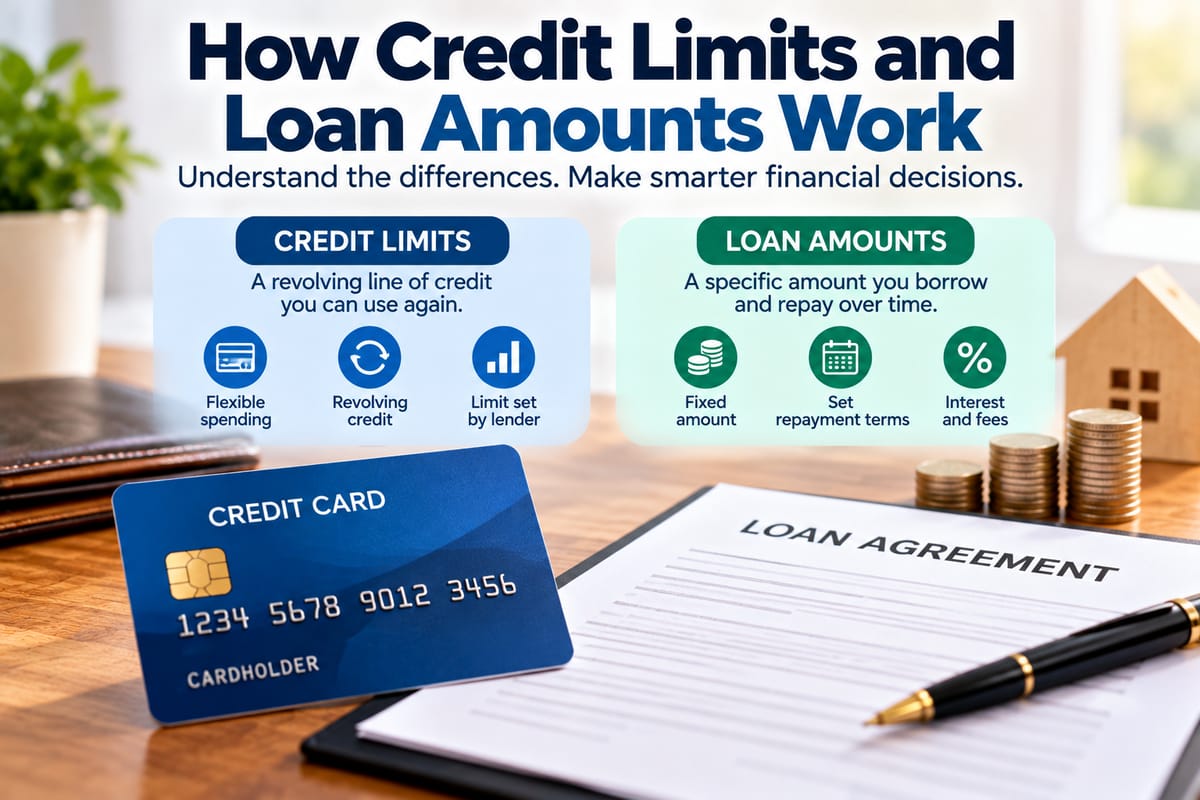
Although credit cards and loans both involve borrowing money, they operate differently. A credit card provides access to a revolving line of credit, while a loan generally provides a specific amount that is repaid according to an agreed schedule.
What Is a Credit Limit?
A credit limit is the maximum amount a lender allows a borrower to have outstanding on a revolving credit account.
For example, if a credit card has a $5,000 limit, the cardholder can generally have up to $5,000 in outstanding balances at one time, subject to the account’s terms and available credit.
A credit limit is not the same as an amount that the borrower should necessarily spend.
Someone with a $5,000 limit does not need to use the entire amount. In fact, using only what can comfortably be repaid can make credit easier to manage.
Credit cards are explained in greater detail in this complete guide to credit cards and how they work.
What Is a Loan Amount?
A loan amount is the principal amount a lender agrees to provide to a borrower.
For example, someone might apply for a $20,000 personal loan and receive approval for that amount. The borrower then repays the principal, along with applicable interest and fees, according to the loan agreement.
Unlike a credit card, a typical installment loan does not normally provide a reusable pool of credit after each payment.
If a borrower takes a $20,000 loan and pays it down to $15,000, the remaining $5,000 is not automatically available to borrow again unless the product specifically allows additional borrowing.
Credit Limits and Loan Amounts Are Different
The two concepts can look similar because both represent access to borrowed money, but their structures are different.
| Credit Limit | Loan Amount |
|---|---|
| Maximum available balance on revolving credit | Amount provided under an installment loan |
| Credit can generally be reused as balances are repaid | Usually paid out once |
| Available credit changes as the balance changes | Outstanding principal declines as payments are made |
| Common with credit cards | Common with personal, auto and other installment loans |
| Interest may depend on the balance carried | Interest is generally calculated according to the loan’s terms |
Understanding this difference is important when comparing different types of borrowing.
How Lenders Determine Credit Limits
Lenders generally consider several factors when establishing a credit limit.
The exact criteria vary between financial institutions and products, but commonly considered information can include:
- Credit history
- Income
- Existing debt obligations
- Payment history
- Credit utilization
- Length of credit history
- Information contained in credit applications
- The lender’s internal policies
- The type of credit product
A lender may use automated systems and other risk-assessment methods to determine how much credit to make available.
A strong credit profile does not guarantee a particular credit limit, because lenders can use different criteria and account for circumstances that vary between applicants.
How Lenders Determine Loan Amounts
Loan approval can involve many of the same considerations, but the lender also has to determine whether the proposed loan amount is manageable under its underwriting criteria.
Factors can include:
Income
Income provides information about a borrower’s ability to make required payments.
The lender may consider the amount, stability and source of income depending on the product and its requirements.
Existing Debt
A borrower who already has substantial financial obligations may have less room for another monthly payment.
Lenders may therefore examine existing debts when assessing an application.
Credit History
Past borrowing behavior can provide information about how a borrower has managed credit.
Payment history, outstanding balances and other information may be considered.
For a broader explanation of these factors, the complete guide to credit scores and credit reports provides additional context.
Loan Purpose
Some lenders consider how borrowed money will be used.
Different types of loans may have different underwriting requirements, maximum amounts and repayment structures.
Loan Term
The length of the repayment period can affect affordability.
A longer repayment period may reduce the scheduled payment in some cases, but it can also mean paying interest over a longer period.
Why Two Borrowers Can Receive Different Limits
Credit decisions are generally based on information about the individual borrower and the specific financial product.
As a result, two people applying for similar credit may receive different limits or loan amounts.
For example, one applicant might have:
- Higher income
- Lower existing debt
- Longer credit history
- Different payment history
- Different application information
The lender may therefore determine that the two applications present different levels of lending risk or repayment capacity.
The lender’s own policies can also produce different decisions even when two borrowers appear similar.
What Affects a Credit Card’s Available Credit?
A credit card’s available credit generally depends on the assigned credit limit and the amount currently charged or otherwise counting toward the balance.
Suppose a card has a $4,000 limit and the current balance is $1,000.
Ignoring pending transactions and other account-specific factors, approximately $3,000 remains available.
If the balance increases to $2,500, the available amount generally falls accordingly.
Making payments can restore available credit, although the exact timing depends on the card issuer’s policies and how payments are processed.
What Happens When You Reach Your Credit Limit?
When a credit card balance reaches its available limit, additional transactions may be declined or otherwise handled according to the card’s terms.
Reaching the limit can also leave the borrower with little or no available credit for emergencies.
It is therefore important to view the credit limit as a maximum permitted balance rather than a spending target.
What Is Credit Utilization?
Credit utilization generally describes the relationship between revolving credit balances and available revolving credit limits.
For example, someone with a $2,000 balance on a card with a $10,000 limit has a 20% balance-to-limit ratio.
Utilization can be considered both for an individual revolving account and across multiple revolving accounts.
Credit utilization is one component that can be relevant to credit scoring models, although scoring systems differ in how they calculate and use information.
A credit limit itself does not automatically mean that a borrower has good or bad credit. The broader credit profile matters.
Can a Credit Limit Change?
A credit limit can sometimes change over the life of an account.
A lender may increase or decrease a limit based on its policies and information available about the account and borrower.
In some cases, borrowers can request a higher limit.
An increase can provide additional available credit, but it does not automatically mean that spending more is financially appropriate.
Similarly, a lower credit limit can reduce the amount available to borrow.
The specific rules for changes vary by lender and account agreement.
How Loan Amounts Affect Monthly Payments
The amount borrowed is one of the major factors affecting the size of a loan payment.
Other important factors include:
- Interest rate
- Repayment period
- Payment frequency
- Fees
- Loan structure
Consider a simplified example.
A borrower takes a $10,000 loan. If the repayment period is relatively short, the principal generally has to be repaid over fewer payments. A longer term spreads repayment over more periods.
However, comparing loans only by the monthly payment can be misleading.
A lower monthly payment may result from a longer repayment period, which can increase the total amount of interest paid over the life of the loan.
Loan Amount Versus Total Repayment
The amount borrowed is not necessarily the total amount eventually paid back.
Suppose someone borrows $15,000. The total repayment could be higher because interest and applicable fees are added according to the loan agreement.
This makes it important to examine:
- Principal
- Interest rate
- Annual percentage rate where applicable
- Fees
- Loan term
- Scheduled payment
- Total repayment amount
The actual cost depends on the terms of the specific loan.
Why Lenders May Not Approve the Requested Amount
A borrower may request one amount but receive approval for another.
Possible reasons can include:
- Income does not support the requested payment under the lender’s criteria
- Existing debt obligations are significant
- Credit history does not meet the lender’s requirements
- The requested amount exceeds the product’s limits
- The lender’s underwriting assessment supports a smaller amount
- The application does not satisfy other eligibility requirements
A lower approved amount does not necessarily mean that the borrower did something wrong. It reflects the lender’s assessment under its particular criteria.
How Loan Terms Affect Borrowing Capacity
Borrowing capacity is not determined by loan amount alone.
The repayment period can affect the scheduled payment and therefore how an application is assessed.
For example, a $12,000 loan over one repayment period will have a different scheduled payment from a $12,000 loan spread over a substantially longer period, assuming other terms are comparable.
However, extending the term can increase the amount of time interest is charged.
Borrowers should therefore consider both monthly affordability and overall borrowing cost.
Personal Loans and Credit Limits Work Differently
Personal loans typically provide a fixed principal amount that is repaid over an agreed period.
Credit cards generally provide revolving access to credit.
This means a borrower might use a credit card, make a payment, regain some available credit and then use the account again.
A personal loan generally follows a different structure: the borrower receives the loan proceeds and makes scheduled payments until the balance is repaid.
For more information about this type of borrowing, see how personal loans work and when to use one.
What Happens When You Make a Loan Payment?
A loan payment may contain several components depending on the loan structure.
Typically, part of the payment goes toward the outstanding principal while another portion covers interest. Applicable fees or other charges can also affect the amount owed.
As the principal declines, the balance remaining on the loan decreases.
The exact allocation can vary depending on the loan agreement and repayment structure.
Why Interest Rates Matter
Interest determines how much borrowing can cost over time.
Two borrowers could receive the same loan amount but pay different total amounts if their interest rates or other loan terms differ.
For example, consider two hypothetical $10,000 loans with the same repayment period but different interest rates. The loan with the higher rate would generally result in more interest being charged, assuming comparable terms and payment schedules.
This is why the approved loan amount should never be considered in isolation.
Can a Borrower Ask for a Higher Credit Limit?
Some credit card issuers allow customers to request a credit-limit increase.
The issuer may evaluate the request using information such as:
- Income
- Existing account history
- Payment behavior
- Current balances
- Credit information
- Other eligibility criteria
Approval is not guaranteed.
A higher limit can provide additional flexibility, but it can also create the potential for larger balances if spending increases.
The usefulness of a higher limit therefore depends on how the additional credit is managed.
Does a Higher Credit Limit Mean You Should Borrow More?
No.
A credit limit describes how much credit a lender is willing to make available. It does not describe how much a borrower can necessarily afford to repay comfortably.
For example, someone with a $15,000 credit limit might decide that carrying a $2,000 balance is already more than they want to manage.
The distinction between available credit and affordable borrowing is important.
A lender’s approval is not a substitute for a personal assessment of whether additional debt fits within a household budget.
How Credit Limits Can Affect Credit Management
Credit limits can influence how borrowers manage revolving balances.
A larger limit can provide more available credit, while a smaller limit can leave less room for spending before the account approaches its maximum.
Borrowers should monitor:
- Current balances
- Available credit
- Payment due dates
- Interest charges
- Fees
- Credit reports
- Account statements
Regular monitoring can help identify problems before they become more difficult to address.
Common Mistakes With Credit Limits and Loan Amounts
New and experienced borrowers can misunderstand how much credit they actually have available or how much borrowing costs.
Common mistakes include:
Treating the Credit Limit as a Budget
A credit card limit is not the same as disposable income.
Focusing Only on the Monthly Payment
A small monthly payment can sometimes result from a long repayment period.
Ignoring Interest
The amount borrowed is only part of the total cost.
Taking the Maximum Amount Available
Being approved for a certain amount does not mean the entire amount needs to be borrowed.
Forgetting Existing Debt
A new payment has to fit alongside existing financial commitments.
Ignoring Fees
Application, annual, late-payment or other fees can increase the cost of borrowing depending on the product.
Missing Payment Dates
Late payments can result in fees and may affect credit records depending on the circumstances and reporting practices.
People who are new to borrowing can learn more about avoiding common problems in How New Credit Users Can Avoid Mistakes.
How to Think About an Affordable Credit Amount
A useful approach is to start with the household budget rather than the lender’s maximum offer.
Consider:
- Regular income
- Essential expenses
- Existing debt payments
- Savings goals
- Emergency expenses
- Potential changes in income
- The new payment
- Interest and fees
The goal is to understand how a new credit obligation fits into the broader financial picture.
A lender’s maximum approval and a borrower’s comfortable borrowing level can be very different numbers.
What to Check Before Accepting Credit
Before accepting a credit card, loan or limit increase, review the terms carefully.
Look at:
- Interest rate
- Annual percentage rate where applicable
- Credit limit or principal
- Minimum payment
- Repayment period
- Fees
- Late-payment terms
- Early repayment provisions
- Variable-rate provisions
- Security or collateral requirements where applicable
- Consequences of missed payments
Understanding the agreement before borrowing can prevent unpleasant surprises later.
Credit Limits Can Change, but Financial Habits Matter More
Credit limits and loan amounts are useful financial concepts, but the numbers alone do not determine whether borrowing is manageable.
A large credit limit can be useful without being fully used. A modest loan can still become expensive if its terms are poorly understood. Likewise, a seemingly affordable monthly payment may need to be considered alongside the total repayment cost.
The most useful habit is to evaluate borrowing based on the complete picture: how much is available, how much is actually needed, what it costs, how repayment works and whether the obligation fits comfortably within the borrower’s financial circumstances.
Understanding these details can turn credit from an abstract number on an account statement into a financial tool that is easier to evaluate and manage.