How Payment History Affects Credit Scores
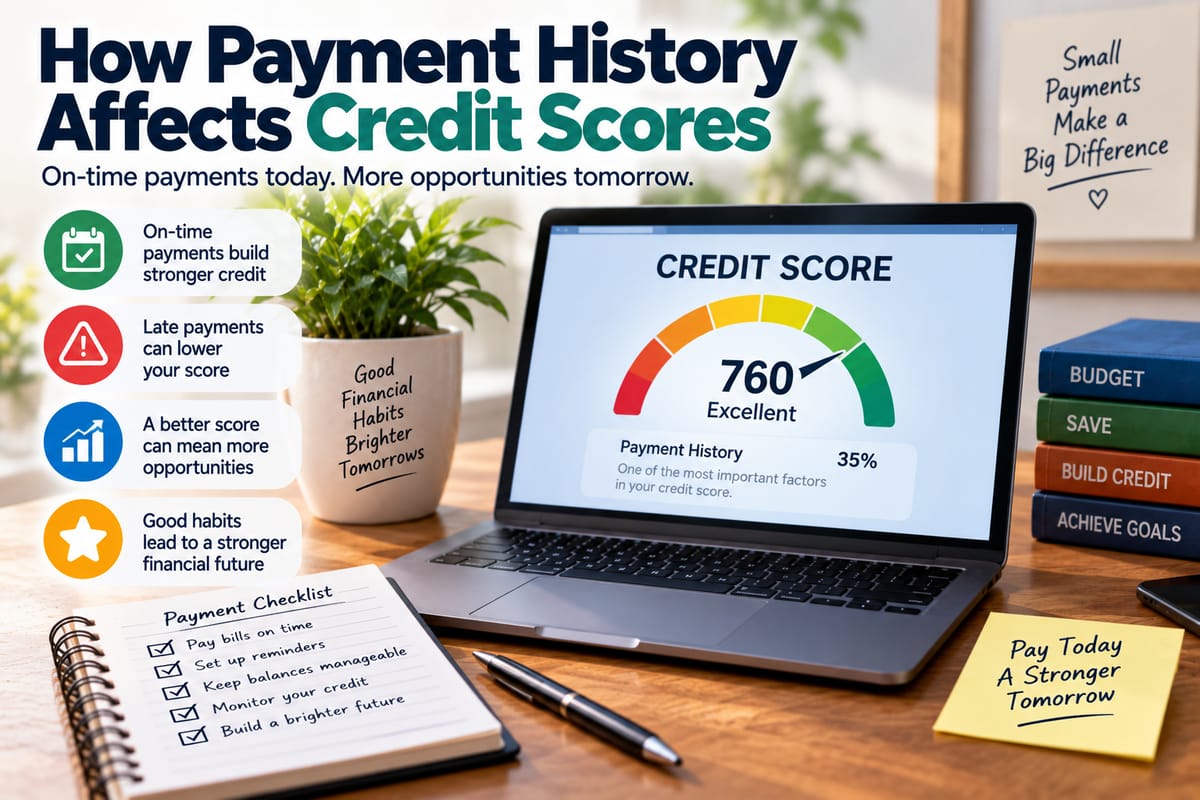
Payment history is one of the most important factors used in many credit-scoring systems. It reflects whether a person has paid their credit obligations as agreed and provides lenders with information about how reliably they have managed borrowed money in the past.
A history of consistently making payments on time can support a healthy credit profile, while missed, late, or seriously delinquent payments can have a negative effect. The impact can vary depending on the scoring model, the type of account, how late a payment is, and other information contained in a person’s credit history.
Understanding payment history is therefore essential for anyone who uses credit cards, loans, mortgages, or other forms of borrowing.
What Is Payment History?
Payment history is a record of how borrowers have handled their scheduled credit payments.
Depending on the type of account and reporting system, a credit report may show whether payments were made on time, whether an account became delinquent, and whether an account eventually went into collections or experienced another serious payment problem.
Credit accounts that may contribute information to payment history include:
- Credit cards
- Personal loans
- Auto loans
- Mortgages
- Student loans
- Retail credit accounts
- Other accounts that report payment information to credit bureaus
Payment history is not simply a record of whether someone has ever missed a payment. It can include the timing and severity of payment problems over the life of an account.
Why Payment History Matters to Credit Scores
Credit scores are designed to estimate credit risk using information from a person’s credit history.
One of the questions a scoring model attempts to answer is relatively straightforward:
Has this borrower generally paid credit obligations as agreed?
A consistent record of timely payments provides evidence of responsible repayment behavior. Conversely, repeated payment problems can indicate greater risk to a lender.
The exact importance assigned to payment history depends on the scoring model. Different scoring systems can use different formulas and may weigh information differently.
For a broader explanation of how scoring works, credit reports, and the information they contain, see this complete guide to credit scores and credit reports.
How On-Time Payments Can Help
Making payments on time helps establish a positive repayment record.
Every successful payment represents another instance of meeting a credit obligation according to its terms. Over time, a consistent pattern can contribute to a stronger credit history.
On-time payments are particularly important because credit scoring models generally evaluate patterns rather than isolated moments.
For example, someone who has consistently paid several credit accounts on time over many years has a different credit history from someone with numerous recent delinquencies.
This does not mean that one late payment will automatically destroy a credit score. Credit scoring considers multiple pieces of information.
What Happens When a Payment Is Late?
A payment being late does not necessarily mean it will immediately appear as a serious delinquency on every credit report.
Credit agreements and reporting practices can differ, and the number of days a payment is overdue can matter.
A borrower may face different consequences depending on whether a payment is:
- A few days late
- Significantly overdue
- Reported as delinquent
- Sent to collections
- Associated with a default or another serious account event
A lender may also charge a late fee before a payment becomes a reported delinquency.
Because reporting rules vary, borrowers should review the terms of their individual accounts rather than assuming that every late payment is treated identically.
Why the Severity of a Late Payment Matters
Credit scoring models can distinguish between different levels of delinquency.
A payment that is only slightly late may be treated differently from an account that remains unpaid for a much longer period.
More serious delinquencies generally provide stronger evidence of repayment problems.
The timing of the delinquency can also matter. A recent serious missed payment may have a different effect from an older payment problem that is no longer recent.
This is one reason credit scores can change over time even when a person has not opened or closed any new accounts.
Repeated Missed Payments Can Create Larger Problems
One isolated payment problem and a pattern of missed payments are not necessarily equivalent.
Repeated delinquencies can suggest that a borrower is having difficulty managing their credit obligations.
A pattern might involve several missed payments across one account or payment problems affecting multiple accounts.
In addition to potential credit-score consequences, repeated missed payments can result in:
- Late fees
- Increased account costs
- Collection activity
- Account restrictions
- Difficulty qualifying for new credit
- Higher borrowing costs in some circumstances
The financial consequences can therefore extend beyond the credit score itself.
How Recent Payment History Can Matter
Credit scoring models may place importance on how recent information is.
A recent payment problem can provide more relevant information about current repayment behavior than an older event.
This is one reason a credit score can gradually recover after a period of financial difficulty when a person establishes a consistent record of on-time payments.
Recovery is not necessarily immediate, however.
Older negative information may continue to appear on credit reports for a period determined by applicable reporting rules, and different scoring models can treat historical information differently.
Does One Missed Payment Ruin a Credit Score?
There is no universal answer because credit scores depend on the scoring model and the borrower’s overall credit profile.
The effect of a payment problem can depend on factors such as:
- How late the payment was
- Whether it was reported
- How recently it occurred
- Whether there are other missed payments
- The person’s existing credit history
- The type of account involved
- Other information considered by the scoring model
Someone with an otherwise strong and established credit history may have a different outcome from someone who already has several recent delinquencies.
The important point is that a single payment problem should not automatically be interpreted as a permanent assessment of someone’s creditworthiness.
Payment History and Credit Age
Payment history also interacts with the broader history of a person’s credit accounts.
A long history of successfully managed accounts can provide more information about repayment behavior than a very limited credit history.
This does not mean people should keep unnecessary accounts open solely to preserve credit history. Instead, it highlights why consistently managing existing accounts can be valuable over time.
People who are just beginning to use credit can focus on establishing sustainable habits rather than trying to build a large credit profile quickly.
Those starting with little or no credit history can learn more from this guide on how to build credit from scratch.
Payment History Is Different From Credit Utilization
Payment history and credit utilization are separate aspects of credit scoring.
Payment history concerns whether required payments have been made as agreed.
Credit utilization generally refers to how much revolving credit is being used relative to available credit limits.
For example, someone could make every credit card payment on time while using a large percentage of their available credit. Another person could have low balances but a history of missed payments.
These situations can affect a credit profile in different ways.
This distinction is important because paying on time is essential, but it is not the only factor that credit-scoring systems may consider.
Payment History and Credit Card Balances
Credit card users should understand the difference between making a payment and paying a balance in full.
Making at least the required payment by the due date generally prevents the account from becoming delinquent under the terms of the account.
Paying the full statement balance can have additional financial benefits because it may help avoid interest charges, depending on the card’s terms.
These are separate concepts:
- Minimum payment: The minimum amount required to keep the account from becoming delinquent under its terms.
- Statement balance: The amount shown on the statement for the billing period.
- Current balance: What is owed on the account at a particular point in time.
- Payment due date: The date by which the required payment must be made.
Understanding these differences can help borrowers avoid unnecessary interest and payment problems.
Automatic Payments Can Help Prevent Missed Due Dates
Automatic payments can be useful for people who sometimes forget payment deadlines.
A borrower may be able to arrange for at least the required payment to be automatically withdrawn from a bank account.
However, automatic payments should not be treated as something that can simply be set up and forgotten.
People should still check their accounts to make sure:
- There is enough money available for the payment.
- The payment information remains accurate.
- The account is active.
- The payment was processed successfully.
- The amount being withdrawn is appropriate.
A failed automatic payment can still create problems if it causes an account to become overdue.
Calendar Reminders Can Also Help
People who prefer to make payments manually can use calendars, phone reminders, banking alerts, or budgeting systems to track due dates.
A simple routine can reduce the chance of overlooking an important deadline.
For people managing several accounts, a payment calendar can list:
| Account | Payment Due | Amount | Payment Status |
|---|---|---|---|
| Credit Card | 5th | Minimum due | Scheduled |
| Personal Loan | 12th | Required payment | Paid |
| Auto Loan | 18th | Required payment | Scheduled |
| Store Card | 25th | Minimum due | Paid |
The specific dates and amounts will vary by borrower, but the principle is the same: make payment obligations visible and easy to monitor.
How Credit Reports Help Track Payment History
Credit reports provide a record of information supplied by participating creditors and other reporting organizations.
Reviewing a credit report can help a person identify potential problems, such as:
- Incorrectly reported late payments
- Accounts they do not recognize
- Incorrect balances
- Duplicate information
- Outdated information
- Accounts that should have been closed
Regularly checking credit information can therefore be useful for identifying discrepancies.
Credit monitoring services can also provide alerts or summaries. A broader explanation of this process is available in how credit monitoring tools track credit health.
What If a Payment Is Reported Incorrectly?
Credit reports can contain errors.
If someone believes a payment was incorrectly reported as late or delinquent, they can review the information and follow the applicable dispute process with the relevant credit bureau and creditor.
Useful records may include:
- Bank statements
- Payment confirmations
- Account statements
- Emails
- Receipts
- Transaction records
Keeping payment documentation can make it easier to investigate a disagreement about when or whether a payment was made.
How Payment History Can Affect Borrowing
Credit scores are one factor that lenders may consider when evaluating applications.
A borrower’s credit history can influence how a lender evaluates an application for products such as:
- Credit cards
- Personal loans
- Auto financing
- Mortgages
- Other forms of credit
Lenders may also consider income, existing debts, employment information, collateral, loan terms, and their own underwriting criteria.
A strong payment history does not guarantee approval, just as a weaker payment history does not necessarily mean an application will always be rejected.
The overall credit profile and the lender’s requirements matter.
Payment History and Interest Costs
Credit history can sometimes influence the terms offered by a lender, although practices differ between lenders and products.
When a lender views a borrower as presenting greater credit risk, the lender may price that risk into the terms of credit.
This can potentially mean higher borrowing costs.
Over a long loan period, even a relatively small difference in interest rates can translate into a substantial difference in total interest paid.
This is one reason maintaining a healthy credit history can matter beyond the numerical credit score itself.
What New Credit Users Should Watch For
People new to credit may accidentally create payment problems simply because they are unfamiliar with how credit accounts operate.
Common mistakes can include:
- Forgetting the first payment due date
- Assuming a payment is automatic when it is not
- Paying after the deadline
- Confusing the statement date with the due date
- Using a credit card without planning for repayment
- Ignoring account notifications
- Opening more accounts than they can comfortably manage
Practical habits can make these problems easier to avoid. More guidance is available in how new credit users can avoid mistakes.
What to Do After a Missed Payment
A missed payment does not mean someone should ignore the account.
Taking action quickly can help prevent the situation from becoming more serious.
A borrower can:
- Check the account to determine what is overdue.
- Make the required payment if possible.
- Review whether additional fees have been charged.
- Contact the lender if there is a problem or unusual circumstance.
- Confirm when the payment has been processed.
- Set up reminders or automatic payments if appropriate.
- Review the credit report later to ensure the information is accurate.
If financial difficulties make repayment impossible, contacting creditors early may provide more options than waiting until the account becomes severely delinquent.
Building a Strong Payment History Over Time
A positive payment history generally comes from consistency rather than a single action.
A practical system can be simple:
Know the due dates → Budget for payments → Pay on time → Monitor accounts → Review credit reports → Address problems quickly
This routine can help prevent avoidable mistakes.
It is also important to borrow within a person’s financial capacity. A perfect record becomes difficult to maintain if monthly credit obligations are consistently unaffordable.
Payment History Is One Piece of the Bigger Credit Picture
Payment history is important, but it is not the entire credit profile.
Credit-scoring systems may consider other factors, including credit utilization, length of credit history, types of credit accounts, new credit activity, and other information depending on the model.
Two people with identical payment histories can therefore have different credit scores because the rest of their credit profiles differ.
This is why improving credit generally involves looking at the entire financial picture rather than focusing on a single number.
Consistency Is the Key to Healthy Credit Habits
Payment history provides a long-term record of how a person handles credit obligations. Making payments on time can help establish a positive history, while repeated or serious delinquencies can create problems that may affect credit profiles and borrowing opportunities.
The most effective approach is usually straightforward: understand payment due dates, borrow within manageable limits, monitor accounts, review credit reports, and respond quickly when something goes wrong.
Credit scores can change over time, but the habits behind them are built one payment at a time.