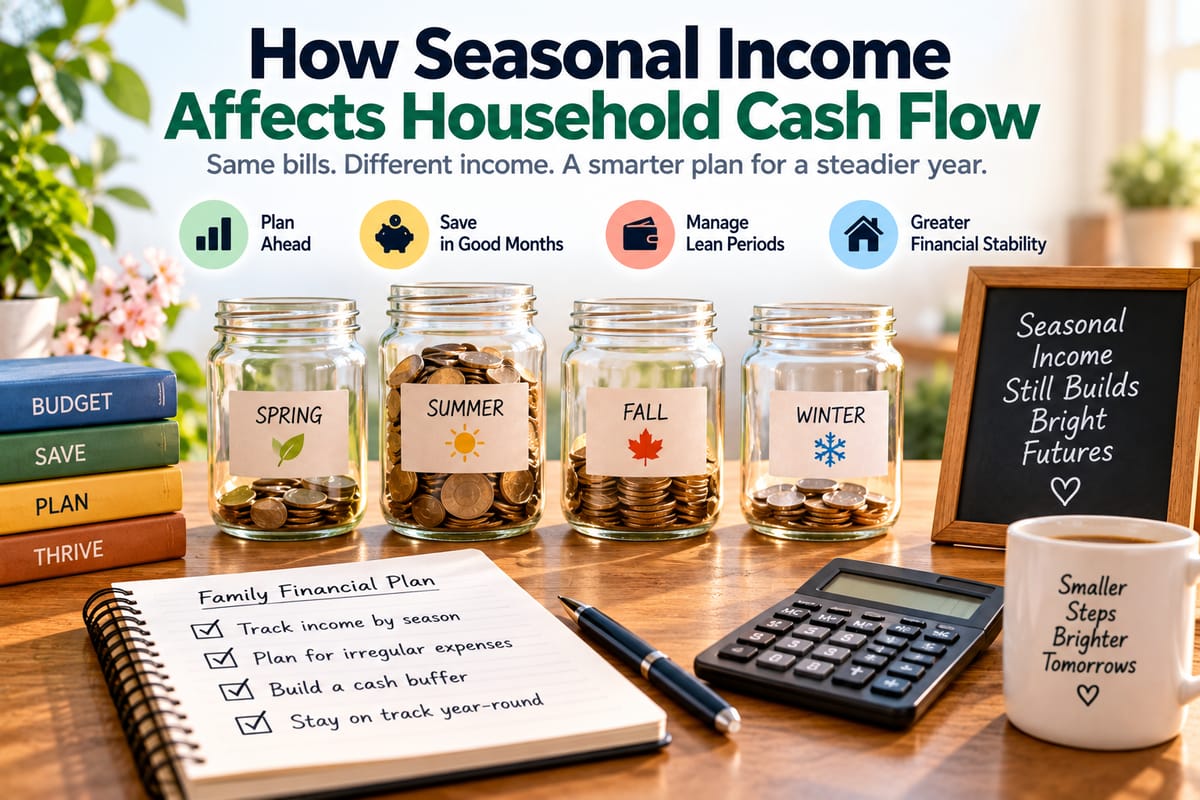
How Seasonal Income Affects Household Cash Flow
Household finances can become difficult to manage when income changes significantly from one part of the year to another. A family may earn substantially more during certain months and considerably less during others, creating a pattern that looks very different from the steady monthly paycheck many traditional budgeting methods assume.
This is known as seasonal income.
Seasonal income can affect households in many ways. A family might have strong cash flow during a busy work season but struggle to cover ordinary expenses during slower months. Another household might receive annual bonuses, commission payments, agricultural income, contract earnings, or business revenue at irregular times.
The challenge is not necessarily that the household earns too little over the entire year. Instead, the problem can be when the money arrives compared with when bills and other expenses are due.
Understanding this timing difference can make it easier for families to plan ahead, build reserves, adjust spending, and avoid treating a high-income month as though it represents normal income for the entire year.
What Is Seasonal Income?
Seasonal income is money that changes according to predictable or recurring periods during the year.
It can affect employees, self-employed workers, business owners, contractors, farmers, freelancers, and households with multiple income sources.
Examples include:
- Tourism workers earning more during peak travel periods
- Agricultural households receiving income after harvests
- Retail workers earning more during busy shopping periods
- Construction workers experiencing seasonal changes in available work
- Freelancers receiving more contracts during certain months
- Teachers or temporary workers with income that follows specific schedules
- Business owners experiencing predictable seasonal sales
- Workers receiving annual bonuses or commissions
- Households with temporary or contract employment
The defining feature is that income does not arrive evenly throughout the year.
A household could therefore have an adequate annual income while still experiencing periods of tight cash flow.
Income and Cash Flow Are Not the Same
One of the most important concepts for households with seasonal earnings is the difference between annual income and cash flow.
Annual income measures how much money a household receives over a longer period.
Cash flow looks at when money enters and leaves the household.
Imagine a household earns $60,000 over a year.
At first glance, that might appear equivalent to earning $5,000 every month.
But suppose the actual pattern looks like this:
| Period | Income |
|---|---|
| January | $2,000 |
| February | $2,000 |
| March | $2,500 |
| April | $3,000 |
| May | $4,000 |
| June | $7,000 |
| July | $8,000 |
| August | $9,000 |
| September | $8,000 |
| October | $6,000 |
| November | $5,000 |
| December | $3,500 |
The household’s annual income might be sufficient to cover its expenses, but the lower-income months can still create problems if bills remain relatively consistent.
This is why seasonal households need to manage timing, not just totals.
Why Seasonal Income Creates Cash Flow Pressure
Many household expenses do not change as dramatically as income.
Rent or mortgage payments may remain the same each month.
Utilities, insurance, transportation, food, school expenses, subscriptions, and debt payments can also continue regardless of whether income is high or low.
This creates a mismatch.
During high-income periods, a household may have significantly more money available than it needs for immediate expenses.
During low-income periods, the opposite can happen.
Without planning, families may spend heavily during strong months and then rely on credit or emergency savings during weaker months.
This can create a cycle in which the household feels financially comfortable for part of the year and financially stressed for another part.
The Importance of Looking at the Entire Year
A household with seasonal income should generally avoid building its financial plan around its best month.
Instead, it can be helpful to examine the entire year.
Start by identifying:
- Expected income by month
- Essential expenses
- Variable household spending
- Annual and irregular expenses
- Debt payments
- Savings contributions
- Expected high-income periods
- Expected low-income periods
A calendar or spreadsheet can make the pattern much easier to see.
The goal is to understand when the household is likely to have excess cash and when it may need to draw from money saved during stronger periods.
Building a Budget Around Seasonal Income
Traditional monthly budgeting can be difficult when income changes throughout the year.
A seasonal household may benefit from using a year-round budget that still tracks monthly cash flow.
The how to build a family budget approach can provide a useful foundation for organizing household income and expenses.
The key adjustment is to recognize that income may not be evenly distributed.
Instead of asking only:
How much can we spend this month?
the household can also ask:
How much do we need to set aside during stronger months to support the rest of the year?
This shifts the focus from short-term spending capacity to overall financial stability.
Creating a Monthly Income Forecast
A simple income forecast can help a household anticipate changes.
For each month, estimate:
- Expected income
- Essential expenses
- Flexible expenses
- Planned savings
- Irregular expenses
- Expected surplus or shortfall
For example:
| Month | Expected Income | Essential Expenses | Estimated Surplus/Shortfall |
|---|---|---|---|
| January | $2,500 | $3,000 | -$500 |
| February | $2,700 | $3,000 | -$300 |
| March | $3,200 | $3,000 | +$200 |
| April | $4,500 | $3,000 | +$1,500 |
| May | $6,000 | $3,000 | +$3,000 |
This type of forecast makes the seasonal pattern visible.
The household can then plan to use some of the April and May surplus to cover anticipated shortfalls in January and February.
Building a Cash Flow Buffer
A cash flow buffer can be particularly valuable for seasonal households.
Instead of allowing all surplus income from strong months to disappear into discretionary spending, a family can reserve some of it for future lower-income periods.
This money can function as a bridge between high-income and low-income seasons.
For example, if a household knows that income usually falls substantially for three months each year, it can gradually build a dedicated cash reserve before that period begins.
The amount required depends on the household’s expenses, income pattern, savings, and level of uncertainty.
The broader principles in how to manage uneven household cash flow are especially relevant to families whose income does not arrive at a consistent monthly rate.
Separate Regular Expenses From Seasonal Expenses
Not every expense needs to be treated the same way.
A household can divide expenses into categories such as:
Fixed Expenses
These are expenses that are relatively predictable.
Examples include:
- Rent or mortgage
- Insurance
- Loan payments
- Certain subscriptions
- School-related commitments
Variable Expenses
These can change from month to month.
Examples include:
- Groceries
- Transportation
- Utilities
- Entertainment
- Household purchases
Irregular Expenses
These occur periodically rather than every month.
Examples include:
- Car repairs
- School fees
- Property maintenance
- Annual insurance payments
- Holiday spending
- Medical expenses
- Appliance replacement
Separating these categories helps families understand which costs must be funded consistently and which can be planned for in advance.
Planning for Irregular Expenses
Seasonal income and irregular expenses can create a particularly challenging combination.
A household may have low income at the same time that an annual or unexpected expense arrives.
One solution is to set aside money gradually during higher-income periods.
The principles discussed in how families can budget for irregular expenses can help families prepare for costs that do not fit neatly into a monthly budget.
For example, instead of waiting until an annual insurance payment is due, a household could reserve part of the expected cost during earlier months.
This turns a large future payment into a series of smaller planned allocations.
Use High-Income Months Strategically
A high-income month can create a sense of financial abundance.
That can make it tempting to increase spending immediately.
However, seasonal households may need to treat unusually strong income differently from regular income.
A surplus can potentially be divided among several priorities:
- Future household expenses
- Emergency savings
- Seasonal cash reserves
- Debt repayment
- Long-term savings
- Planned purchases
- Retirement or investment goals
- Reasonable discretionary spending
The exact allocation depends on the family’s circumstances.
The important principle is to avoid assuming that every dollar earned during a peak period represents money available for immediate consumption.
Avoid Lifestyle Inflation During Peak Seasons
Lifestyle inflation occurs when spending rises as income rises.
For households with seasonal income, this can be particularly risky.
A family might experience several months of strong earnings and begin spending as though those earnings will continue throughout the year.
When the slow season arrives, the household may discover that its regular expenses have increased while income has fallen.
A more sustainable approach is to distinguish between:
Temporary income increase and permanent increase in earning capacity.
If a strong income period is temporary, spending decisions should account for what happens when that period ends.
Create a Minimum Monthly Spending Target
Seasonal households can benefit from identifying the minimum amount needed to cover essential living expenses.
This can include:
- Housing
- Food
- Utilities
- Transportation
- Insurance
- Minimum debt payments
- Essential healthcare
- Necessary household costs
Once the household knows this baseline, it becomes easier to calculate how much needs to be reserved during high-income periods.
For example, if essential expenses are $3,000 per month and the household expects income of only $2,000 during certain months, it knows that the difference must come from another source.
That source might be savings, a cash-flow reserve, additional work, or another reliable household income stream.
Create a Seasonal Savings Target
Instead of saving an arbitrary amount each month, families with seasonal income can create savings targets based on their expected annual pattern.
Suppose a household expects three low-income months.
If each month is expected to produce a $1,000 shortfall, the family could establish a target of at least $3,000 for those expected gaps, while considering an additional cushion for uncertainty.
The calculation could look like:
Expected seasonal shortfall × number of low-income months = minimum seasonal reserve
This is only a planning framework. Actual needs can be higher because income estimates and expenses may change.
Keep Emergency Savings Separate
A seasonal cash-flow reserve and an emergency fund do not necessarily serve the same purpose.
A seasonal reserve is designed for a predictable income pattern.
An emergency fund is designed for unexpected problems.
For example:
Seasonal reserve: Income is expected to decline every January and February.
Emergency fund: A major car repair occurs unexpectedly.
Keeping these purposes separate can make it easier to determine whether money should be used for a known seasonal shortfall or preserved for an unexpected emergency.
Automate Savings During Strong Months
Automation can make seasonal saving easier.
When a high-income payment arrives, a household could automatically transfer a predetermined portion into a separate savings account.
This reduces the temptation to spend the entire surplus.
For example, a family might decide that a portion of every unusually large payment goes toward:
- Seasonal reserves
- Emergency savings
- Annual expenses
- Long-term goals
The exact percentages depend on income stability and household priorities.
Use Separate Accounts for Different Purposes
Some households find it easier to organize seasonal finances by separating money into different accounts or clearly defined savings categories.
Possible categories include:
- Monthly spending
- Seasonal income reserve
- Emergency savings
- Annual bills
- Long-term savings
- Planned purchases
This can make the purpose of each dollar more visible.
It also reduces the risk of confusing money that is reserved for future expenses with money that is available for discretionary spending.
Be Careful With Credit During Low-Income Months
Credit can temporarily bridge a cash-flow gap, but repeatedly using credit to cover predictable seasonal shortfalls can create a longer-term problem.
Suppose a household consistently experiences lower income for three months each year.
If it borrows money every year to cover those months and then repays the debt during the high-income season, interest costs can gradually consume part of the household’s income.
Where possible, building a reserve ahead of the slow season can reduce dependence on borrowing.
Credit may still have a role in certain circumstances, but predictable seasonal expenses are generally easier to manage when anticipated in advance.
Coordinate Household Income Sources
Some families have more than one income source.
For example, one partner may receive a regular paycheck while another earns seasonal or contract income.
This can create an opportunity to structure household cash flow more deliberately.
The regular income can potentially cover predictable monthly expenses, while seasonal earnings can be allocated toward:
- Savings
- Annual expenses
- Debt reduction
- Large purchases
- Future low-income periods
The appropriate arrangement depends on the household’s financial situation and goals.
Review Income Patterns From Previous Years
Historical information can make seasonal planning more realistic.
If possible, review several years of income and identify:
- High-income months
- Low-income months
- Average income by season
- Unusually strong periods
- Unusually weak periods
- Recurring expenses
- Major unexpected expenses
Past patterns cannot guarantee future results, but they can provide a useful starting point for forecasting.
This is particularly helpful for self-employed households and small business owners whose income can fluctuate considerably.
Build Flexibility Into the Budget
A seasonal budget should not be so rigid that it becomes unusable.
Income forecasts can be wrong.
A busy season may be weaker than expected. A slow period may last longer than usual. An unexpected expense may appear.
For this reason, households can include some flexibility in their plans.
A budget can have:
- Essential spending
- Flexible spending
- Savings targets
- Seasonal reserves
- Emergency reserves
When income falls below expectations, flexible spending can potentially be reduced without immediately affecting essential needs.
Create Simple Household Money Routines
Seasonal budgeting works better when the household reviews its finances regularly.
Families can establish simple routines for:
- Checking account balances
- Reviewing upcoming bills
- Updating income estimates
- Tracking spending
- Moving money into savings
- Preparing for upcoming low-income periods
The how families can create simple routines for managing bills, spending and savings approach can help turn financial planning into a regular household habit rather than something that happens only when money becomes tight.
Plan Before the Slow Season Begins
One of the most common mistakes with seasonal income is waiting until income falls before making adjustments.
By that point, the household may already be under pressure.
A better approach is to prepare before the transition.
Several weeks or months before the expected slow period, the family can:
- Review expected income.
- Calculate essential expenses.
- Check the seasonal reserve.
- Pay attention to upcoming irregular bills.
- Reduce unnecessary commitments if needed.
- Review debt payments.
- Confirm emergency savings.
- Adjust discretionary spending.
Early preparation gives the household more choices.
What If the Seasonal Pattern Changes?
Seasonal patterns are not always perfectly predictable.
A business can experience a weaker peak season. A contract may end earlier than expected. Weather can affect agricultural income. Consumer demand can change.
This is why households should avoid assuming that last year’s income pattern will repeat exactly.
Instead, use previous years as a reference while maintaining a margin for uncertainty.
A stronger reserve can provide additional protection when actual income differs from forecasts.
How Families Can Reduce Seasonal Stress
Financial stress often increases when a household does not know whether it can cover upcoming expenses.
A clear seasonal cash-flow plan can reduce some of that uncertainty.
Families can improve visibility by maintaining:
- A monthly income forecast
- A list of fixed expenses
- A calendar of irregular bills
- A seasonal savings target
- An emergency fund
- Regular household financial check-ins
The goal is not to predict every dollar perfectly.
The goal is to know what is likely to happen and have a plan for reasonable variations.
A Simple Example of Seasonal Cash Flow Planning
Consider a household whose income is highest from June through September.
During those four months, the family receives significantly more money than it needs for immediate monthly expenses.
Instead of spending the entire surplus, the household could establish a seasonal plan.
During Peak Months
The family could:
- Cover normal monthly expenses
- Build the seasonal reserve
- Fund upcoming annual bills
- Add to emergency savings
- Pay down expensive debt where appropriate
- Allocate a reasonable amount toward discretionary spending
During Low-Income Months
The household could:
- Draw from the seasonal reserve
- Maintain essential spending
- Reduce discretionary purchases
- Avoid unnecessary new debt
- Continue monitoring upcoming expenses
When the next high-income period begins, the reserve can be rebuilt.
This creates a cycle that matches the household’s financial reality rather than forcing an uneven income stream into an artificially even monthly model.
Seasonal Income and Long-Term Financial Goals
Seasonal income does not necessarily prevent a household from pursuing long-term financial goals.
In some cases, strong earning periods can provide substantial opportunities to save.
The challenge is maintaining consistency when income fluctuates.
A family might use high-income periods to make larger contributions toward:
- Emergency savings
- Retirement
- Education
- Home purchases
- Debt repayment
- Business investment
- Other long-term goals
The key is to balance these goals with the need to maintain sufficient cash for the next low-income period.
Why Cash Flow Planning Matters More Than a Single Monthly Number
A monthly income figure can hide important information.
A household earning $4,000 every month and another earning $2,000 for six months followed by $6,000 for six months could have the same annual income.
Yet their cash-flow challenges would be very different.
The first household has relatively predictable monthly resources.
The second needs to transfer resources from strong months into weaker months.
That is why seasonal households benefit from looking beyond the monthly snapshot and considering the entire annual cycle.
Turning Seasonal Earnings Into Greater Financial Stability
Seasonal income does not automatically mean unstable finances. The bigger challenge is matching the timing of income with the timing of expenses.
A household can make that process easier by forecasting income across the year, identifying predictable low-income periods, building reserves during stronger months, planning for irregular expenses, and maintaining regular financial routines.
The central idea is simple:
High-income months need to help support low-income months.
When families treat seasonal earnings as part of an annual financial cycle rather than as a series of unrelated monthly windfalls, they can make better use of strong periods and prepare more effectively for slower ones.
A well-planned seasonal budget can turn an uneven income pattern into a more predictable household cash-flow system—one that gives the family a clearer view of its money throughout the entire year.