Consumer Confidence Falls: What It Could Mean for Household Spending and Saving
Understanding what a decline in consumer confidence means can therefore help households make more deliberate financial decisions rather than reacting to economic headlines.
How Estate Planning Can Affect Inheritance and Taxes
Understanding the connection between estate planning, inheritance and taxes can help families prepare more deliberately and reduce avoidable problems.
How Iran-Related Oil Risks Could Affect Energy Stocks and Investors
For investors, the important question is therefore not simply whether Iran will push oil prices higher. It is **how long supply risks persist, how much crude is actually removed from the market, and how energy companies and the wider economy respond.**
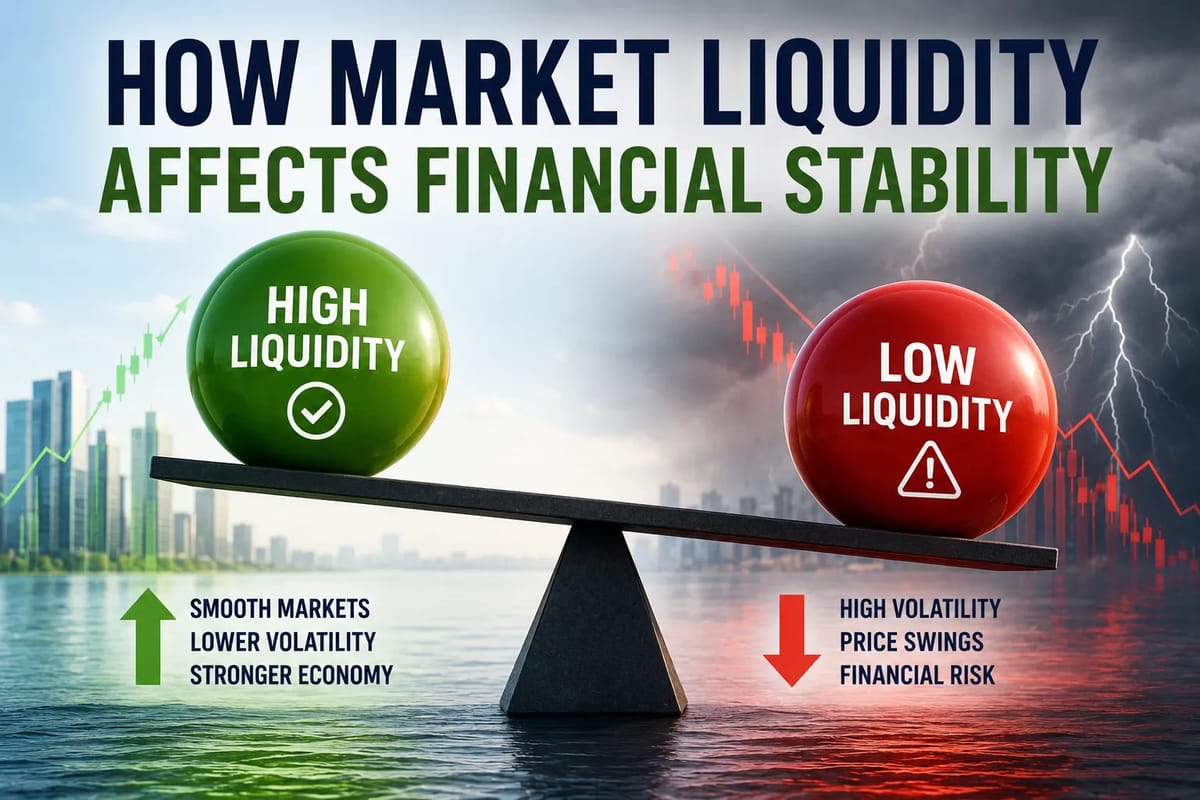
How Market Liquidity Affects Financial Stability
Understanding how liquidity works helps explain why financial markets can sometimes move rapidly during periods of economic or financial stress.
How Personal Loans Work and When to Use One
Understanding how personal loans work, what they cost and when borrowing makes financial sense can help consumers make more informed decisions.
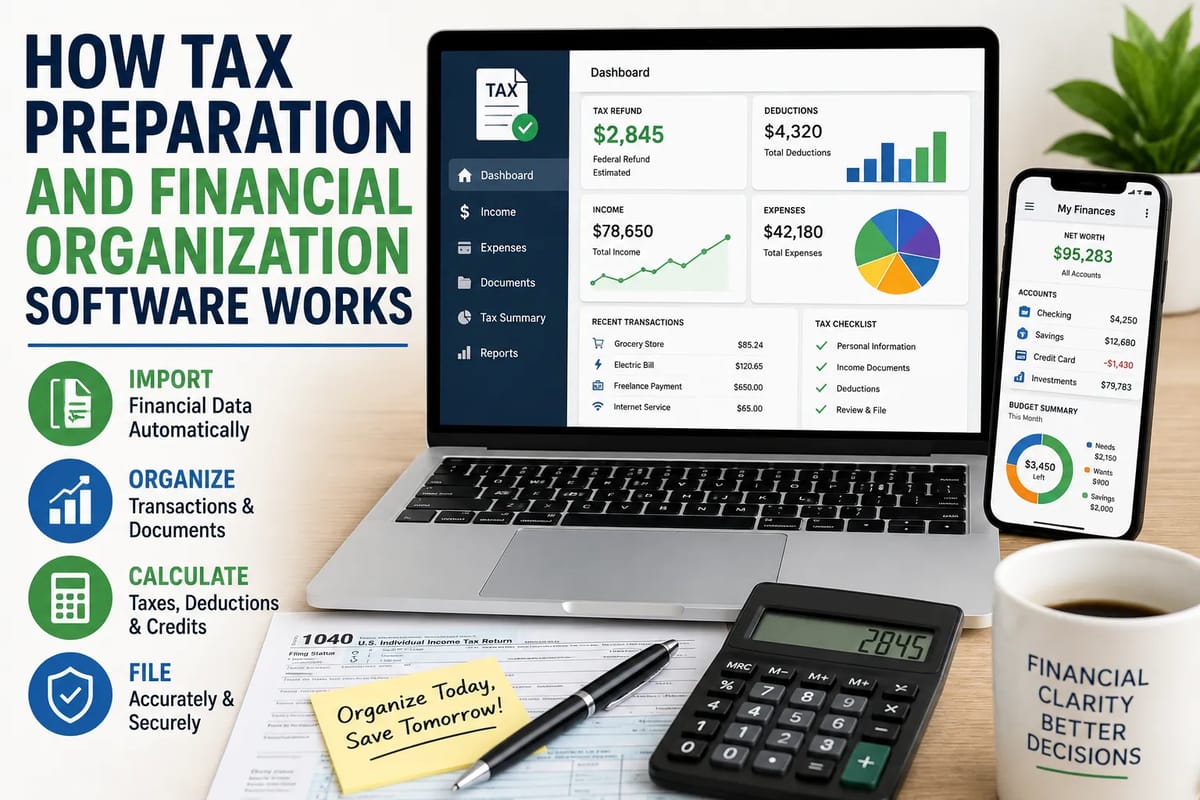
How Tax Preparation and Financial Organization Software Works
These tools can help users organize financial records, categorize transactions, estimate tax obligations, prepare returns and identify information that may be relevant to deductions or credits. They can also reduce the amount of manual data entry involved in routine financial tasks.
How to Build Scalable Income Over Time
For people looking to increase their earning potential over the long term, understanding how scalability works can be more valuable than chasing the latest side-hustle trend.
How to Manage Household Debt and Pay Off Multiple Debts
The good news is that multiple debts do not have to be tackled all at once. A clear system can help a household understand what it owes, prioritize the most expensive balances and gradually reduce the amount of money going toward debt.
Popular Posts