Consumer Confidence Report Could Show Whether Americans Are Cutting Their Budgets
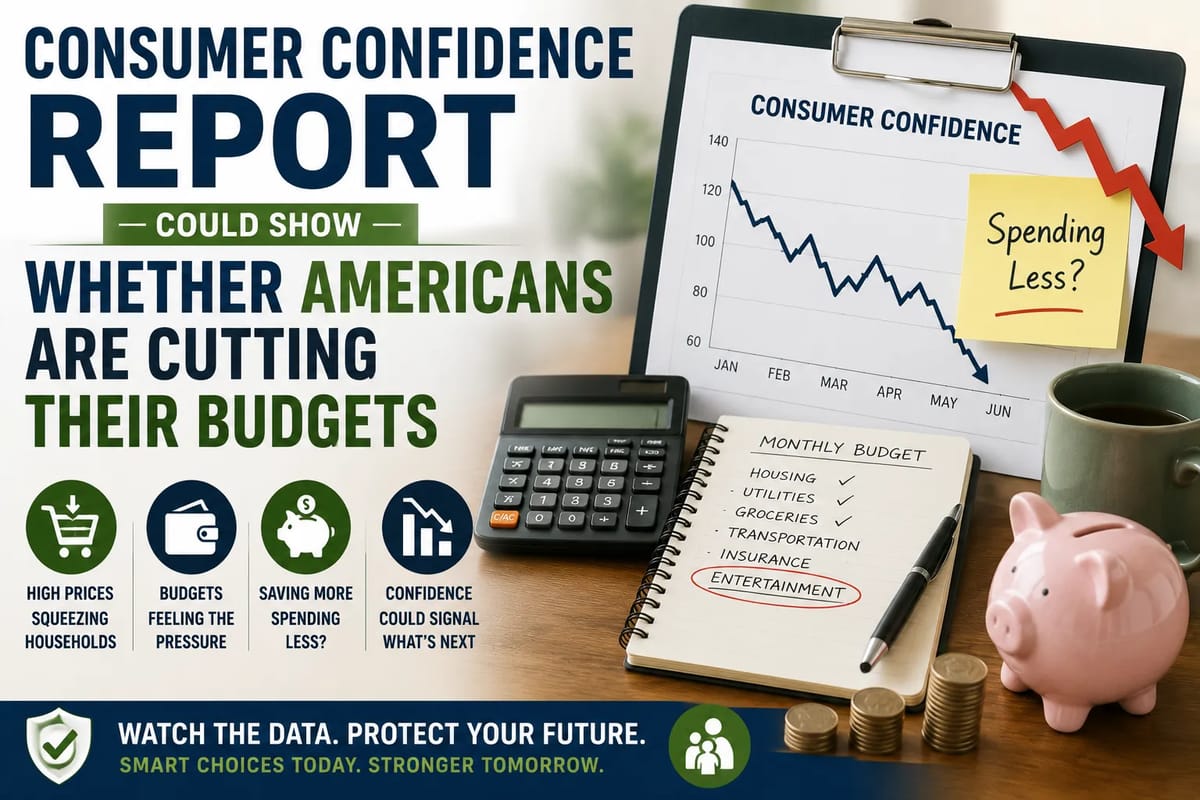
Consumer confidence surveys do not directly measure how much people spend. Instead, they capture attitudes about current economic conditions and expectations for the months ahead. Those expectations can influence decisions about major purchases, saving, borrowing and discretionary spending.
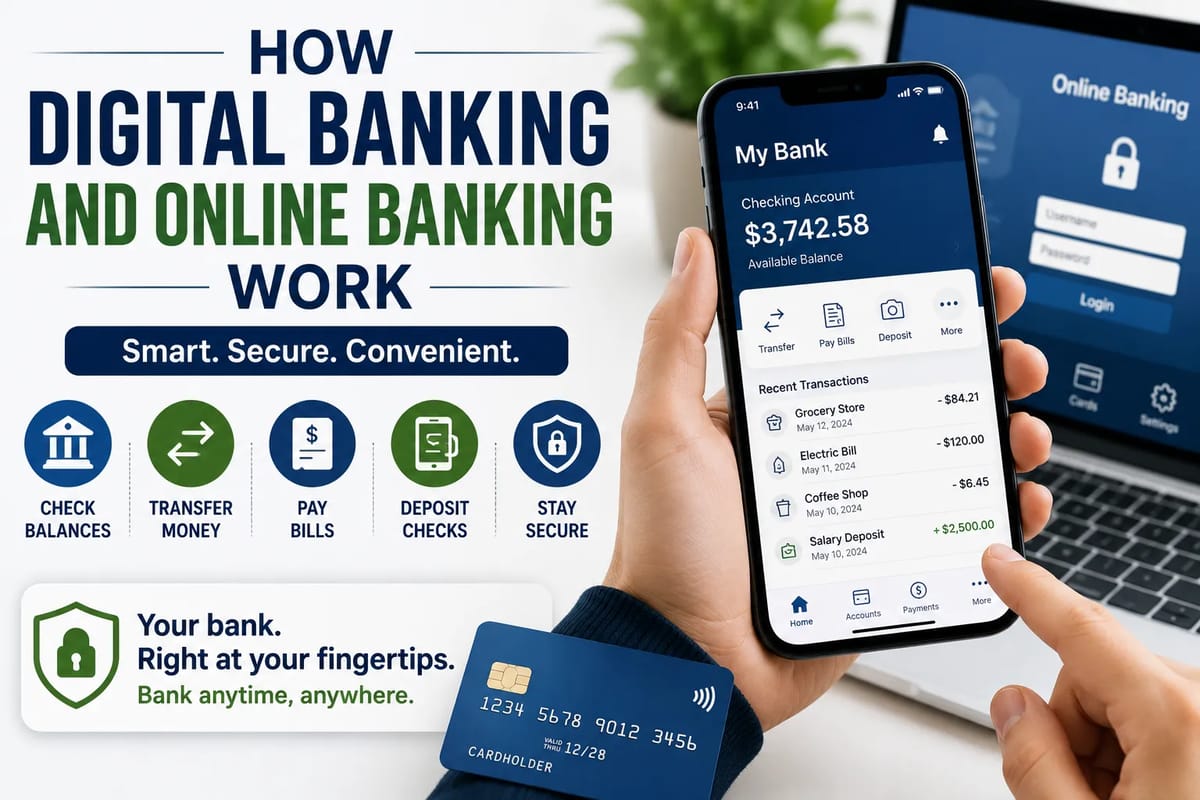
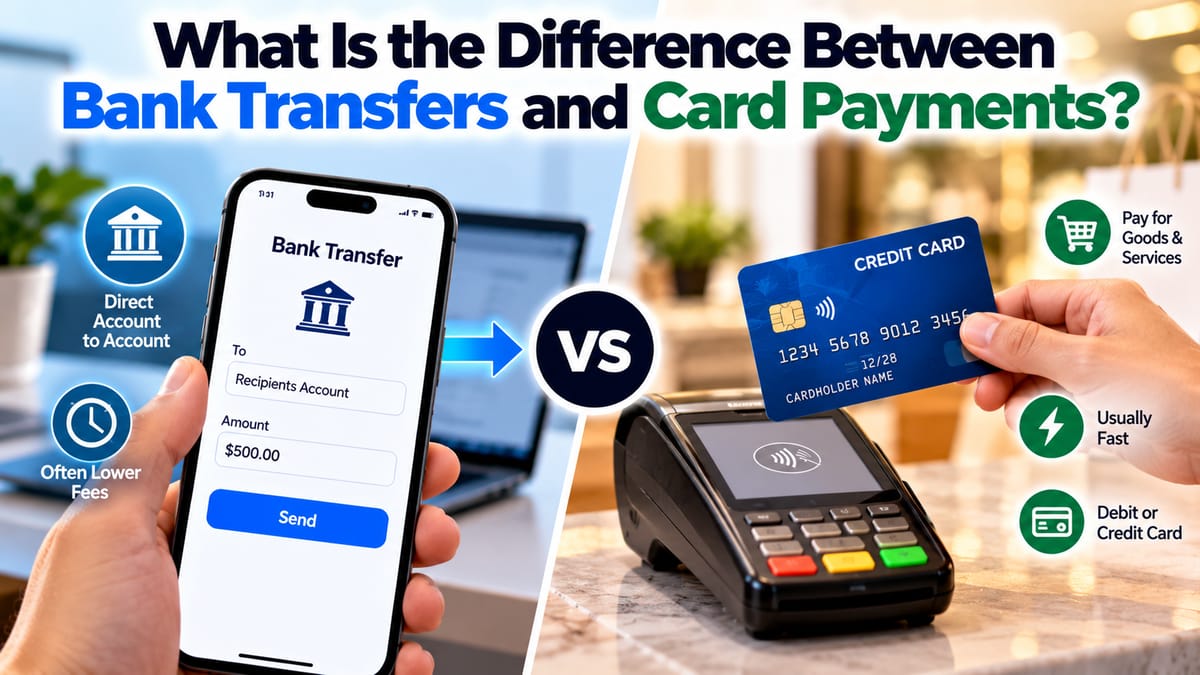
How Digital Banking and Online Banking Work
Understanding how these systems work can help consumers use them more effectively while recognizing the security risks that come with managing money online.
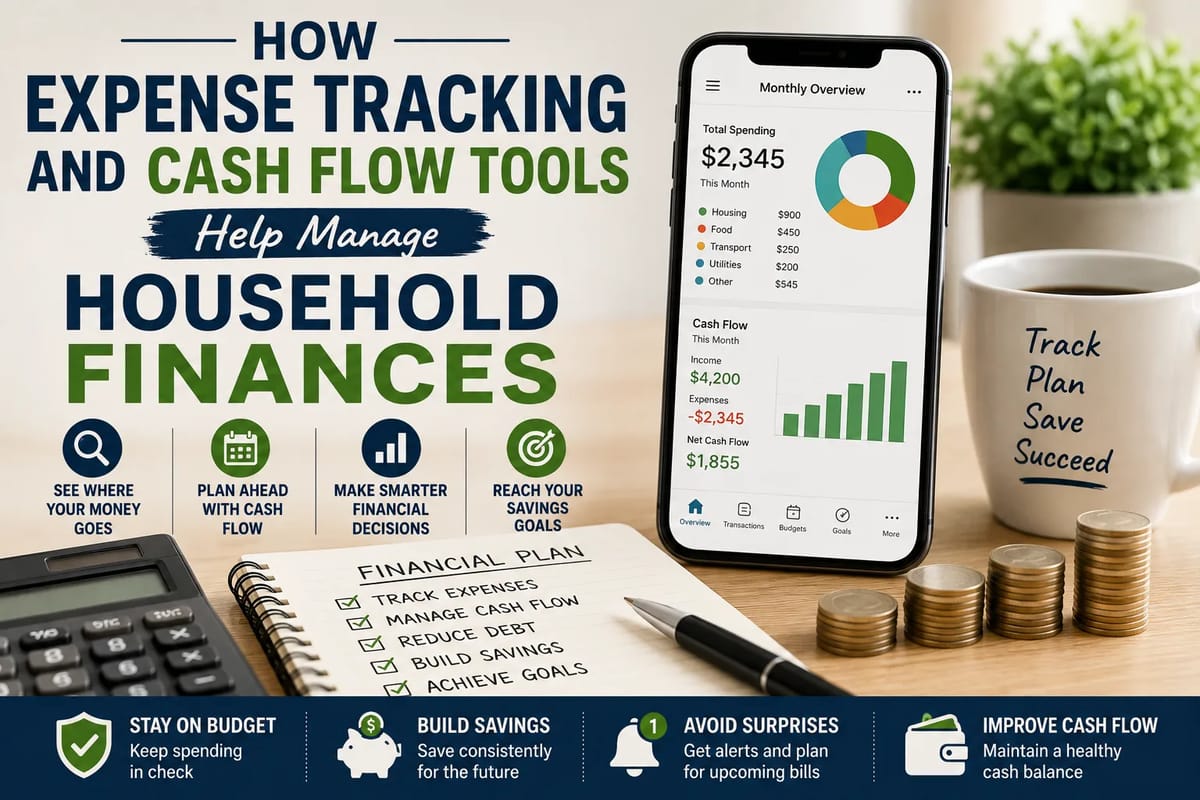
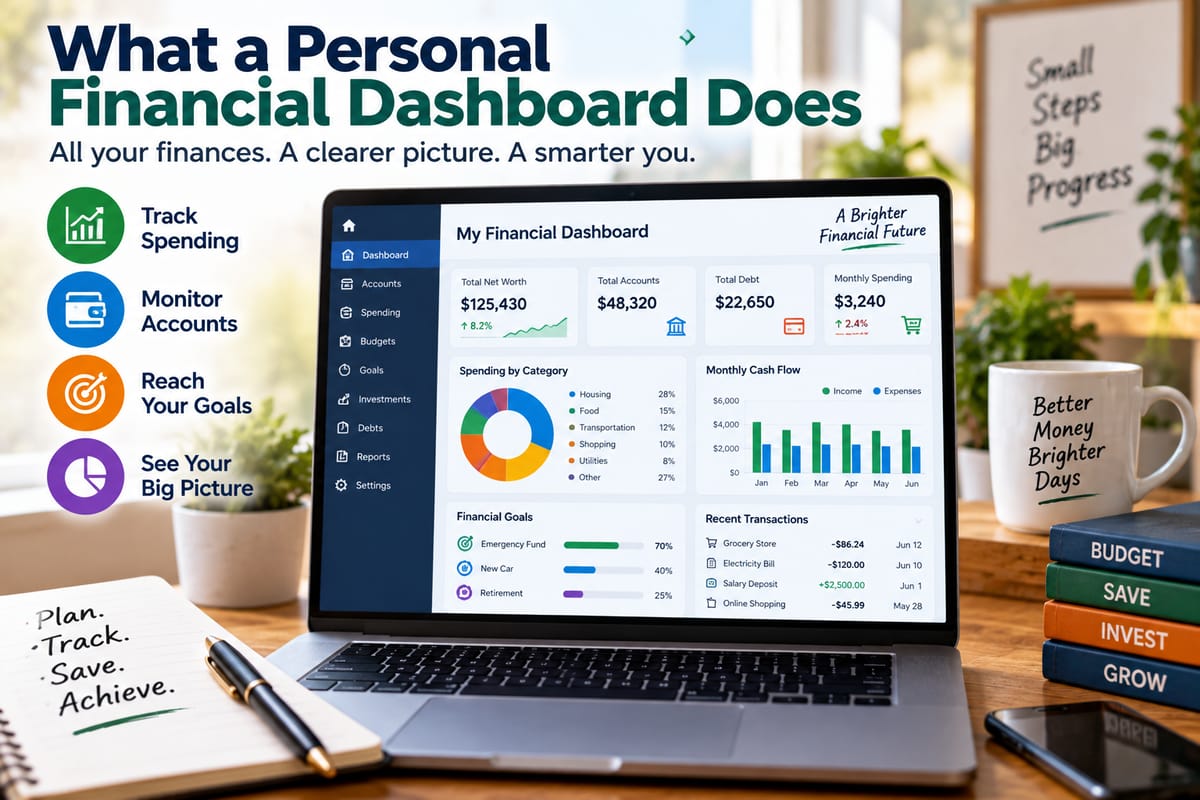
How Expense Tracking and Cash Flow Tools Help Manage Household Finances
Whether it is a simple spreadsheet, budgeting app, banking dashboard or more sophisticated financial management software, the right tool can turn scattered transactions into useful information.
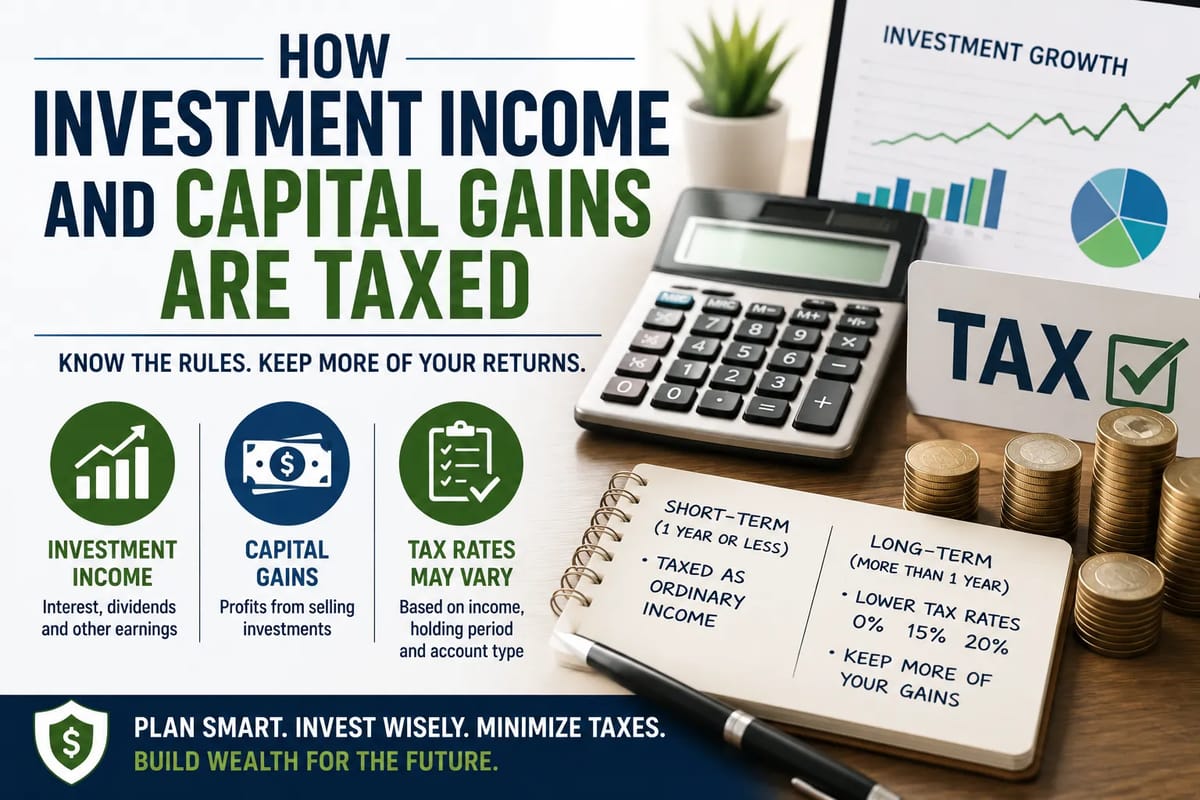
How Investment Income and Capital Gains Are Taxed
Understanding those differences can help investors avoid surprises at tax time and make more informed decisions about when and how to sell investments.
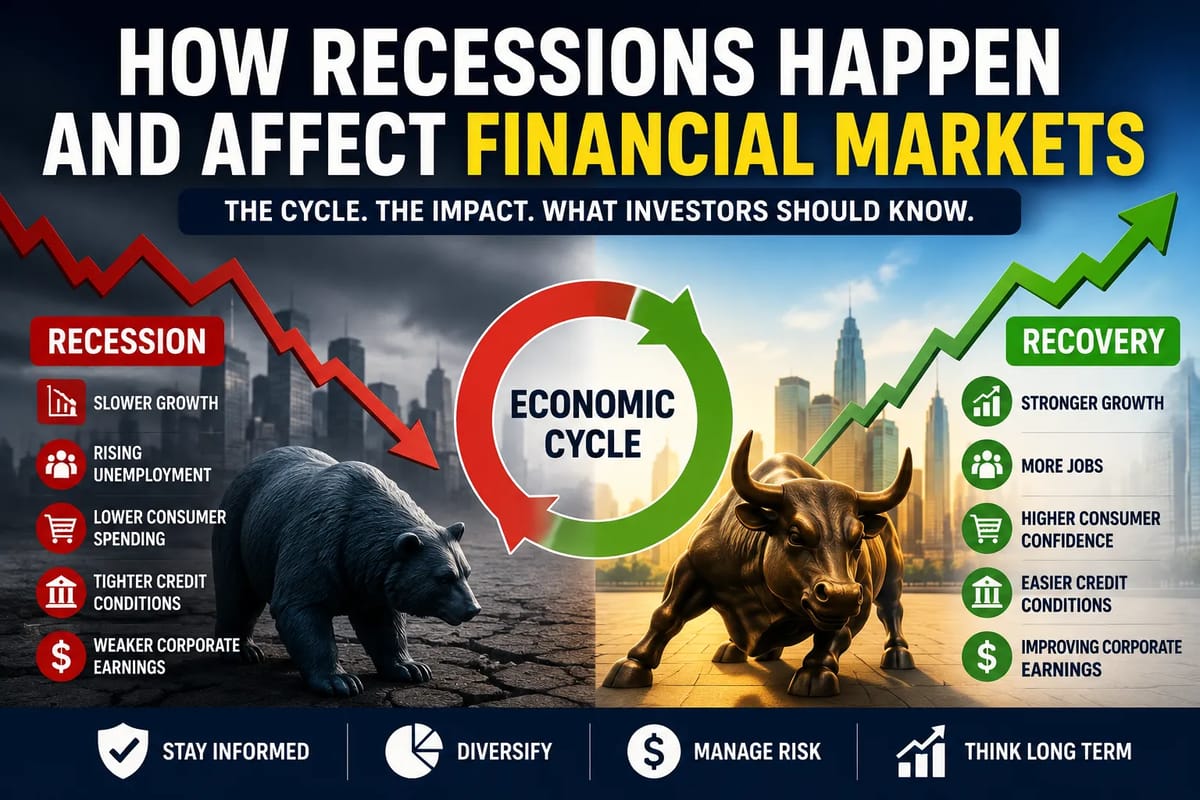
How Recessions Happen and Affect Financial Markets
Understanding how recessions develop—and how investors typically respond to them—can make economic headlines easier to interpret.
How to Manage Household Finances During Major Life Changes
The most effective approach is not to try to predict every expense. It is to create a financial system that can **adapt as circumstances change**.
How to Turn Knowledge and Teaching Skills Into Online Education Income
From live workshops and private tutoring to online courses, memberships, digital resources and educational newsletters, there are now numerous ways to package knowledge for people willing to pay for a solution to a problem.
U.S.-Canada Tariff Escalation Raises New Risks for Investors
For investors, the central issue is no longer simply which products face higher duties. It is whether the latest confrontation becomes another temporary negotiating tactic or develops into a longer-lasting deterioration in the North American trading relationship.
Popular Posts