How Investment Income and Capital Gains Are Taxed
Investing can help build wealth over time, but returns from stocks, bonds, mutual funds, real estate and other assets can create tax obligations along the way.
For U.S. taxpayers, investment income is not taxed in one universal way. The tax treatment depends on what type of income you receive, how long you hold an investment, your overall income and the type of account holding the investment.
Interest, dividends and capital gains can all appear on the same portfolio statement, but they may be subject to very different tax rules.
Understanding those differences can help investors avoid surprises at tax time and make more informed decisions about when and how to sell investments.
Note: This article focuses on U.S. federal income tax rules. State and local taxes can differ, and individual circumstances can change the result. Tax rules also change over time, so investors should verify current requirements with the IRS or a qualified tax professional.
For broader guidance on how investment decisions fit into an overall tax strategy, see the Complete Guide to Personal Taxes and Tax Planning.
What Counts as Investment Income?
Investment income generally refers to money earned from assets rather than from working for an employer or operating an active business.
Common examples include:
- Interest from savings accounts and bonds
- Dividends from stocks and funds
- Capital gains from selling investments
- Rental income in certain circumstances
- Royalties
- Certain annuity income
- Gains from investment real estate
The IRS generally considers investment-related income taxable unless a specific tax rule excludes it.
However, different forms of investment income can be taxed differently.
For a broader explanation of how different forms of income are reported and handled for tax purposes, see the Complete Guide to Income Taxes and Taxable Income.
Investment Income Versus Capital Gains
One of the most important distinctions is between income generated by an investment and profit from selling an investment.
Suppose you own shares of a company.
If the company pays you a dividend, that payment is investment income.
If the shares increase in value and you later sell them for more than you paid, the difference can be a capital gain.
These two forms of return can therefore have different tax consequences.
How Interest Income Is Generally Taxed
Interest is one of the simplest forms of investment income.
Interest may come from:
- Bank savings accounts
- Certificates of deposit
- Corporate bonds
- Treasury securities
- Certain money market investments
Generally, taxable interest is included in income for the year it is received or otherwise becomes taxable under the applicable tax rules.
Unlike long-term capital gains, ordinary taxable interest generally does not receive the preferential long-term capital-gains rates.
That means an investor’s ordinary income tax bracket can play an important role in determining how much tax is owed.
Certain types of interest can receive special treatment. For example, qualifying tax-exempt municipal bond interest may not be subject to regular federal income tax, although there can be exceptions and other tax consequences.
How Dividends Are Taxed
Dividends are payments made by companies or certain investment funds to shareholders.
There are two broad categories investors commonly encounter: qualified dividends and ordinary dividends.
Qualified dividends can receive the same preferential federal tax rates that generally apply to long-term capital gains, assuming the applicable requirements are satisfied.
Ordinary dividends generally do not receive those lower rates and are instead taxed at ordinary income tax rates.
Your brokerage or fund company typically provides information identifying the tax character of dividends on the appropriate tax forms.
What Makes a Dividend “Qualified”?
Not every dividend automatically qualifies for the lower tax rate.
Among other requirements, an investor generally must satisfy specific holding-period rules.
This means that simply owning a stock that pays dividends is not enough to guarantee that every dividend will receive preferential treatment.
Investors should review the tax information provided by their brokerage rather than assuming that all dividends are taxed identically.
What Is a Capital Gain?
A capital gain generally occurs when you sell a capital asset for more than its adjusted basis.
For investments such as stocks, the basis is often related to what you paid for the investment, although adjustments can affect the calculation.
For example:
- You purchase shares for $5,000.
- You later sell them for $7,000.
- Your taxable capital gain may be $2,000, before considering applicable adjustments, losses and other tax rules.
The important point is that an increase in the market value of an investment does not generally create a capital gain merely because the investment is worth more.
The gain generally becomes relevant for tax purposes when the asset is sold or otherwise disposed of in a taxable transaction.
Unrealized Gains Are Different
Suppose you buy shares for $10,000 and their market value rises to $15,000.
You have an unrealized gain of $5,000.
If you have not sold the shares, you generally have not realized that capital gain for regular federal income tax purposes.
If you later sell them for $15,000, the gain becomes realized.
This distinction is particularly important for long-term investors because an investment can increase substantially in value without generating an immediate capital-gains tax bill.
Short-Term and Long-Term Capital Gains
The length of time you hold an investment can have a major effect on its tax treatment.
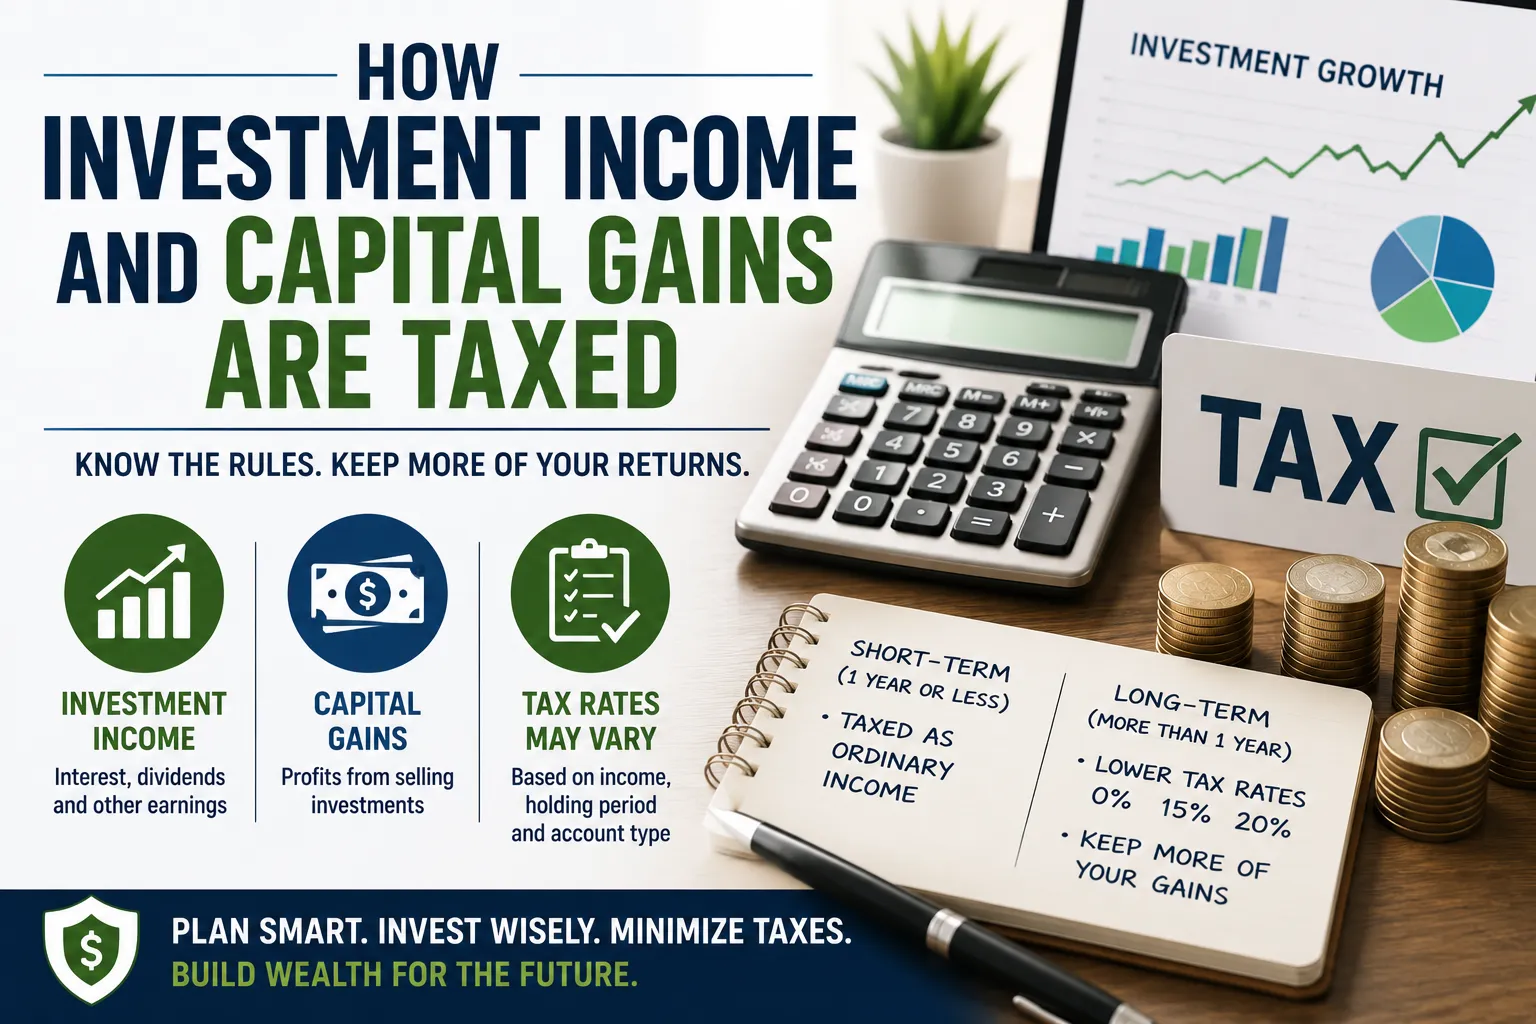
Under the general federal rules, an investment held for one year or less before being sold produces a short-term capital gain or loss.
An investment held for more than one year generally produces a long-term capital gain or loss.
That distinction matters because short-term capital gains are generally taxed at ordinary income tax rates.
Long-term capital gains can qualify for lower tax rates.
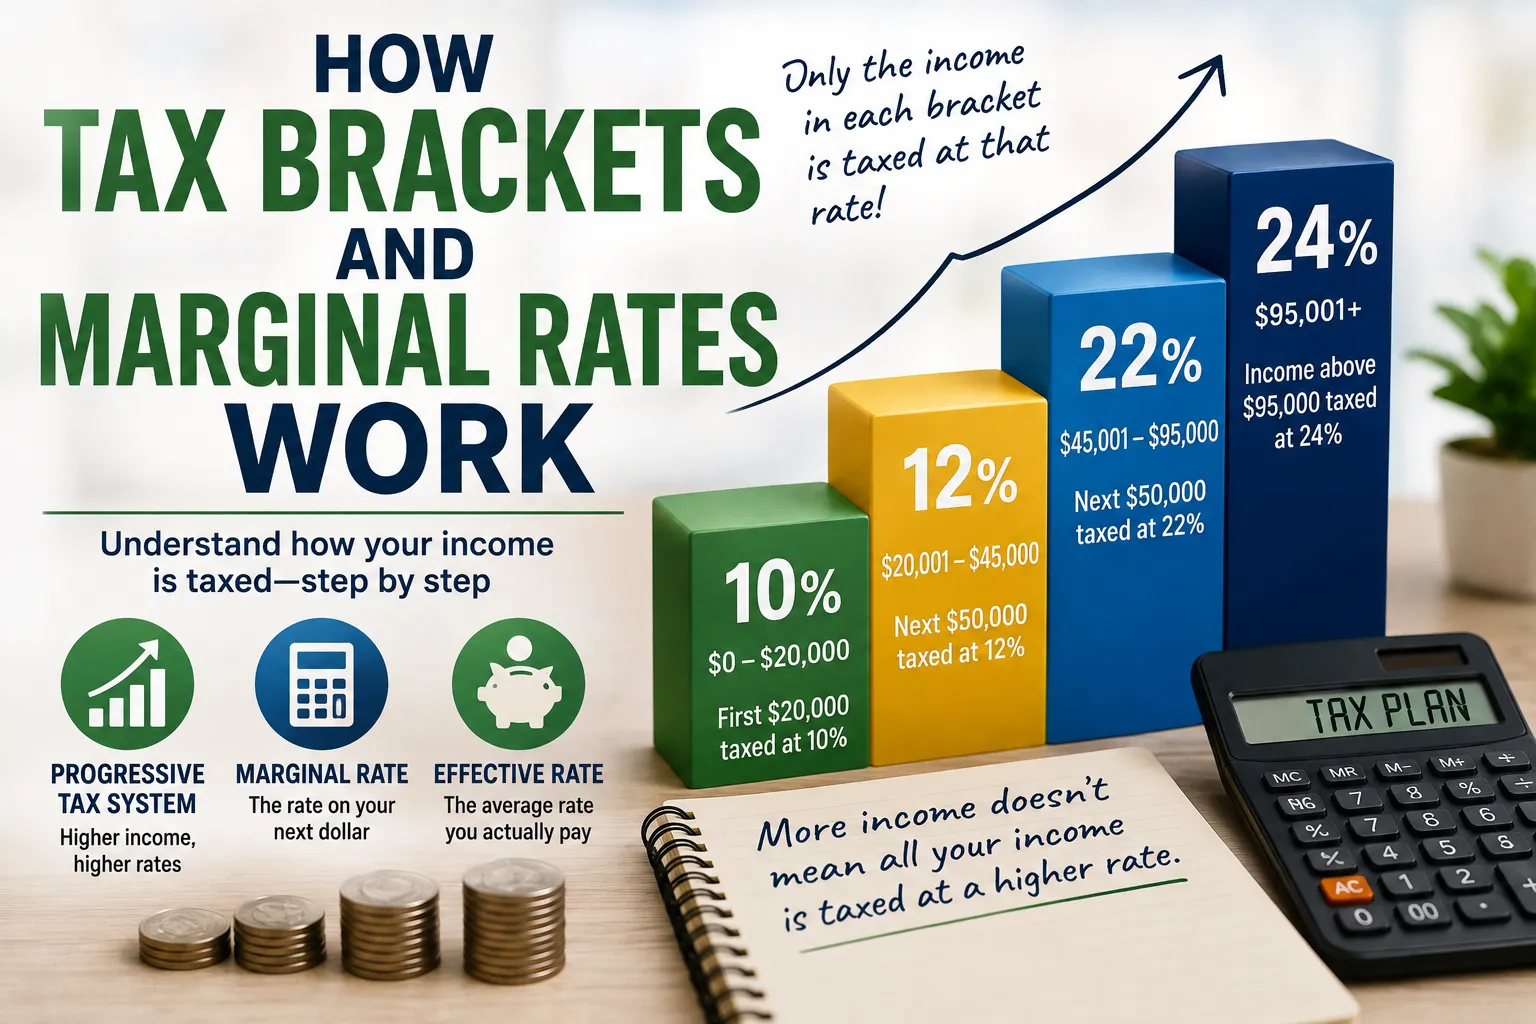
Investors who want to understand how these rates fit into their broader tax position should also review how tax brackets and marginal rates work.
Why Holding Period Matters
Consider two investors who each make a $10,000 profit.
Investor A sells an investment after holding it for eight months.
Investor B sells a similar investment after holding it for two years.
Their gains may be subject to different tax treatment because Investor A has a short-term gain while Investor B has a long-term gain.
This is one reason investors should consider the tax consequences before selling an appreciated asset.
Tax considerations should not necessarily determine every investment decision, but they can be an important part of the decision.
How Long-Term Capital Gains Are Taxed
For most individual taxpayers, long-term capital gains generally fall into preferential federal tax-rate categories.
For 2025, the IRS identifies maximum rates of 0%, 15% and 20% for most net capital gains, depending on taxable income. Certain categories of gains can be taxed at different maximum rates.
The applicable rate depends on the taxpayer’s overall taxable income and filing status.
This means there is no single capital-gains tax rate that applies to every investor.
The 0% Capital-Gains Rate
Some taxpayers can have qualifying long-term capital gains taxed at 0%.
This does not mean the investment itself is tax-free in every situation.
Instead, qualifying long-term gains can fall into a 0% federal capital-gains bracket when the taxpayer’s taxable income is within the applicable range.
For 2025, the IRS lists the 0% threshold at $48,350 for single and married-filing-separately taxpayers, $96,700 for married couples filing jointly and qualifying surviving spouses, and $64,750 for heads of household.
Those thresholds are specific to 2025 and can change for later tax years.
The 15% and 20% Rates
Taxpayers with higher taxable incomes can generally face a 15% or 20% long-term capital-gains rate on the portion of qualifying gains that falls into those brackets.
The calculation is based on the taxpayer’s overall taxable income rather than simply the size of the investment gain.
This is why two people who earn the same amount from selling an investment may not necessarily owe the same amount of federal capital-gains tax.
Short-Term Gains Usually Face Ordinary Income Rates
Short-term capital gains generally do not receive the preferential long-term capital-gains rates.
Instead, they are generally taxed at the taxpayer’s ordinary income tax rates.
For active investors who frequently sell investments after short holding periods, this distinction can significantly affect after-tax returns.
A strategy that generates frequent taxable gains can therefore create a larger tax bill than an investor might expect based solely on the portfolio’s headline return.
Capital Losses Can Reduce Capital Gains
Investments do not always increase in value.
When an investment is sold for less than its adjusted basis, the result can be a capital loss.
Capital losses can generally be used to offset capital gains, subject to the applicable tax rules.
This is one reason investors should consider their entire portfolio rather than looking at gains and losses in isolation.
Investors considering deductions, credits and other ways to reduce their overall tax liability can also review the Complete Guide to Tax Deductions and Credits.
What Happens When Losses Exceed Gains?
If total capital losses exceed capital gains, U.S. federal tax rules generally allow individuals to deduct up to $3,000 of excess net capital loss against other income in a tax year, or $1,500 for married individuals filing separately.
Unused losses can generally be carried forward to future years.
For investors with significant losses, this carryforward can become valuable over multiple tax years.
The Importance of Tax-Loss Harvesting
Some investors deliberately sell investments that have declined in value to realize capital losses.
This strategy is commonly known as tax-loss harvesting.
The realized losses may then offset realized capital gains, potentially reducing the investor’s current tax liability.
However, tax-loss harvesting has rules and limitations.
One important consideration is the wash-sale rule, which can limit the ability to claim a loss when an investor sells an investment and acquires substantially identical securities within the applicable period.
Investors should understand the rules before attempting to use losses purely for tax purposes.
Taxes Can Apply to Mutual Fund Distributions
Mutual fund investors sometimes receive taxable capital-gains distributions even when they personally did not sell their fund shares.
A fund may sell investments within its portfolio and distribute realized gains to shareholders.
Those distributions can create tax consequences for investors holding the fund in taxable accounts.
This can surprise investors who believe they only owe taxes when they personally sell their shares.
Exchange-Traded Funds Can Also Create Taxable Events
Exchange-traded funds can distribute taxable income and capital gains as well.
However, the tax efficiency of a particular fund depends on its structure, investment strategy, turnover and other factors.
Investors should review the fund’s tax documents and distribution history rather than assuming that every ETF will have identical tax characteristics.
Real Estate Investments Can Have Different Rules
Capital gains can also arise from investment property.
For example, an investor who purchases a rental property and later sells it for more than its adjusted basis may have a taxable gain.
Real estate taxation can be considerably more complicated than the taxation of publicly traded stocks because factors such as depreciation, improvements and the type of property can affect the calculation.
Certain portions of a real-estate gain can also be subject to special tax rates.
Rental Income Is Not the Same as a Capital Gain
A rental property can generate two distinct types of tax-related events.
The first is rental income received while the property is being rented.
The second is a potential capital gain when the property is eventually sold.
Rental income and expenses are generally handled under a different set of rules from the capital-gains calculation.
Investors should therefore keep careful records of rental income, expenses, improvements and other costs associated with the property.
Investment Accounts Can Change the Tax Picture
The same investment can have different tax consequences depending on where it is held.
A stock held in a regular taxable brokerage account may generate taxable dividends and capital gains.
A retirement account can follow very different tax rules.
For example, traditional retirement accounts generally defer taxation on qualifying investment earnings until distributions are taken, while qualified Roth distributions can generally be tax-free.
The specific rules depend on the type of account and the circumstances of the distribution.
Why Account Location Matters
Investors sometimes focus heavily on choosing individual investments while overlooking the tax characteristics of the account holding them.
In taxable accounts, investors generally need to consider:
- Dividend taxation
- Capital gains
- Capital losses
- Tax-efficient fund selection
- Trading frequency
In tax-advantaged accounts, the timing and character of investment income can be treated differently.
This makes asset location an important consideration in some investment strategies.
The Net Investment Income Tax
Higher-income investors may face an additional 3.8% Net Investment Income Tax, commonly called NIIT.
The tax applies to the lesser of net investment income or the amount by which modified adjusted gross income exceeds the applicable statutory threshold.
For individuals, the thresholds are:
- $200,000 for single or head-of-household filers
- $250,000 for married couples filing jointly or qualifying surviving spouses
- $125,000 for married individuals filing separately
The IRS says net investment income can include interest, dividends, capital gains, rents, royalties and certain other investment-related income.
This tax is separate from ordinary capital-gains taxation.
The NIIT Does Not Apply to Everyone With Investment Income
Having investment income does not automatically mean you owe the 3.8% NIIT.
The tax generally becomes relevant when both the taxpayer’s modified adjusted gross income exceeds the applicable threshold and there is net investment income subject to the tax.
The calculation can become complicated, particularly for people with multiple income sources, rental properties, businesses or substantial investment gains.
For investors with several types of income, understanding how to manage taxes on different income sources can be an important part of organizing their broader tax strategy.
Why Large Investment Sales Can Affect Taxes
Selling a highly appreciated investment can have consequences beyond the capital-gains tax on the investment itself.
A large gain can increase taxable income and potentially affect exposure to other taxes or income-based financial rules.
For example, a high-income taxpayer may need to consider whether an investment sale could increase exposure to the Net Investment Income Tax.
This is why planning the timing of a major asset sale can sometimes be important.
Tax Planning Does Not Mean Avoiding Taxes
Tax planning is about understanding the rules and making lawful financial decisions that take taxes into account.
Common considerations include:
- Choosing when to realize gains
- Managing investment losses
- Considering tax-advantaged accounts
- Understanding dividend taxation
- Maintaining accurate cost-basis records
- Reviewing the tax impact of major asset sales
The goal is not necessarily to eliminate taxes.
A profitable investment that creates a tax bill can still be a very good investment.
The important question is how much of the return remains after taxes and other costs.
Keep Track of Your Cost Basis
Cost basis is critical when calculating a capital gain or loss.
For a straightforward stock purchase, the basis may begin with the amount paid for the shares.
But the calculation can become more complicated after:
- Stock splits
- Reinvested dividends
- Corporate reorganizations
- Gifts
- Inherited assets
- Multiple purchases
- Certain adjustments
Brokerages generally provide cost-basis information for many investments, but investors should still review their records.
An incorrect basis can lead to an incorrect taxable gain or loss.
Reinvested Dividends Can Still Matter for Taxes
Investors who automatically reinvest dividends sometimes assume they did not receive taxable income because they never withdrew the money.
That can be a mistake.
A dividend can generally be taxable even if it is automatically used to purchase additional shares.
Those reinvested amounts can also affect the basis of the newly purchased shares.
Keeping accurate records is therefore important.
Taxable and Tax-Advantaged Accounts Should Be Viewed Differently
A diversified investment portfolio can contain multiple account types.
For example, an investor might hold:
- Stocks in a taxable brokerage account
- Bonds in a retirement account
- Index funds in a taxable account
- Roth investments for long-term goals
The tax treatment of returns can differ across those accounts.
This does not mean one account type is universally better.
It means investors should consider both what they own and where they own it.
How Taxes Affect Investment Returns
Imagine two investments that both generate a 10% pre-tax return.
If one produces more taxable income each year while the other generates most of its return through long-term appreciation that is not realized until later, their after-tax outcomes can differ.
Taxes are therefore part of an investment’s real cost.
A useful way to think about performance is:
After-tax return = investment return − taxes − investment costs
This is not a complete tax calculation, but it illustrates why investors should look beyond headline returns.
Don’t Let Taxes Drive Every Investment Decision
Tax efficiency matters, but it should not become the only reason to hold an investment.
For example, refusing to sell a poorly performing or unsuitable investment simply because selling would create a tax bill can lead to a larger financial mistake.
Taxes should be considered alongside:
- Investment risk
- Diversification
- Financial goals
- Time horizon
- Liquidity needs
- Expected returns
- Fees
The best decision is usually the one that makes sense for the overall financial plan.
Good Recordkeeping Makes Tax Season Easier
Investment taxes can become difficult when records are incomplete.
Keep documentation for:
- Purchase dates
- Purchase prices
- Sales
- Dividends
- Interest
- Capital-gains distributions
- Investment expenses where relevant
- Corporate actions
- Tax forms from financial institutions
Many brokerages provide annual tax documents, but investors should still review them carefully.
When Professional Tax Advice May Be Worthwhile
Simple investment portfolios can often be easier to manage from a tax perspective.
More complicated situations may justify professional advice.
Consider speaking with a qualified tax professional when dealing with:
- Large capital gains
- Investment property
- Business ownership
- Inherited investments
- Substantial stock compensation
- International investments
- Complex partnerships
- Large charitable gifts of appreciated assets
- Significant tax-loss harvesting
Professional advice can be particularly valuable before—not after—a major taxable transaction.
The Key Difference Is What You Earn and When You Sell
Investment taxation can seem complicated because the same portfolio may generate several different types of taxable income.
Interest can generally be taxed as ordinary income. Dividends can be qualified or ordinary. Capital gains can be short-term or long-term. Capital losses can offset gains subject to specific limits. Higher-income investors may also face the Net Investment Income Tax.
The most important concepts to remember are therefore straightforward:
Not all investment income is taxed the same way.
Selling an appreciated investment generally creates a taxable event, while an unrealized gain generally does not.
Holding an investment for more than one year can change the federal tax treatment of a capital gain.
Losses can sometimes reduce taxable gains.
And perhaps most importantly, the tax treatment of an investment should be considered as part of the broader financial plan rather than in isolation.
For investors, understanding these principles can make tax season less surprising and make long-term financial decisions more deliberate.