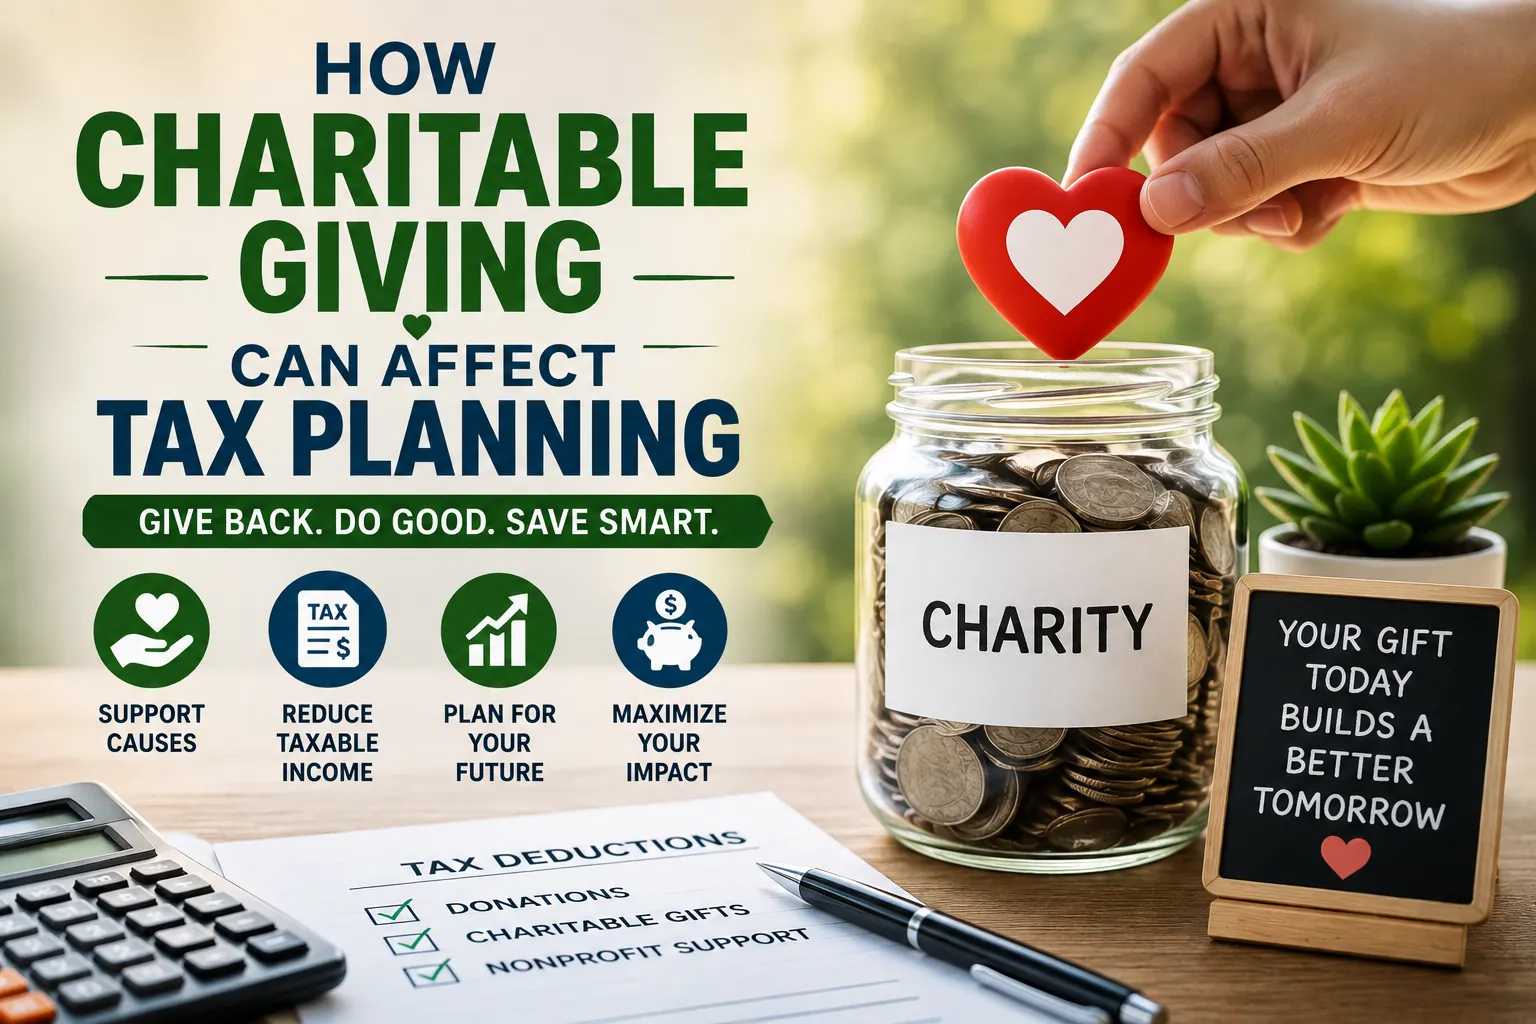
How Charitable Giving Can Affect Tax Planning
Charitable giving is often viewed primarily as a way to support causes, communities and organizations that matter to you. But donations can also play a role in financial planning, particularly when tax rules allow qualifying contributions to reduce taxable income or provide other tax benefits.
The important distinction is that giving money away is not automatically a way to save money on taxes. The tax treatment of a donation depends on factors such as where you live, the type of organization receiving the contribution, what you donate, how you make the gift and whether you qualify for a particular deduction or credit.
For that reason, charitable giving works best as part of a broader financial plan rather than as a tax strategy by itself.
For broader guidance on organizing your tax decisions, see the Complete Guide to Personal Taxes and Tax Planning.
How Charitable Giving and Taxes Are Connected
In many tax systems, governments provide some form of tax incentive for certain charitable contributions.
Depending on the jurisdiction, this may take the form of:
- A deduction from taxable income
- A tax credit
- A deduction for certain donated assets
- Special treatment for charitable trusts or similar arrangements
- Tax advantages for gifts made through particular accounts or structures
The rules can be very different from one country to another.
Even within the same country, tax treatment can depend on the taxpayer’s income, filing status and the type of donation.
Before making a large contribution for tax purposes, it is therefore important to understand the specific rules that apply to you.
A Tax Deduction Is Not the Same as Getting Your Donation Back
One of the most common misunderstandings about charitable deductions is assuming that donating $1,000 means receiving $1,000 back from the tax authority.
That is generally not how a deduction works.
A deduction typically reduces the amount of income subject to tax.
For example, if a qualifying $1,000 donation reduces taxable income, the actual tax savings depend on the taxpayer’s applicable tax rate and the rules governing the deduction.
The donation still costs money.
The tax benefit simply reduces the after-tax cost of making the contribution.
Tax Credits Work Differently
A tax credit generally operates differently from a deduction.
A deduction reduces taxable income, while a credit directly reduces the amount of tax owed, subject to the applicable rules.
This distinction can make credits particularly valuable.
However, charitable contributions do not automatically qualify for a tax credit simply because they qualify as charitable donations.
The specific tax rules determine whether a contribution receives a deduction, credit or no tax benefit.
Not Every Donation Qualifies
One of the most important rules for taxpayers is that a contribution to a good cause is not necessarily a tax-deductible contribution.
Tax systems generally establish requirements for organizations that qualify for charitable tax treatment.
Depending on the jurisdiction, qualifying organizations may include certain:
- Registered charities
- Religious organizations
- Educational institutions
- Public-benefit organizations
- Foundations
- Community organizations
A donation to an individual, political organization or nonqualifying group may receive different treatment.
Before making a large donation, check whether the recipient organization qualifies under the relevant tax rules.
Keep Documentation for Your Donations
Good recordkeeping is one of the simplest ways to make charitable giving easier at tax time.
Depending on the type and value of the contribution, documentation may include:
- Receipts
- Donation confirmations
- Bank or payment records
- Written acknowledgments from the charity
- Records describing donated property
- Valuation documents
- Information about the organization receiving the gift
The exact documentation requirements vary by jurisdiction and donation type.
Keeping records as soon as you make a donation is generally easier than trying to reconstruct them months later.
Cash Donations Are Usually the Simplest
Cash donations are often the easiest charitable contributions to document.
A donation made through a bank transfer, credit card, check or an organization’s online payment system can generally produce a straightforward transaction record.
However, taxpayers should still retain the appropriate receipt or acknowledgment where required.
The simplicity of cash donations can make them particularly convenient for people who want to give regularly throughout the year.
Donating Property Can Create More Complicated Tax Questions
Charitable giving does not have to involve cash.
People may donate:
- Clothing
- Furniture
- Electronics
- Vehicles
- Artwork
- Shares
- Other investments
- Real estate
The tax treatment of donated property can be considerably more complicated.
The relevant value may depend on the property’s fair market value, original purchase price, holding period and other factors.
For valuable assets, professional tax advice can be worthwhile before making the donation.
Donating Appreciated Investments Can Be Different From Selling Them
One particularly important planning consideration involves investments that have increased significantly in value.
Suppose an investor owns shares that were purchased for $10,000 and are now worth $30,000.
Selling those shares could potentially create a taxable capital gain, depending on the applicable tax rules.
In some jurisdictions, donating qualifying appreciated assets directly to an eligible charity can produce different tax consequences from selling the asset and donating the cash afterward.
The potential benefits depend heavily on local law, the type of asset and how long it has been held.
This is an area where professional advice can be particularly valuable because the tax outcome can be significantly different depending on how the transaction is structured.
For additional context on investment taxation, see How Investment Income and Capital Gains Are Taxed.
Consider Charitable Giving When Creating a Yearly Tax Plan
Charitable donations do not have to be considered only at the end of the tax year.
Instead, giving can be incorporated into an annual financial plan.
At the beginning of the year, you might estimate:
- How much you expect to earn
- How much you plan to save
- How much you expect to pay in taxes
- Which charitable causes you want to support
- Whether your planned donations may qualify for tax benefits
This approach can help prevent charitable contributions from becoming an afterthought.
It also makes it easier to budget for giving without disrupting other financial priorities.
Regular Giving Can Make Budgeting Easier
Some people prefer to make one large donation each year.
Others give smaller amounts throughout the year.
Regular contributions can make charitable giving easier to incorporate into a household budget.
For example, someone who wants to donate $1,200 annually could set aside $100 each month.
The exact amount is less important than creating a giving plan that fits comfortably within available income.
Tax considerations can then be incorporated into the plan rather than determining how much the person gives.
Don’t Let Tax Savings Determine Your Entire Giving Strategy
Tax benefits can be useful, but they should not become the sole reason for donating.
If you give $1,000 primarily because you expect a tax benefit, you are still spending $1,000.
The tax benefit may reduce the after-tax cost, but it does not make the contribution free.
A better approach is to start with the amount you genuinely want to give and then determine how the donation can be made in the most tax-efficient way permitted by law.
Consider Your Overall Tax Situation
The value of a charitable deduction can depend on your broader tax position.
For example, a taxpayer with relatively low taxable income may receive a different benefit from a deduction than a taxpayer with substantially higher taxable income.
Similarly, limits may apply to how much charitable giving can be deducted in a particular year.
This means that the same $5,000 donation can have different tax consequences for different households.
Charitable planning should therefore be considered alongside the rest of your tax situation.
Donation Limits Can Matter
Some tax systems limit the amount of charitable contributions that can be deducted in a particular tax year.
If your donations exceed the applicable limit, you may not receive the full tax benefit immediately.
Some jurisdictions allow qualifying excess contributions to be carried forward to future tax years.
The rules vary, so taxpayers considering unusually large donations should understand the applicable limits before making the contribution.
Large Donations May Require Additional Planning
A substantial charitable contribution can create more complicated tax and financial-planning considerations.
For example, someone who wants to donate a large amount might need to consider:
- The timing of the contribution
- The type of asset being donated
- The organization’s eligibility
- Applicable deduction limits
- Required documentation
- Valuation requirements
- The donor’s current and future tax position
A large donation should therefore be planned carefully rather than made solely because a tax deadline is approaching.
Timing Can Matter
The timing of charitable giving can affect which tax year receives the potential benefit.
A contribution made in one tax year may have different implications from a contribution made in the next.
This can matter particularly when income changes significantly from year to year.
For example, someone expecting unusually high income in one year may want to examine whether concentrating qualifying charitable contributions in that year produces a more useful tax result than spreading the same contributions across several years.
Whether that strategy works depends on the applicable tax rules.
Life Changes Can Affect Charitable Planning
Tax planning should change when your financial circumstances change.
Events that may affect charitable giving decisions include:
- Starting a business
- Receiving a large bonus
- Selling an investment
- Selling a property
- Retiring
- Receiving an inheritance
- Experiencing a major change in income
- Entering a different tax bracket
- Moving to another jurisdiction
A charitable strategy that made sense several years ago may no longer be optimal.
For another perspective on how changing circumstances can alter your tax position, see How Major Life Changes Can Affect Your Taxes.
Charitable Giving Can Fit Into Retirement Planning
Charitable giving can also become part of retirement planning.
Retirees may have different sources of income, including pensions, investment accounts and government benefits.
Depending on the country’s tax rules and the type of retirement account, charitable contributions may interact with retirement withdrawals and taxable income in different ways.
Some jurisdictions also provide special rules for donations made directly from certain retirement accounts.
Because retirement-account rules can be complicated, taxpayers should verify the current requirements before making a large contribution.
Estate Planning and Charitable Giving
Charitable giving does not have to happen entirely during your lifetime.
Some people include charitable organizations in their estate plans.
Possible approaches can include:
- Leaving a charitable bequest in a will
- Naming a charity as a beneficiary of certain assets
- Establishing a charitable trust
- Creating or contributing to a foundation
- Making planned gifts
The tax and legal consequences can vary significantly.
Estate planning also involves issues beyond taxes, including inheritance arrangements, family needs and the legal requirements governing wills and trusts.
For related planning considerations, see How Estate Planning Can Affect Inheritance and Taxes.
Charitable Giving Can Reflect Your Values and Financial Goals
Financial planning is not only about minimizing taxes.
It is also about deciding how money should be used to support the life you want.
For many people, charitable giving is part of that picture.
A well-designed financial plan can accommodate giving alongside:
- Emergency savings
- Retirement contributions
- Debt repayment
- Housing costs
- Education expenses
- Investments
- Family financial goals
This can make charitable contributions sustainable rather than something that competes unexpectedly with essential financial priorities.
Don’t Give Away Money You Need for Essential Expenses
Tax benefits should never override basic financial security.
Before increasing charitable contributions, make sure your household can comfortably cover essential expenses.
Important priorities may include:
- Housing
- Food
- Utilities
- Insurance
- Debt payments
- Emergency savings
- Necessary medical or family expenses
Someone who gives more than they can afford may eventually need to borrow money to cover basic costs.
That defeats the purpose of building a healthy financial plan.
Watch Out for Donation Scams
Charitable giving also requires basic fraud awareness.
Scammers may exploit natural disasters, humanitarian emergencies and emotionally powerful causes to solicit money.
Before donating, verify:
- The organization’s name
- Its official website
- Its registration status where applicable
- How the donation will be processed
- Whether the recipient qualifies for tax benefits
Be particularly cautious when someone pressures you to make an immediate payment or requests unusual payment methods.
If a tax deduction matters to you, verify the organization’s eligibility before donating.
Be Wary of Tax Strategies That Sound Too Good to Be True
Some financial arrangements are marketed primarily around tax savings.
Be cautious when someone claims that you can make money by donating money or promises an unusually large tax benefit with little economic cost.
Legitimate charitable planning generally involves a real contribution to a qualifying organization and compliance with applicable tax rules.
If a strategy seems designed primarily to manufacture a deduction rather than support a genuine charitable purpose, it deserves careful scrutiny.
Work With a Tax Professional for Complex Gifts
Simple cash donations may not require professional advice.
More complicated contributions can be different.
Consider obtaining professional guidance before donating:
- Highly appreciated investments
- Real estate
- Closely held business interests
- Valuable collectibles
- Large estates
- Substantial retirement assets
- Assets subject to complicated tax rules
A qualified tax adviser can help determine how the contribution fits into your broader financial situation.
A Simple Charitable Giving Checklist
Before making a donation, ask yourself:
Is the organization legitimate?
Verify the recipient before sending money.
Does it qualify for tax benefits?
Do not assume every nonprofit or community organization qualifies.
Can I comfortably afford the donation?
Giving should not undermine essential household expenses.
What documentation do I need?
Keep receipts and other required records.
What am I donating?
Cash and property may receive different tax treatment.
When am I making the contribution?
Timing may affect the tax year in which the contribution is recognized.
Is the gift large or complicated?
If so, professional advice may be worthwhile.
Tax Planning Should Support the Giving Goal
The most effective charitable tax planning starts with a simple principle: give because you want to support the organization or cause, then consider how the tax rules can help you do that efficiently.
For some taxpayers, a straightforward cash contribution may be the best option. Others may benefit from exploring donations of appreciated investments, planned gifts or other qualifying arrangements.
The right approach depends on personal finances and local tax law.
Charitable giving can therefore occupy an interesting place in financial planning. It combines personal values with practical considerations about income, assets, taxes and long-term goals.
When planned carefully, donations can support causes you care about while potentially providing legitimate tax benefits. But the tax benefit should remain part of the calculation—not the reason to give more than your financial situation can comfortably support.