What Do Banks Do With Customer Deposits?
When people put money into a bank account, it can seem as though the bank simply holds that money in a secure place until the customer needs it. In reality, commercial banking is more complex.
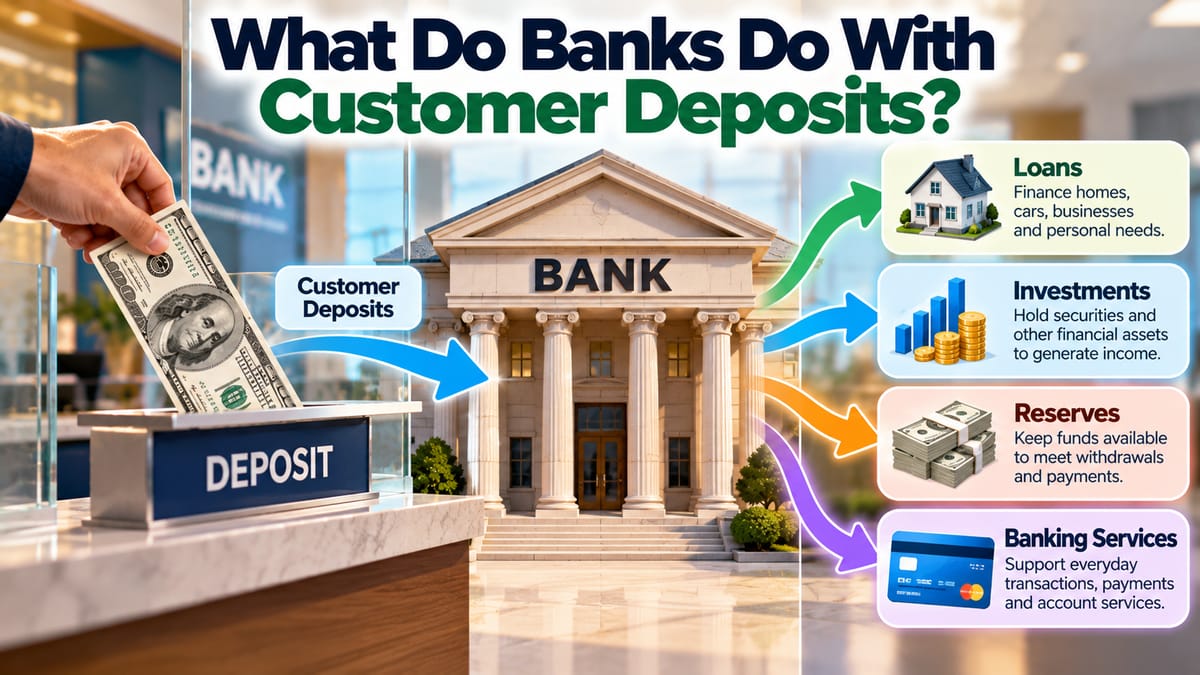
Banks use deposits as an important source of funding for their broader operations. They hold some funds in forms that can be used to meet customer withdrawals and payment needs, while other funds support lending and investment activities within the rules established by regulators.
This system allows banks to provide services such as checking accounts, savings accounts, loans, payment services, and other financial products.
Understanding what happens to deposits also helps explain how banks make money, why banks need liquidity, and why the banking system is closely connected to central banks and financial markets.
What Is a Bank Deposit?
A bank deposit is money placed with a financial institution for safekeeping and use through an account.
Common deposit accounts include:
- Checking accounts
- Savings accounts
- Time deposits
- Certificates of deposit
- Certain business transaction accounts
- Other deposit products offered by banks
When a customer deposits money, the bank records the amount as a liability on its balance sheet.
This may seem surprising because the money belongs to the customer. From the bank’s accounting perspective, however, the deposit represents an obligation to the customer.
The bank generally owes the customer the amount available in the account, subject to the account’s terms and applicable banking rules.
Why Are Customer Deposits Important to Banks?
Deposits are one of the major sources of funding for commercial banks.
Banks can use their funding base to support activities such as:
- Making loans
- Purchasing certain financial assets
- Maintaining liquidity
- Processing payments
- Funding day-to-day operations
- Meeting withdrawal demands
The difference between the interest a bank earns on certain assets and the interest it pays on deposits can contribute to the bank’s earnings.
Other banking revenue comes from fees and financial services. How Banks Make Money From Interest, Fees and Financial Services provides a broader explanation of these revenue sources.
Banks Do Not Simply Keep All Deposits in a Vault
A common misconception is that banks place all customer deposits into a vault and then return exactly the same physical money when customers withdraw it.
Modern banking does not generally operate this way.
Most money in bank accounts exists as electronic account balances rather than as physical banknotes.
Banks manage their balance sheets so they can meet expected customer withdrawals and payment obligations while using their available funding to support lending and other permitted activities.
The result is a financial system in which money moves continuously between customers, businesses, banks, and other financial institutions.
Deposits Are Bank Liabilities
A bank’s balance sheet can broadly be divided into assets, liabilities, and equity.
Customer deposits generally appear on the liability side.
Bank assets can include:
- Loans to customers
- Cash and reserves
- Certain securities
- Balances held with other institutions
- Other financial assets
Liabilities can include:
- Customer deposits
- Borrowings
- Other obligations
Equity represents the bank’s capital belonging to its owners.
This structure allows a bank to use funding from deposits and other sources to acquire assets that generate income.
How Deposits Support Lending
One of the most important functions of deposits is providing funding for lending.
When a bank makes a loan, it does not necessarily take a particular customer’s deposited banknotes and hand them directly to the borrower.
Instead, modern banking involves balance-sheet entries and the creation and transfer of deposit balances as loans are originated and payments move through the financial system.
The relationship between deposits, bank lending, and money creation is more complicated than the simple idea that banks “lend out deposits.”
The How Do Banks Create and Lend Money? guide explains this process in greater detail.
What Happens When a Bank Makes a Loan?
Suppose a customer is approved for a loan.
The bank records the loan as an asset because the borrower has an obligation to repay it, including applicable interest.
At the same time, depending on the structure of the transaction, the bank can create a deposit in the borrower’s account.
The borrower can then use that balance to make payments.
When the borrower spends the money, it can move to another person’s or company’s bank account.
This illustrates why deposits and lending are interconnected rather than completely separate activities.
Deposits Can Move Between Banks
Customers frequently transfer money from one bank to another.
For example, a person may use their bank account to:
- Pay a retailer
- Send money to another person
- Pay a utility bill
- Receive a salary
- Transfer money to a different bank
- Pay a loan
- Purchase goods online
When money moves between banks, the institutions need mechanisms for settling those transactions.
This can involve payment networks, clearing systems, central bank settlement systems, or other financial infrastructure depending on the country and transaction type.
Banks Need Liquidity
Although banks use deposits to support lending and other activities, they must also be able to meet customers’ demands for withdrawals and payments.
This requires liquidity management.
Liquidity refers broadly to the ability to obtain or use funds when they are needed without unacceptable delay or loss.
Banks therefore manage different types of assets and funding sources to ensure they can meet their obligations.
Liquidity management can involve:
- Cash
- Central bank balances
- Highly liquid securities
- Incoming payments
- Borrowing arrangements
- Other sources of readily available funds
The exact liquidity requirements and regulatory standards differ by jurisdiction.
Why Customers Can Withdraw Money on Demand
Checking accounts are designed to provide convenient access to funds.
A customer may use an account balance through:
- Cash withdrawals
- Debit cards
- Electronic transfers
- Checks where available
- Bill payments
- Online payments
- Mobile banking
Banks anticipate that customers will not all withdraw their entire balances simultaneously under normal conditions.
This allows the banking system to operate while maintaining sufficient liquidity for ordinary customer activity.
The Complete Guide to Checking Accounts and Everyday Banking explains how everyday deposit accounts function and how customers typically use them.
What Happens to Savings Deposits?
Savings accounts can provide customers with a place to hold money while potentially earning interest.
From the bank’s perspective, savings deposits provide funding that can support the institution’s balance sheet.
Banks may use their overall funding base to support loans and investments while managing liquidity and regulatory requirements.
The interest paid to customers is one of the bank’s funding costs.
If a bank earns more interest from certain assets than it pays on deposits and other funding sources, the difference can contribute to its net interest income.
Why Banks Pay Interest on Some Deposits
Banks may pay interest to attract and retain deposits.
Customers have alternatives for storing or investing their money, so banks compete for funding in various ways.
Interest rates on deposits can be influenced by:
- Market interest rates
- Competition among banks
- Central bank policy
- The type of account
- Account balance
- Deposit term
- Bank funding needs
- Broader economic conditions
Some transaction accounts may pay little or no interest, while savings and time deposits may offer higher rates depending on market conditions.
Time Deposits Provide Different Funding Characteristics
A time deposit generally requires funds to remain in the account for a specified period or may impose conditions on early withdrawal.
From the bank’s perspective, deposits with defined terms can provide a more predictable source of funding.
Customers may receive a higher interest rate in exchange for accepting restrictions on access.
The exact structure varies among financial institutions and jurisdictions.
Banks Use Deposits to Support the Broader Economy
Bank deposits are connected to economic activity because banks use their funding and balance sheets to provide financial services to households and businesses.
Bank lending can support:
- Home purchases
- Business expansion
- Equipment purchases
- Education
- Vehicle purchases
- Working capital
- Construction
- Consumer spending
When a bank provides financing, the borrower can use the funds for economic activity while the bank earns income from the loan.
Deposits therefore play an important role in connecting savers, borrowers, businesses, and financial institutions.
Banks Also Hold Financial Assets
Banks do not necessarily use all available funding for customer loans.
Depending on applicable laws and their business models, banks can hold financial assets such as government securities and other permitted investments.
These assets can provide income and may also contribute to liquidity management.
The exact types of assets banks can hold and the limits imposed on them depend on regulatory requirements and the institution’s strategy.
What Role Do Central Banks Play?
Commercial banks operate within a wider monetary and financial system.
Central banks influence financial conditions through monetary policy, banking regulation, payment systems, and other functions.
Depending on the country, commercial banks may maintain accounts or reserves with the central bank.
Central banks can also influence short-term interest rates and the broader cost of funding in the financial system.
The How Central Banks Affect Commercial Banks guide provides more detail on this relationship.
Bank Reserves Are Different From Customer Deposits
Bank reserves and customer deposits are related but are not the same thing.
A customer’s deposit is a liability of the commercial bank.
A commercial bank’s reserve balance at a central bank is generally an asset of that commercial bank.
This distinction becomes particularly important when examining how payments settle between banks.
For example, when a customer at one bank transfers money to a customer at another bank, the banks need to settle the transaction between themselves.
Depending on the country’s payment infrastructure, central bank money can play an important role in that settlement.
What Happens When Customers Deposit Cash?
When a customer deposits physical cash, the bank records the corresponding deposit in the customer’s account.
The physical cash becomes part of the bank’s cash holdings and may eventually be processed through the banking system.
The bank does not necessarily keep those exact banknotes reserved for that specific customer.
Instead, the customer’s account reflects the bank’s obligation to provide the customer with the corresponding amount according to the account’s terms.
What Happens When Customers Deposit a Check?
When checks are used, banks generally need to process and clear them.
A deposited check may not immediately represent fully settled funds.
The banking system verifies and processes the payment between the relevant institutions.
This is why funds from certain deposits may be subject to availability periods or other conditions.
Modern electronic payment systems have reduced reliance on traditional paper checks in many markets, but check processing remains relevant in some banking systems.
Electronic Deposits Are Increasingly Common
Most everyday deposits now occur electronically rather than through physical cash.
Examples include:
- Salary payments
- Government payments
- Bank transfers
- Mobile payments
- Business receipts
- Electronic deposits
- Transfers between accounts
Electronic transactions allow money to move through the financial system without requiring physical currency to change hands.
The bank records account balances and processes the corresponding payment instructions through the relevant infrastructure.
What Happens When Customers Withdraw Money?
When a customer withdraws money, the bank reduces the customer’s deposit balance.
If the withdrawal is made in cash, the bank provides physical currency.
If the customer transfers funds to another bank, the transaction is settled through the relevant payment system.
The bank therefore needs sufficient liquidity and operational capacity to fulfill these obligations.
This is one reason banks continuously monitor cash flows and expected withdrawals.
Why Banks Cannot Ignore Liquidity Risk
A bank can have valuable assets and still face serious problems if it cannot obtain funds when obligations become due.
For example, many loans may be valuable because borrowers are expected to repay them over time. But loans generally cannot be converted into cash instantly without potentially affecting their value.
This creates a difference between solvency and liquidity.
Solvency concerns whether a bank’s assets are sufficient to cover its obligations over the relevant period.
Liquidity concerns whether the bank can meet obligations as they become due.
Both are important to banking stability.
Deposit Insurance Can Protect Eligible Depositors
Many countries operate deposit protection or deposit insurance systems.
These systems can provide protection for eligible deposits up to specified limits if a covered bank fails.
The exact rules vary by country, including:
- Which banks are covered
- Which accounts qualify
- Maximum protection limits
- How compensation is provided
- Which types of deposits are excluded
Customers should understand the deposit protection framework applicable to their bank rather than assuming that every balance receives unlimited protection.
Banks Manage Deposit Concentration
Banks also pay attention to where their deposits come from.
A bank with a large number of stable retail deposits may have a different funding profile from a bank that relies heavily on a smaller number of large institutional deposits.
Funding concentration can affect liquidity planning.
Banks therefore monitor characteristics such as:
- Deposit size
- Customer type
- Account type
- Maturity
- Withdrawal patterns
- Geographic concentration
- Business concentration
Managing these factors helps banks understand how their funding could behave under different circumstances.
Deposits Can Be Stable or More Sensitive to Market Conditions
Not all deposits behave in exactly the same way.
Some customers maintain relatively stable balances for everyday financial needs. Others may move substantial funds when interest rates, market conditions, or financial circumstances change.
Banks therefore use historical information and financial models to estimate how deposits might behave.
These estimates are important for liquidity and risk management.
Why Banks Want Customers to Keep Deposits
Deposits can provide relatively important funding for banks.
Banks may compete for deposits by offering:
- Interest
- Convenient digital banking
- Low or reduced fees
- Rewards
- Payment services
- ATM access
- Mobile applications
- Business banking services
- Other financial products
A customer who keeps money in a bank may also use loans, credit cards, investment services, insurance products, or payment services offered by the institution.
This creates multiple potential sources of revenue for the bank.
Deposits and Bank Profitability
Customer deposits can contribute to bank profitability in several ways.
The most familiar is the relationship between deposit funding and lending.
A simplified example illustrates the concept.
Suppose a bank pays an average of 2% on certain deposits while earning an average of 7% on a group of loans and other interest-generating assets.
The difference between those rates is not automatically the bank’s profit because the bank has many other expenses and risks.
It may need to account for:
- Employee costs
- Technology
- Branches
- Regulatory expenses
- Credit losses
- Funding costs
- Taxes
- Operational expenses
- Interest-rate risk
- Other financial costs
Nevertheless, the difference between interest earned and interest paid is an important component of traditional banking economics.
Banks Must Manage Credit Risk
When deposits support lending, banks take on credit risk.
A borrower may fail to repay a loan fully or on time.
Banks therefore evaluate factors such as:
- Borrower income
- Existing debt
- Credit history
- Collateral
- Business performance
- Cash flow
- Loan purpose
- Economic conditions
The bank must balance the potential income from lending against the possibility of losses.
This is one reason banks cannot simply lend every available dollar without considering risk.
Deposits and Interest Rates
Interest rates affect both sides of the banking business.
When market interest rates change, banks may adjust the rates offered on deposits and charged on loans.
The speed and extent of those changes vary.
A bank might increase savings rates to attract deposits while also adjusting loan rates as its funding costs change.
Central bank policy can influence these conditions, but individual banks also respond to competition and their own funding needs.
What Happens During Financial Stress?
During periods of financial uncertainty, customers may behave differently.
Some may withdraw funds, move money between banks, or shift money between different types of financial assets.
Banks therefore maintain contingency plans for liquidity pressures.
Regulatory frameworks can also require banks to maintain capital, liquidity, reporting systems, and risk-management procedures designed to improve resilience.
The exact requirements vary by jurisdiction and bank type.
Why Banking Depends on Trust
Banking is fundamentally dependent on confidence.
Customers need to believe that they can access their money when required and that the bank will operate according to applicable rules.
Banks therefore invest heavily in:
- Cybersecurity
- Fraud prevention
- Risk management
- Compliance
- Internal controls
- Liquidity management
- Operational resilience
- Customer authentication
A bank’s ability to process payments and withdrawals reliably is an essential part of its relationship with customers.
Customer Deposits and Digital Banking
Digital banking has changed how people interact with their deposits.
Customers can now often:
- Check balances instantly
- Transfer money
- Deposit checks through mobile applications
- Pay bills
- Send payments
- Manage savings
- Receive transaction alerts
Despite these technological changes, the underlying financial relationship remains similar.
The bank records a customer’s balance as a deposit liability and manages the broader balance sheet and payment infrastructure needed to support that account.
Deposits Are Part of a Larger Financial System
A customer deposit may appear to be a simple balance displayed on a banking application, but it is connected to a much larger system.
That balance is linked to:
- The bank’s balance sheet
- Payment networks
- Lending activities
- Liquidity management
- Central banking systems
- Financial markets
- Regulatory requirements
- Deposit protection arrangements
This interconnected structure is what allows banks to provide both everyday payment services and broader financial intermediation.
A Simple Example of How Deposits Move Through Banking
Imagine a customer deposits $1,000 into a checking account.
The bank records a $1,000 deposit liability.
The customer later uses $200 to pay a local business.
The business deposits or receives that money through its own bank account.
The funds have now moved from one customer’s account to another economic participant.
The original bank may need to settle the payment with another institution if the recipient uses a different bank.
Meanwhile, the bank continues managing its overall assets, liabilities, liquidity, and capital.
The $1,000 deposit was therefore not simply sitting untouched in a vault. It was part of a continuously operating financial system.
The Bigger Role of Customer Deposits
Customer deposits provide banks with an important source of funding and form a central part of everyday banking.
Banks use their balance sheets to manage deposits, loans, investments, liquidity, capital, and other obligations. They also operate payment systems that allow customers to move money between people, businesses, and financial institutions.
For customers, the visible part of banking may simply be a checking or savings balance. Behind that balance is a complex system designed to maintain access to funds while allowing banks to provide lending and other financial services.
Understanding what banks do with deposits helps explain why checking accounts, savings accounts, loans, interest rates, central banks, and payment systems are so closely connected.
A deposit is therefore more than money being stored. It is a claim against a financial institution and an important component of the broader banking system that moves money through the economy.