How to Use a Compound Interest Calculator for Savings Growth
Saving money is often described as a matter of putting money aside consistently, but the way those savings grow can be just as important as the amount being saved. Compound interest allows previously earned interest to become part of the balance, giving future interest a larger amount to work with.
A compound interest calculator makes this process easier to understand. Instead of manually calculating how an account might grow over several years, you can enter a few basic figures and see how the balance could change over time.
Understanding how to use the calculator correctly can also make it easier to compare savings goals, interest rates, contribution schedules, and time horizons.
What Is Compound Interest?
Compound interest is interest earned on both the original amount saved and the interest that has accumulated previously.
For example, imagine depositing money into an account that earns interest. After the first period, the account earns interest on the initial deposit. If that interest remains in the account, the next interest calculation can be based on the larger balance.
Over many years, this repeated process can have a substantial effect on savings growth.
Compound interest is different from simple interest, where interest is calculated only on the original principal.
What a Compound Interest Calculator Does
A compound interest calculator estimates how a savings balance could grow based on several inputs.
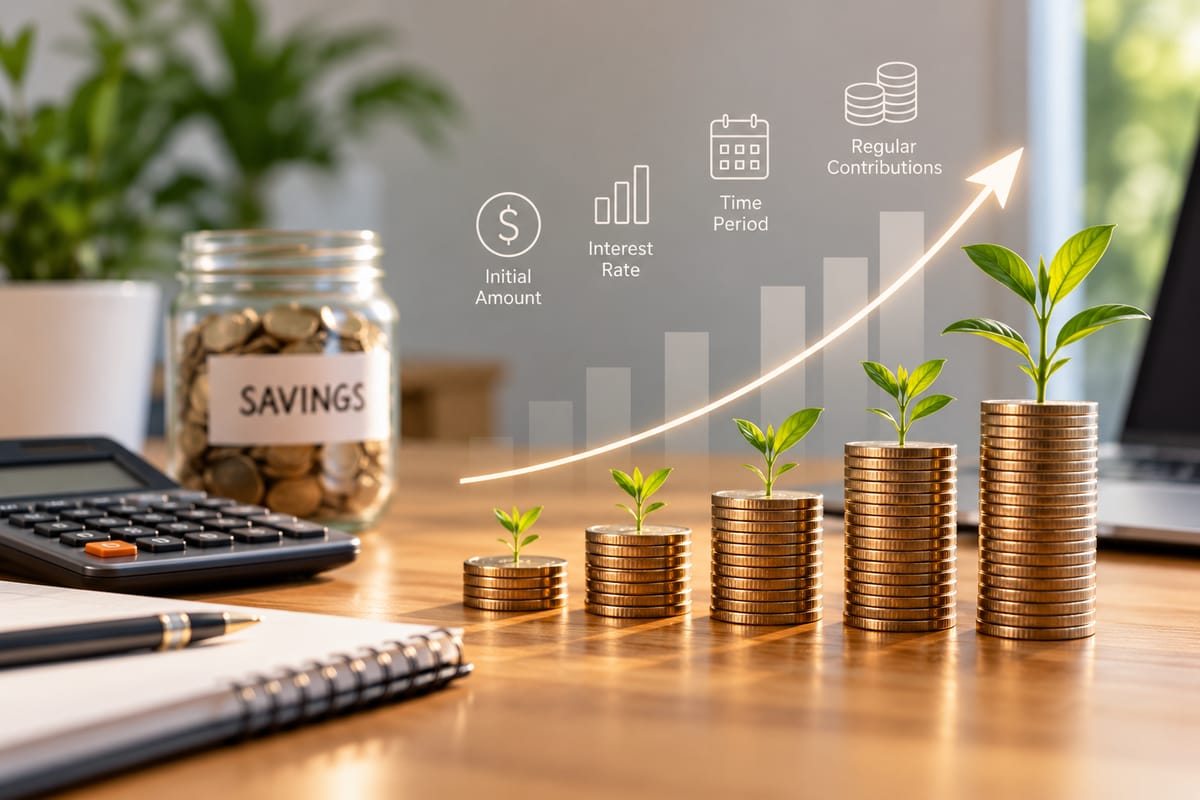
Most calculators ask for some combination of:
- Initial deposit
- Interest rate
- Compounding frequency
- Length of time
- Additional contributions
- Contribution frequency
The calculator then uses those variables to estimate the future value of the savings.
The exact features vary between calculators. Some are designed for simple lump-sum calculations, while others allow regular deposits and more detailed assumptions.
For a broader look at financial calculators and the problems they can help solve, see the Complete Guide to Financial Tools and Calculators.
Start With the Initial Savings Amount
The first number to enter is usually the amount you already have available to save.
This could be:
- $500
- $1,000
- $5,000
- $10,000
- Or another starting balance
The initial amount matters because interest begins accumulating on that money.
A larger starting balance can produce more interest in absolute terms when the interest rate and time period remain the same. However, someone starting with a smaller amount can still build substantial savings by contributing regularly and allowing enough time for growth.
Enter the Interest Rate Carefully
The interest rate is one of the most important inputs in the calculation.
For example, you might compare an account earning 3%, 4%, or 5% annually. Even seemingly small differences can become more significant over longer periods because the additional interest can itself earn interest.
When using a calculator, make sure you understand whether the stated rate is an annual interest rate, annual percentage yield, or another measure.
Savings products can use different terminology, and the rate shown by a financial institution may already account for compounding.
Choose the Compounding Frequency
Compounding frequency describes how often interest is added to the account balance.
Depending on the financial product, interest may compound:
- Annually
- Semiannually
- Quarterly
- Monthly
- Daily
More frequent compounding can affect the final result when other variables remain constant.
However, compounding frequency should not be considered in isolation. The stated interest rate, fees, account conditions, and other terms also matter when comparing savings products.
Enter the Time Period
Time is one of the most important variables in compound growth.
A calculator might ask you to enter the number of years you expect to leave the money invested or saved.
For example, you could compare:
- 1 year
- 5 years
- 10 years
- 20 years
- 30 years
The longer the money remains in an account and continues earning interest, the more opportunity there is for accumulated interest to contribute to future growth.
This is one reason starting early can matter even when the initial amount is relatively modest.
Add Regular Contributions
Many people do not make one deposit and leave it untouched. They add money to their savings regularly.
A more detailed compound interest calculator may allow you to enter a recurring contribution, such as:
- $50 per month
- $100 per month
- $250 per month
- $500 per month
Regular contributions can have a substantial impact on the final balance because each new deposit gets its own opportunity to earn interest.
When comparing scenarios, it can be useful to look at both the amount contributed and the amount generated through interest.
Understand the Difference Between Contributions and Interest
One of the most useful features of a compound interest calculator is that it can separate the money you contribute from the growth generated by interest.
Suppose you eventually accumulate $50,000 in an account.
That does not necessarily mean you personally deposited $50,000. Part of the final balance may have come from accumulated interest.
A calculator can help show the relationship between:
Starting balance + additional contributions + earned interest = estimated future balance
Seeing these components separately can make the long-term effect of saving easier to understand.
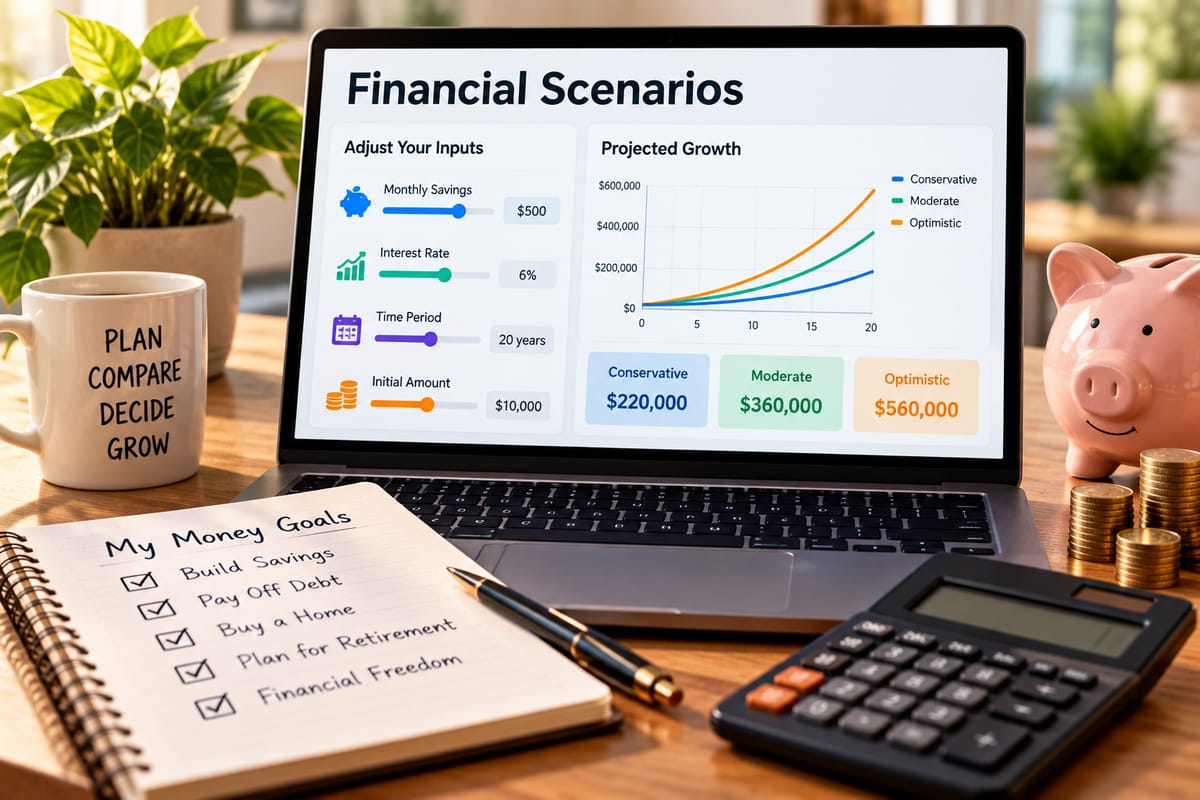
Try Different Savings Scenarios
Do not use a compound interest calculator only once.
One of its biggest advantages is the ability to compare scenarios.
For example, you could calculate what happens if you:
- Save $100 per month for 10 years.
- Save $150 per month for 10 years.
- Save $100 per month for 15 years.
- Start with a larger initial deposit.
- Use a different interest rate.
Comparing these scenarios can reveal which variables have the largest effect on the projected balance.
This can be particularly useful when setting realistic savings goals.
See Why Time Matters
Consider two hypothetical savers who use the same interest rate and make similar contributions.
One begins saving at age 25 and continues for several decades. Another begins at age 40 and saves a larger amount each month.
The earlier saver has more time for accumulated interest to remain in the account and generate additional growth.
This does not mean starting later makes saving ineffective. It simply demonstrates why time is a powerful component of compound growth.
A calculator makes this relationship easier to visualize by allowing you to change the number of years while keeping other assumptions constant.
Compare Higher Contributions With Higher Interest Rates
A compound interest calculator can also help compare different ways of increasing savings growth.
One scenario might involve keeping the interest rate unchanged while increasing monthly contributions. Another might involve keeping contributions the same while using an account with a higher rate.
These comparisons can help identify the practical trade-offs between saving more and seeking a different return.
The calculations should be treated as illustrations rather than guarantees because actual savings returns can vary depending on the financial product and its terms.
Use Realistic Assumptions
A calculator is only as useful as the assumptions entered into it.
If you enter an unusually high interest rate that is unlikely to remain available for the entire period, the projected balance may give an unrealistic impression of future savings.
Similarly, assuming that you will contribute the same amount every month for decades may not reflect how your income or expenses actually change.
When building a projection, consider using conservative, realistic assumptions and then testing several scenarios.
For example, you could calculate a lower-return scenario, a middle scenario, and a higher-return scenario.
Account for Fees and Taxes
Some compound interest calculators provide a simplified projection that does not account for account fees or taxes.
Fees can reduce the amount of money that remains available to compound. Over long periods, even relatively small recurring fees can affect the final balance.
Taxes can also affect the amount of interest or investment income that ultimately remains available for future growth, depending on the type of account and applicable tax rules.
When comparing real financial products, check the account’s actual terms rather than relying exclusively on a calculator’s headline projection.
Understand the Difference Between Savings and Investment Projections
A savings calculator typically assumes a specified interest rate or return.
Investment accounts are different because returns can fluctuate, and historical performance does not guarantee future results.
A compound growth calculation can still be useful for illustrating how money could grow under a particular assumed rate, but the result should not be interpreted as a guaranteed investment outcome.
For short-term emergency savings and other cash needs, factors such as accessibility, account safety, and liquidity may be more important than simply maximizing projected growth.
Connect Compound Growth to Emergency Savings
Long-term savings growth should not come at the expense of having accessible money for unexpected expenses.
An emergency fund can help cover events such as unexpected repairs, medical expenses, temporary income disruptions, or urgent household costs.
The appropriate amount depends on circumstances such as household expenses, income stability, debt obligations, and available financial resources. The How Much Emergency Savings Should Families Have guide explores the factors that can influence an emergency savings target.
A compound interest calculator can help estimate growth, but it should be used alongside a broader financial plan that accounts for short-term needs.
Use a Calculator as Part of a Larger Money System
A calculator is one tool rather than a complete financial strategy.
You might use one calculator to project savings growth, another to estimate debt payments, and another to evaluate a household budget.
Bringing these tools together can make it easier to understand how individual financial decisions interact.
The Complete Guide to Money Management Tools covers the broader role that budgeting, tracking, planning, and calculation tools can play in managing personal finances.
Build a Personal Collection of Financial Tools
Instead of relying on a single calculator, consider creating a small collection of tools that address different financial questions.
Your personal toolset might include:
- A compound interest calculator
- A budget calculator
- A savings goal calculator
- A debt repayment calculator
- A net worth tracker
- An expense tracking system
- An emergency fund calculator
- A retirement planning tool
The goal is not to use every available financial application. It is to have reliable tools that answer the questions most relevant to your financial situation.
The How to Build a Personal Money Toolset guide provides a broader framework for organizing these resources.
Common Mistakes When Using Compound Interest Calculators
Several mistakes can make a projection misleading.
Using the Wrong Interest Rate
Make sure the rate entered into the calculator matches the type of rate being described by the financial institution.
Forgetting Regular Contributions
If you plan to save monthly, include those contributions in the calculation. Otherwise, the projected balance may significantly underestimate your potential savings.
Ignoring Fees
A projection that assumes every dollar remains invested or saved without costs may overstate the eventual balance.
Assuming the Rate Never Changes
A savings account’s rate can change over time. A calculator using a constant rate is therefore a simplified scenario.
Treating the Result as Guaranteed
A projection is an estimate based on the assumptions entered. It is not a promise that a particular balance will be reached.
A Simple Process for Using the Calculator
For most savings projections, the process can be reduced to a few steps:
- Enter your current savings balance.
- Enter the annual interest rate or applicable return assumption.
- Select the compounding frequency.
- Enter the number of years.
- Add planned recurring contributions.
- Review the projected final balance.
- Check how much of that balance comes from your own contributions.
- Compare the result with different rates, contribution amounts, and time periods.
- Consider fees, taxes, and changing rates where relevant.
- Revisit the projection as your financial circumstances change.
This process turns the calculator from a simple number generator into a planning tool.
Turn the Projection Into a Savings Goal
Once you understand how the variables affect growth, you can work backward from a target.
Suppose you want to accumulate a specific amount within a certain number of years. Instead of simply asking how much your current savings might become, you can experiment with different monthly contribution amounts to determine what could potentially reach that target under your assumptions.
This approach can make a broad goal such as “save more money” more concrete.
You can then incorporate the required contribution into your monthly budget and review it periodically.
Review Your Calculations Over Time
Financial circumstances change.
Income can increase or decrease, expenses can shift, interest rates can change, and savings goals may evolve.
For that reason, a compound interest calculation should not necessarily be a one-time exercise.
Review your assumptions periodically and update the calculation when important circumstances change.
The most useful projection is not necessarily the one with the biggest final number. It is the one based on assumptions that reasonably reflect your financial situation and help you make informed decisions about saving.
Making Compound Growth Easier to Understand
A compound interest calculator turns an abstract financial concept into a visible projection. By adjusting the starting balance, interest rate, compounding frequency, time period, and recurring contributions, you can see how different savings strategies may affect future growth.
The biggest lesson is that compound growth depends on several variables working together. A calculator cannot predict the future with certainty, but it can help you understand the relationship between saving consistently, allowing time for growth, and keeping realistic expectations about returns.
Used alongside budgeting, emergency savings, and other money-management tools, it can become a practical part of a broader system for setting and tracking financial goals.