How Financial Scenario Tools Model Different Money Decisions
Financial decisions rarely happen in isolation. Choosing to save more can affect how quickly you reach a goal, taking on a loan can change monthly cash flow, and increasing an investment contribution can alter long-term projections.
Financial scenario tools are designed to make these relationships easier to understand. Rather than simply showing one number, they allow users to change assumptions and compare different possible outcomes.
These tools do not predict the future. Instead, they create models based on the information entered. Understanding how those models work can help people use financial calculators more effectively and recognize the difference between a useful projection and a guaranteed result.
What Are Financial Scenario Tools?
Financial scenario tools are calculators or software features that allow users to model hypothetical financial situations.
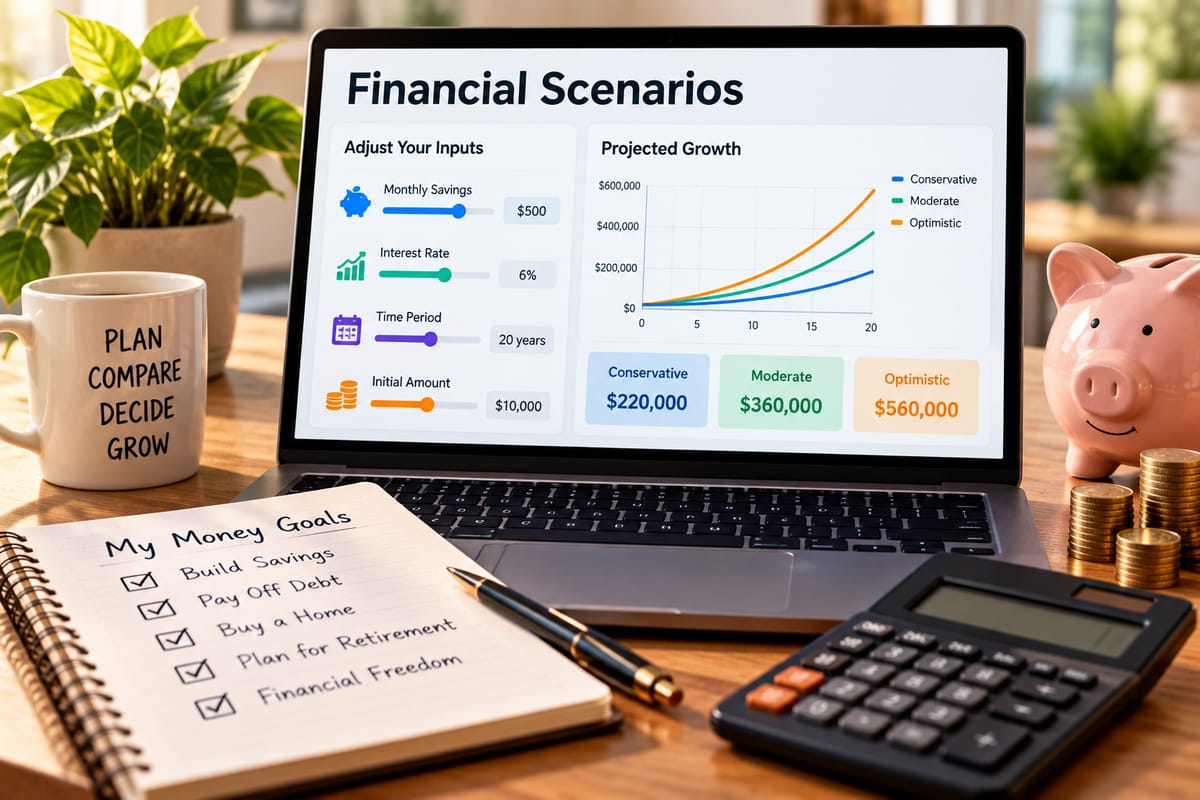
A typical tool might let you change variables such as:
- Income
- Expenses
- Savings contributions
- Interest rates
- Loan amounts
- Investment returns
- Time periods
- Inflation assumptions
- Debt payments
- Retirement contributions
The tool then calculates how those changes could affect a selected financial outcome.
For example, someone saving for a home might compare what happens if they save $300 per month versus $500 per month. Someone considering a loan might compare different borrowing amounts or repayment periods.
The purpose is not to tell users exactly what will happen. It is to make the potential consequences of different assumptions easier to see.
How Scenario Modeling Works
Most financial scenario tools follow a relatively straightforward process.
First, the user enters a starting financial position. This could include current savings, income, debt, expenses, or an existing investment balance.
Next, the user enters assumptions about what might change.
The tool applies those assumptions to a mathematical model and produces an estimated result.
The basic process can be summarized as:
Starting position + assumptions + time = projected outcome
The complexity varies considerably. A simple calculator may use only a few variables, while a sophisticated financial planning system may model dozens of interconnected factors.
Why Changing Assumptions Matters
The most useful feature of a scenario tool is often the ability to change one or more assumptions.
Suppose a household wants to determine how quickly it could build a savings fund. It could model several scenarios:
| Scenario | Monthly Saving | Time | Projected Result |
|---|---|---|---|
| A | $200 | 5 years | Estimate |
| B | $300 | 5 years | Estimate |
| C | $400 | 5 years | Estimate |
| D | $300 | 7 years | Estimate |
The exact results depend on the tool and assumptions, but the comparison makes the relationship between contribution size and time easier to understand.
This is more informative than looking at one calculation in isolation.
Financial Tools Can Model Trade-Offs
Many financial decisions involve trade-offs rather than obvious right or wrong answers.
For example, putting more money toward debt may reduce interest costs but leave less money available for short-term savings.
Increasing monthly savings may accelerate progress toward a goal but reduce the amount available for discretionary spending.
A scenario tool can model both sides of a decision by changing relevant inputs.
This helps users ask more useful questions, such as:
- What happens if I increase my monthly payment?
- What happens if I delay the purchase?
- What happens if my income changes?
- What happens if expenses increase?
- What happens if I save for longer?
- What happens if the interest rate changes?
Savings Scenario Modeling
Savings calculators are among the simplest examples of financial scenario tools.
A savings model may consider:
- Starting balance
- Regular contributions
- Interest rate
- Compounding frequency
- Time period
Users can then compare different saving strategies.
For example, someone saving for a major purchase might model the difference between making a larger initial deposit and making smaller recurring contributions.
A scenario tool can also illustrate the importance of time. Extending the savings period may allow additional contributions and interest to accumulate.
Modeling Emergency Savings
Emergency savings present another useful scenario.
Instead of simply choosing an arbitrary savings target, a household can examine its essential monthly expenses and determine how different emergency-fund sizes might compare.
For example, scenarios could represent three months, six months, or another period of essential expenses.
The model can then be adjusted if income, household size, or monthly expenses change.
The purpose is not to produce one universally appropriate emergency-fund number. It is to help users understand how their target changes when their circumstances change.
Debt and Loan Scenarios
Loan calculators can model the financial effects of borrowing.
Inputs may include:
- Principal amount
- Interest rate
- Loan term
- Payment frequency
- Fees
- Down payment
- Additional payments
Changing the loan term can demonstrate an important trade-off. A longer repayment period may reduce the scheduled payment while potentially increasing the total interest paid.
A shorter term can produce higher scheduled payments but may reduce the amount of interest paid over the life of the loan.
The Complete Guide to Loan Calculators provides a broader explanation of how these tools can be used to examine borrowing scenarios.
Modeling Different Interest Rates
Interest rates can have a substantial effect on certain financial decisions.
A scenario tool can show how changing an assumed rate affects:
- Loan payments
- Total borrowing costs
- Savings growth
- Investment projections
- Credit costs
This is particularly useful when a financial decision extends over many years.
However, users should distinguish between a rate that is contractually fixed and an assumption that may change over time.
A calculator can model a selected rate, but it cannot guarantee that a variable rate will remain unchanged.
Investment Scenario Modeling
Investment scenario tools can illustrate how different contribution amounts, time periods, and assumed returns could affect a portfolio.
For example, a user might compare:
- Investing $200 per month
- Investing $300 per month
- Investing $500 per month
The tool may then show projected balances under a particular return assumption.
These projections should be interpreted carefully. Investment returns are uncertain, and actual results can differ substantially from a constant assumed rate.
A scenario model is therefore best understood as an illustration of how variables interact rather than a prediction of future investment performance.
Retirement Scenario Modeling
Retirement planning often requires multiple assumptions.
A retirement scenario tool might incorporate:
- Current savings
- Annual contributions
- Expected retirement age
- Investment return assumptions
- Inflation
- Estimated retirement spending
- Other sources of income
- Expected length of retirement
Changing one assumption can affect the entire projection.
For example, retiring earlier reduces the number of years available for additional contributions while potentially increasing the number of years that savings need to support spending.
Scenario modeling makes these relationships easier to explore.
Budget Scenario Modeling
Financial scenario tools can also be used for everyday household budgeting.
Suppose a household wants to determine whether it can afford a new recurring expense.
A budget model can compare current income and expenses with a version that includes the proposed payment.
The household could then create alternative scenarios:
Current budget → proposed expense → reduced discretionary spending → increased income
This can help reveal whether a new expense is manageable without relying solely on intuition.
What-If Analysis Makes Tools More Useful
One of the most practical features of scenario modeling is what-if analysis.
A user can create a baseline scenario and then change one variable at a time.
For example:
Baseline: Save $300 per month.
Scenario 1: Save $400 per month.
Scenario 2: Save $500 per month.
Scenario 3: Keep saving $300 but extend the goal by two years.
This makes it easier to see which changes have the largest effect.
It can also prevent users from assuming that every financial variable has the same importance.
Sensitivity Analysis
Some financial tools go further by showing how sensitive an outcome is to changes in assumptions.
Suppose a retirement projection depends heavily on an assumed investment return. Testing several possible return assumptions can show how much the final projection changes.
Likewise, a debt model can test different interest rates or repayment periods.
Sensitivity analysis is useful because financial assumptions are rarely certain.
Instead of asking, “What will happen?” users can ask:
“How much does the outcome change if this assumption is different?”
That is often a more useful question.
Scenario Tools Can Model Income Changes
Income is another variable that can significantly affect financial decisions.
A household might model:
- Current income
- A potential raise
- Reduced working hours
- A career change
- Temporary unemployment
- Additional freelance income
The model can then show how the change could affect savings, expenses, debt payments, or other goals.
Income scenarios can be particularly useful when planning for expenses that extend over several years.
Modeling Expense Changes
Expenses can change just as significantly as income.
A household might anticipate:
- Higher rent
- Mortgage payments
- Childcare costs
- Tuition
- Insurance increases
- Transportation expenses
- Healthcare costs
- Retirement spending
Scenario modeling allows users to incorporate these changes before they occur.
Rather than asking whether the current budget works today, users can ask whether it remains workable under different future conditions.
Financial Dashboards Add Context
A scenario calculator may answer one specific question, while a financial dashboard can bring multiple pieces of information together.
A personal financial dashboard might display:
- Account balances
- Income
- Expenses
- Savings
- Debt
- Investments
- Net worth
- Progress toward goals
The What a Personal Financial Dashboard Does guide explores how these dashboards can organize financial information in one place.
Combining a current financial snapshot with scenario tools can make projections easier to interpret.
Combining Several Financial Tools
No single calculator needs to answer every financial question.
A person might use:
- A budgeting tool to understand monthly cash flow.
- A savings calculator to model progress toward a goal.
- A loan calculator to compare borrowing options.
- An investment calculator to illustrate long-term scenarios.
- A financial dashboard to monitor the overall picture.
These tools can complement one another.
The Complete Guide to Financial Tools and Calculators provides a broader overview of the different types of financial calculations people can use.
Building a Personal Money Toolset
The most useful financial tools are usually those that answer questions you actually have.
Someone managing household expenses may prioritize budgeting and cash-flow tools. Someone preparing to buy a home may focus on mortgage and affordability calculators. Someone approaching retirement may be more interested in long-term savings and income projections.
Building a personal collection of relevant tools can make financial planning more organized.
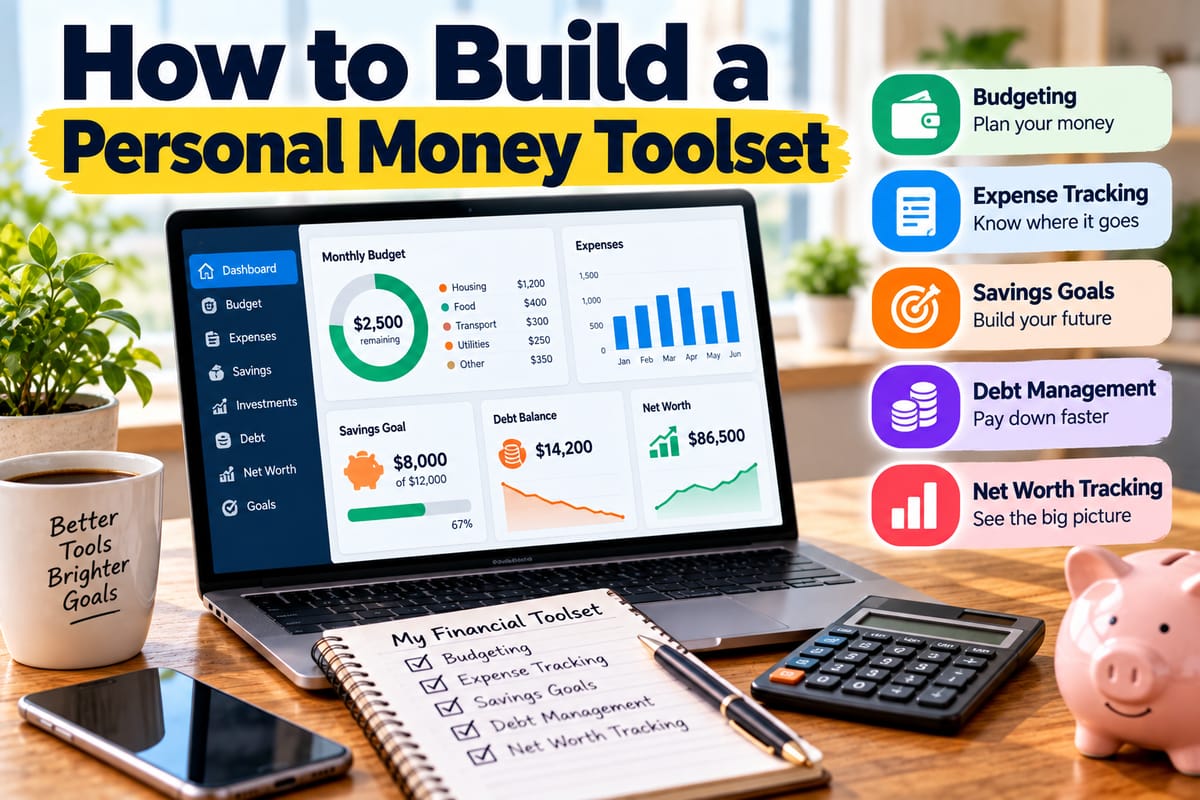
The How to Build a Personal Money Toolset guide explains how different financial tools can be combined into a practical system.
Scenario Models Are Not Predictions
One of the most important limitations of financial scenario tools is that they depend on assumptions.
If the assumptions change, the result changes.
A calculator may assume a particular interest rate, income level, inflation rate, investment return, or monthly contribution. Real life may not follow those assumptions.
For this reason, a projected result should not be interpreted as a guaranteed outcome.
Instead, treat it as an estimate under a particular set of conditions.
Garbage In, Garbage Out
Financial models follow a basic principle: poor inputs can produce poor outputs.
If expenses are underestimated, income is overstated, or an unrealistic return assumption is used, the resulting projection may create a misleading sense of confidence.
Before trusting a scenario, review the assumptions carefully.
Ask:
- Are the numbers realistic?
- Are important expenses missing?
- Is the interest rate appropriate?
- Could the income change?
- Could the time period change?
- Are fees included?
- Are taxes relevant?
- Does the model account for uncertainty?
The quality of the output depends heavily on the quality of the inputs.
Use Multiple Scenarios Instead of One
Rather than building one optimistic projection, consider creating several scenarios.
Conservative Scenario
Use relatively cautious assumptions.
Baseline Scenario
Use assumptions that appear reasonably realistic based on current circumstances.
Higher-Growth Scenario
Use more favorable assumptions to illustrate what could happen if conditions improve.
This approach creates a range of possible outcomes instead of encouraging users to focus on a single number.
Compare Decisions Using the Same Time Horizon
Scenario comparisons become more meaningful when they use comparable time periods.
For example, comparing a five-year savings plan with a ten-year plan may be useful if the goal is to understand the effect of time, but the difference should be recognized when interpreting the results.
Likewise, when comparing loans, users should consider both monthly payments and total costs over the relevant repayment period.
A consistent framework makes comparisons easier to understand.
Watch for Double-Counting
Complex financial models can sometimes include overlapping assumptions.
For example, a user might manually increase savings contributions while also entering a projected income increase that already assumes those additional savings.
Similarly, an expense reduction might be counted both as a lower expense and as additional available income.
Reviewing the model carefully can help prevent these errors.
Update Scenarios When Circumstances Change
A financial scenario created today may become less useful months or years later.
Income can change. Interest rates can move. Expenses can increase. Savings balances can grow.
Updating the model periodically helps keep the assumptions relevant.
This does not mean constantly recalculating every financial decision. Major changes in income, debt, savings goals, or household expenses are reasonable occasions to revisit important scenarios.
Use Scenario Tools Before Major Decisions
Scenario modeling can be particularly useful before making decisions with long-term financial consequences.
Examples include:
- Taking out a mortgage
- Buying a vehicle
- Changing jobs
- Increasing retirement contributions
- Taking on additional debt
- Starting a business
- Moving to a more expensive home
- Increasing recurring household expenses
The model can help identify potential consequences before the decision becomes difficult to reverse.
Ask Better Questions With Financial Models
The real value of a financial scenario tool is not the number displayed at the end.
It is the ability to explore relationships.
Instead of asking only:
“Can I afford this?”
a user can ask:
- What happens if my income falls?
- What happens if expenses rise?
- What happens if I delay the purchase?
- What happens if I increase my savings?
- What happens if the interest rate changes?
- What happens if I pay the debt faster?
- What happens if my goal takes longer than expected?
These questions can produce a much more complete understanding of a financial decision.
Turning Scenarios Into Practical Decisions
Financial scenario tools are most useful when they connect calculations to real choices.
A calculator might reveal that increasing a monthly contribution could accelerate a savings goal. The next step is determining whether the household budget can accommodate that contribution.
A loan model might show that a shorter repayment period reduces total interest. The next question is whether the higher monthly payment is sustainable.
A retirement projection might show that delaying retirement changes the outcome. The practical question is whether working longer is realistic or desirable.
The model provides information. The person still has to decide what trade-offs make sense.
A Practical Process for Scenario Modeling
A simple process can make financial scenario tools easier to use:
- Define the financial decision.
- Gather current and relevant numbers.
- Identify the variables that could change.
- Build a baseline scenario.
- Create alternative scenarios.
- Compare the results.
- Test less favorable assumptions.
- Review fees, taxes, and other omitted costs.
- Decide which assumptions are realistic.
- Revisit the model when important circumstances change.
This approach keeps the tool focused on a specific decision rather than turning it into an exercise in generating endless hypothetical numbers.
Use Models to Understand Trade-Offs
Financial scenario tools are valuable because they make complicated relationships easier to see.
They can show how saving more affects a goal, how borrowing terms affect repayment costs, how expenses influence cash flow, and how changes in assumptions can alter long-term projections.
The most useful way to approach these tools is as decision-support systems rather than fortune-telling devices. Their calculations are based on assumptions, and those assumptions can change.
When used carefully, scenario modeling can turn vague financial questions into concrete comparisons. Instead of simply asking whether a decision appears affordable or worthwhile, users can examine several possible paths and understand the trade-offs behind each one.