How Credit Scores Are Calculated
Credit scores are numbers designed to summarize information from a person’s credit history and help lenders assess credit risk. They can influence decisions involving credit cards, loans and other forms of borrowing.
Although credit scores are often presented as if they were simple financial grades, the calculation behind them can involve multiple pieces of information. Different scoring systems also use different formulas, meaning there is no single universal method for calculating every credit score.
Understanding the main factors that influence credit scores can make credit reports easier to interpret and help borrowers understand how financial behavior may affect their credit profile.
What Is a Credit Score?
A credit score is a numerical representation derived from information in a person’s credit history.
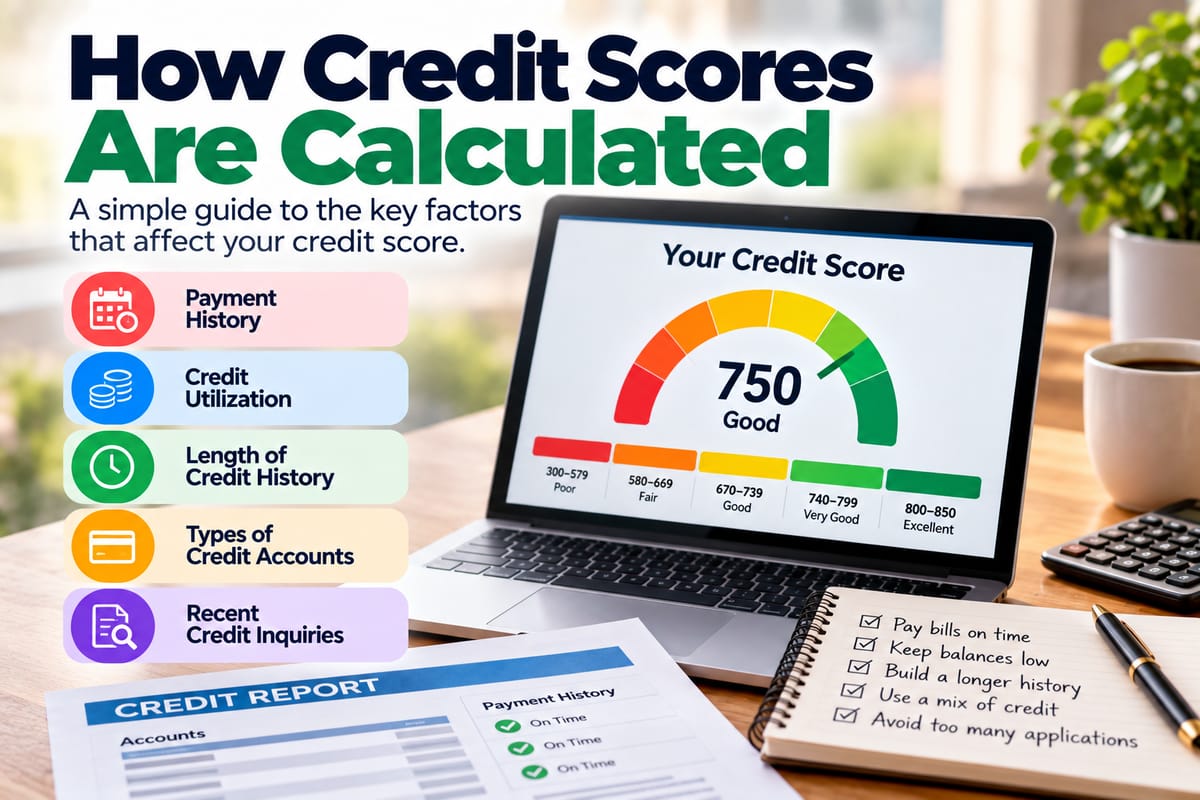
Credit scoring models generally analyze information such as:
- Payment history
- Outstanding balances
- Credit utilization
- Length of credit history
- Types of credit accounts
- Recent credit applications
- Other information relevant to the particular scoring model
The resulting number is intended to help lenders estimate the likelihood that a borrower will repay credit according to its terms.
A credit score is therefore different from a credit report.
A credit report contains information about a person’s credit accounts and history, while a credit score is calculated using information from a credit report and, depending on the scoring system, potentially other data.
For a broader explanation, see the Complete Guide to Credit Scores and Credit Reports.
There Is No Single Credit Score
One of the most important things to understand is that a person does not necessarily have one permanent credit score.
Different scoring models can produce different numbers from the same underlying credit information.
Scores can vary because of:
- Different scoring formulas
- Different credit-reporting agencies
- Different reporting dates
- Different types of credit scores
- Different information available to a scoring model
- Different lender requirements
For this reason, seeing different scores from different services does not automatically mean that one of them is incorrect.
How Credit Scoring Models Work
A scoring model takes information available about a borrower’s credit behavior and processes it according to a mathematical formula.
The model may consider patterns such as:
Has the borrower paid previous debts on time?
How much revolving credit is currently being used?
How long have the person’s credit accounts existed?
How many recent applications for credit have been made?
What types of credit accounts does the person have?
The model then generates a score within the range used by that particular system.
The exact formula is generally proprietary, so consumers typically know the broad categories that matter without knowing every mathematical calculation used to produce an individual score.
Payment History
Payment history is one of the most important categories in many widely used credit-scoring models.
It reflects whether borrowers have made required payments according to the terms of their credit accounts.
A credit history can contain information about:
- On-time payments
- Late payments
- Missed payments
- Accounts sent to collection
- Defaults or other serious delinquencies, depending on the reporting system
Consistently making payments on time can support a stronger credit history.
Late or missed payments can have a negative effect, particularly when they are recent or serious.
The exact impact depends on the scoring model and the information in the credit record.
Why Recent Payment Behavior Matters
Credit scoring models may consider the timing of payment problems.
A recent missed payment can provide different information from an isolated late payment that occurred many years ago.
The severity of the problem can also matter.
For example, a minor delay may be treated differently from a substantially overdue account.
This is one reason why credit scores can change over time even when a person’s overall financial situation appears relatively stable.
Credit Utilization
Credit utilization generally refers to how much revolving credit a borrower is using compared with the available credit limits.
For example, suppose a credit card has a limit of $10,000 and the balance is $2,000.
The balance represents 20% of the available limit.
If the balance rises to $8,000 while the limit remains $10,000, the utilization ratio becomes 80%.
Credit utilization can be considered for individual revolving accounts and across multiple revolving accounts, depending on the scoring model.
Why Credit Utilization Matters
A high revolving balance relative to available credit can indicate that a borrower is relying heavily on available credit.
Credit scoring models can therefore take utilization into account.
However, utilization is not the same as payment history.
Someone can have a high credit limit and make every payment on time, while another person can have a low balance but a history of missed payments.
Credit scoring models consider multiple factors rather than relying on one number or behavior.
Length of Credit History
The age of a person’s credit accounts can also influence some scoring models.
This can include factors such as:
- How long credit accounts have existed
- The age of the oldest account
- The age of newer accounts
- How long specific accounts have been active
A longer credit history can provide more information about how a person has managed credit over time.
Someone who has only recently entered the credit system may have less historical information available to a scoring model.
Why Closing an Old Account Can Matter
Closing a credit account does not necessarily cause an immediate or automatic score reduction.
However, closing an account can affect parts of a person’s credit profile, depending on the account and scoring model.
For revolving credit, closing an account can reduce the total amount of available credit. If existing balances remain unchanged, that can increase the overall utilization ratio.
The effect can vary depending on the person’s complete credit profile.
This is why closing an account should not be viewed as either automatically beneficial or automatically harmful.
Types of Credit Accounts
Credit scoring models may also consider the types of accounts appearing in a person’s credit history.
Examples can include:
- Credit cards
- Personal loans
- Auto loans
- Mortgages
- Other installment accounts
Having different types of credit can provide information about how a borrower has managed different forms of debt.
However, deliberately taking on debt simply to create a particular mix of accounts is generally unnecessary. Borrowing should be based on genuine financial needs and affordability rather than an attempt to manufacture a particular credit profile.
Recent Credit Applications
Applying for several new credit accounts within a short period can affect some credit scores.
Applications can generate inquiries or other records associated with requests for new credit.
A pattern of numerous applications may indicate that a person is seeking additional borrowing.
The treatment of credit inquiries varies by scoring model and type of inquiry.
Some models may distinguish between inquiries associated with different types of lending, and certain inquiries may have little or no effect on a score.
Hard and Soft Credit Inquiries
Credit inquiries are commonly described as either hard or soft inquiries.
Hard Inquiry
A hard inquiry can occur when a lender reviews a person’s credit information as part of a credit application.
Depending on the scoring model, hard inquiries can have an effect on credit scores.
Soft Inquiry
A soft inquiry can occur in situations such as checking one’s own credit information or when a company reviews information for certain purposes that do not involve a new credit application.
Soft inquiries generally do not affect credit scores in the same way hard inquiries can.
The exact treatment depends on the credit-reporting and scoring system involved.
New Credit Accounts
Opening new credit accounts can affect several parts of a credit profile simultaneously.
A new account can:
- Reduce the average age of accounts
- Create a new inquiry
- Increase available credit
- Add a new balance
- Change the overall credit mix
These effects can work in different directions.
For example, a new credit card could increase total available revolving credit, but opening several new accounts within a short period could also result in multiple applications and newer account ages.
The overall effect depends on the person’s existing credit history and the scoring model.
Credit Reports Provide the Underlying Information
Credit scores depend heavily on the information available to the scoring system.
A credit report may contain information about:
- Credit accounts
- Account balances
- Payment history
- Account opening dates
- Credit limits
- Collections
- Public records where applicable
- Credit inquiries
If information on the report is inaccurate, that could affect a score calculated using that information.
This makes reviewing credit reports an important part of managing credit health.
Why Credit Scores Change
Credit scores can change even when a borrower has not opened a new account or missed a payment.
For example, a credit card balance may change from month to month.
If the balance reported to a credit bureau changes, the utilization information used by a scoring model may also change.
Other factors can change as well, including:
- Account ages
- Newly reported payments
- Newly reported balances
- New inquiries
- Account status
- Information added or removed from a credit report
A score is therefore better understood as a current calculation based on available information rather than a permanent personal rating.
The Importance of Reported Balances
Credit card users sometimes assume that their score reflects the balance they personally see at every moment.
In reality, the information available to a scoring model depends on when lenders and other data providers report information.
A person could pay a credit card balance in full every month and still have a balance appear on a credit report if the lender reports the account before the payment is processed.
This is one reason a credit score can sometimes differ from what a borrower expects based solely on their current account balance.
How Credit Monitoring Tools Can Help
Credit monitoring services can help consumers track changes in their credit information and identify potential issues.
Depending on the service, monitoring tools may provide:
- Credit-score updates
- Credit-report information
- Account-change alerts
- New-inquiry notifications
- Identity-related alerts
- Explanations of factors affecting a score
For a broader look at these services, see How Credit Monitoring Tools Track and Explain Credit Health.
Monitoring tools are useful for awareness, but they do not replace careful review of the underlying credit report.
Why Different Services May Show Different Scores
Consumers sometimes become concerned when one service shows a different credit score from another.
This can happen for legitimate reasons.
Different services may use:
- Different scoring models
- Different credit bureaus
- Different reporting dates
- Different versions of a scoring model
- Different data sources
For example, one score may have been calculated using information that was updated more recently than another score.
Comparing scores therefore requires understanding what model and data source each service uses.
Credit Scores Are Not the Same as Creditworthiness
A credit score is an important part of how some lenders evaluate applications, but it is not necessarily the only factor considered.
A lender may also consider:
- Income
- Employment
- Existing debts
- Loan amount
- Collateral
- Account history
- Debt-to-income considerations
- The specific lending product
A high score does not guarantee approval, just as a lower score does not necessarily mean that every lender will reject an application.
Each lender establishes its own eligibility and underwriting criteria.
Why Income Usually Is Not Part of the Score
People sometimes assume that earning more money automatically produces a higher credit score.
Credit scoring models primarily evaluate credit-related information rather than simply ranking people according to income.
Income can be important to a lender’s overall decision because it helps assess repayment capacity, but it is generally distinct from the information used to calculate a traditional credit score.
Someone with a high income can have a poor credit history, while someone with a modest income can maintain a strong record of managing credit.
How Debt Affects Credit Scores
Debt itself is not automatically treated as a negative factor.
Credit scoring models can consider how debt is managed.
For revolving credit, the relationship between balances and limits can be important.
For installment loans, having an outstanding balance does not necessarily mean that a borrower is damaging their score.
Someone can have a mortgage or personal loan and maintain a healthy credit profile by making payments according to the agreement.
The important distinction is between having credit and managing credit responsibly.
The Role of Credit Age for New Borrowers
People who are new to credit may have limited information available for scoring models.
This can make it difficult for a scoring system to evaluate long-term borrowing behavior.
Building a credit history generally takes time.
New borrowers can start by using credit products responsibly, making required payments on time and avoiding unnecessary applications.
People starting from the beginning can learn more in How to Build Credit From Scratch for the First Time.
Why Consistency Matters
Credit scoring is influenced by patterns of behavior rather than a single financial decision.
Consistent payment behavior, responsible use of revolving credit and careful management of new applications can contribute to a stable credit history.
One isolated event may affect a score, but the broader credit record provides additional context.
This is why maintaining good habits over time can be more useful than trying to make sudden changes solely to increase a score.
How Credit Scores Recover After Problems
A credit score can change after negative information appears on a credit report.
Recovery is not necessarily immediate.
The process can involve:
- Bringing overdue accounts current
- Continuing to make payments on time
- Reducing excessive revolving balances
- Avoiding unnecessary new credit applications
- Checking reports for errors
- Allowing time for positive information to accumulate
The speed and extent of recovery depend on the nature of the problem and the scoring system.
There is no universal timetable that guarantees a particular score increase.
Errors Can Affect Credit Scores
Credit reports can sometimes contain inaccurate or incomplete information.
Examples might include:
- An account that does not belong to the consumer
- Incorrect payment information
- Incorrect balances
- Duplicate accounts
- Outdated information
- Incorrect personal details
Because credit scores can be calculated from reported information, errors may potentially affect the resulting score.
Consumers who identify inaccurate information should follow the appropriate dispute process provided by the relevant credit-reporting agency or data provider.
Identity Theft and Credit Scores
Unauthorized credit activity can also affect a person’s credit profile.
Someone who becomes a victim of identity theft may discover unfamiliar accounts or credit inquiries on their report.
Regularly reviewing credit information can make it easier to identify suspicious activity.
Credit monitoring alerts can also help consumers notice certain changes sooner, although monitoring services do not prevent every form of identity theft.
Credit Score Ranges
Credit scores are generally divided into ranges that help lenders and consumers interpret the numerical result.
However, the ranges differ between scoring systems and countries.
A score that is considered strong under one model may not be directly comparable with a score from another model.
Consumers should therefore focus on the scoring system being used rather than assuming that every three-digit score operates under identical ranges.
Why Credit Score Models Differ
Different scoring companies can use different mathematical models.
They may assign different levels of importance to:
- Payment history
- Utilization
- Account age
- Credit mix
- Recent applications
- Other credit information
Some models may also be designed for particular types of lending.
For example, a scoring model used in a mortgage-related context may differ from one designed for another lending product.
This is another reason why there is no single universal credit-score formula.
Credit Scoring Is Designed to Predict Risk
Credit scoring models are generally designed to help estimate the risk associated with lending.
The score does not tell a lender everything about a borrower.
Instead, it provides a standardized way to analyze selected pieces of information.
A lender may then combine the score with other information to make a credit decision.
This helps explain why the same score can produce different lending outcomes at different institutions.
How to Improve the Information Behind Your Score
Rather than focusing exclusively on a target number, consumers can focus on the underlying behaviors that contribute to a healthy credit profile.
These can include:
- Paying bills on time
- Keeping track of account balances
- Avoiding unnecessary debt
- Managing revolving credit responsibly
- Reviewing credit reports
- Limiting unnecessary credit applications
- Correcting inaccurate information
- Maintaining accounts responsibly over time
These habits can support a more stable credit history even when the exact score fluctuates.
Credit Tools Can Make Monitoring Easier
Consumers have access to a growing range of tools designed to help them understand and manage credit.
These may include:
- Credit-report services
- Credit-score trackers
- Budgeting applications
- Credit monitoring services
- Identity monitoring
- Debt calculators
- Payment reminders
These tools can provide useful information, but consumers should understand what each tool actually measures.
A score simulator, for example, may provide an estimate rather than a guaranteed future score.
A broader overview is available in the Complete Guide to Credit Tools.
Common Misunderstandings About Credit Scores
Checking Your Own Credit Always Lowers Your Score
Checking your own credit information is generally treated differently from applying for new credit.
Carrying a Balance Is Required to Build Credit
Borrowers generally do not need to carry interest-bearing balances simply to establish a credit history.
A High Income Automatically Creates a High Score
Income and credit history are different concepts.
Paying Off a Loan Always Causes a Major Score Increase
Paying off debt can change several parts of a credit profile, and the effect on a score depends on the circumstances.
There Is One Universal Credit Score
Different models and reporting sources can produce different scores.
A Score Never Changes Unless You Apply for Credit
Scores can change when balances, payment information, account ages or other reported information changes.
How to Read a Credit Score Responsibly
A credit score is most useful when viewed alongside the information that produced it.
Instead of asking only:
“What is my score?”
it can be more useful to ask:
- What information is influencing my score?
- Are my payments being reported correctly?
- How much revolving credit am I using?
- Have I recently opened several accounts?
- Are my credit reports accurate?
- Has anything changed since the last time I checked?
These questions provide more actionable information than focusing exclusively on the number.
The Bigger Picture Behind Credit Scores
Credit scores are calculated by applying scoring models to information about a person’s credit behavior and history. Factors such as payment history, revolving-credit utilization, account age, credit mix and recent credit activity can influence the result, although their treatment varies among scoring systems.
The score is only one part of the broader lending process. Credit reports provide the underlying history, while lenders may consider income, existing obligations, loan terms and other information before making a decision.
For consumers, the most useful approach is usually to focus on the financial behaviors behind the score: making payments as agreed, managing balances carefully, reviewing credit information for accuracy and using new credit deliberately.
The number can change over time, but the habits and information behind it provide the more meaningful picture of long-term credit health.