Why Children Should Learn About Money
Money affects almost every part of adult life, from paying for everyday necessities to making major purchases, saving for the future, managing debt, and preparing for unexpected expenses. Yet many people reach adulthood without having received much practical education about how money works.
Teaching children about money can help change that.
Financial education does not have to involve complicated investment concepts or detailed household budgets. Children can begin with simple ideas such as the difference between needs and wants, how saving works, why spending choices have consequences, and how people earn money.
As children grow, those lessons can become more sophisticated. They can learn about budgeting, bank accounts, financial goals, responsible borrowing, digital payments, and the relationship between money and long-term choices.
The goal is not to make children financially independent before they are ready. It is to help them gradually develop the knowledge and habits they will eventually need to manage money responsibly.
Why Money Education Matters During Childhood
Children encounter money from an early age.
They may see parents paying for groceries, notice prices in stores, receive gifts of money, hear adults discussing bills, or ask why one family can afford something while another cannot.
Even when adults do not intentionally teach financial concepts, children are already observing how money is used.
Without guidance, they may develop assumptions from advertising, social media, peers, or other sources.
Early financial education gives parents and caregivers an opportunity to explain basic concepts in an age-appropriate way.
Instead of treating money as a mysterious subject reserved for adults, families can present it as an ordinary part of everyday decision-making.
Children Learn by Watching Adults
One of the strongest ways children learn about money is by observing the people around them.
They notice whether adults:
- Compare prices
- Plan purchases
- Save money
- Talk about financial goals
- Avoid unnecessary spending
- Use credit
- Pay bills
- Give to others
- Discuss the difference between needs and wants
Children may not understand all the details, but they can recognize patterns.
This makes everyday activities useful teaching opportunities.
For example, grocery shopping can become a simple lesson about comparing prices. Planning for a family purchase can introduce the idea of saving. Preparing for a holiday can demonstrate how people plan ahead for larger expenses.
Money Lessons Can Be Age-Appropriate
Children do not need to learn everything about personal finance at once.
Financial education can develop gradually.
Young Children
Younger children can begin learning:
- What money is
- What coins and notes represent
- That goods and services cost money
- The difference between needs and wants
- Why people cannot buy everything they want
- Why saving takes time
At this stage, simple examples are usually more effective than complicated explanations.
School-Age Children
Older children can begin exploring:
- Budgeting
- Saving
- Earning
- Spending choices
- Comparing prices
- Allowances
- Financial goals
- Basic banking concepts
They can also begin making small spending decisions with appropriate parental guidance.
Teenagers
Teenagers can gradually learn more advanced concepts, such as:
- Bank accounts
- Digital payments
- Interest
- Credit
- Debt
- Taxes
- Employment income
- Financial scams
- Saving for larger goals
- Budgeting for recurring expenses
These lessons can prepare them for greater financial independence.
Teaching Children the Difference Between Needs and Wants
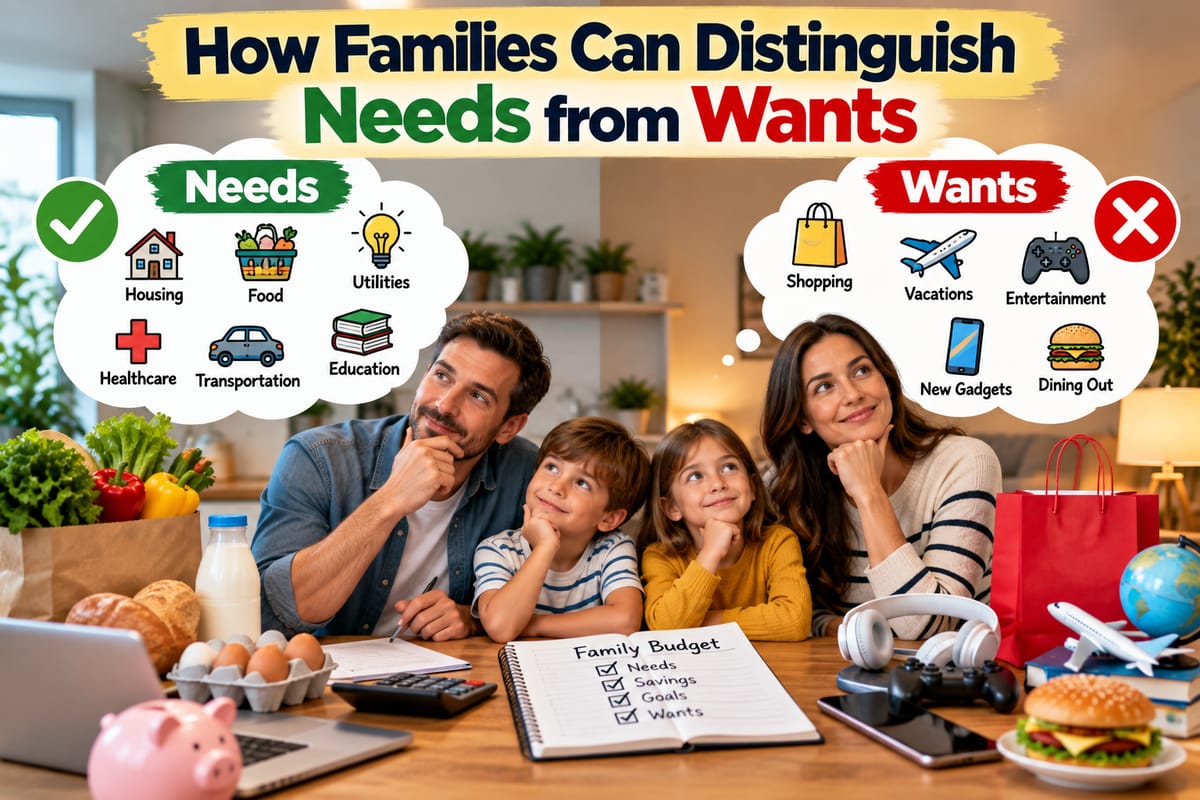
One of the most useful early money lessons is understanding the difference between a need and a want.
Needs are things required for basic well-being and everyday life, such as food, appropriate clothing, housing, and essential healthcare.
Wants are things people would like to have but can generally live without.
The distinction is not always absolute. A smartphone, for example, might be a want for one child but an important communication or educational tool in another situation.
The purpose of the lesson is not to tell children that wanting things is wrong.
Instead, it helps them understand that available money is limited and choices have consequences.
Children Need to Understand That Money Is Limited
A major financial reality is that resources are limited.
People have to make choices because they cannot spend the same money twice.
If a child has $10 and spends all of it on one item, that same $10 cannot also be used for another purchase.
This simple idea introduces the concept of opportunity cost.
A parent might explain:
“If you spend this money today, you won’t have it available for the toy you’ve been saving for.”
The child begins to understand that spending decisions involve trade-offs.
That lesson becomes increasingly important as financial decisions become larger and more complicated.
Saving Teaches Patience
Saving can be difficult because it requires someone to delay immediate enjoyment in favor of a future goal.
Children can practice this skill with relatively small amounts.
For example, a child might want a toy that costs $30 but currently has $10.
Instead of buying something smaller immediately, the child could decide to save the $10 and add more money over time.
This teaches several concepts simultaneously:
- Goal setting
- Patience
- Planning
- Delayed gratification
- Tracking progress
The amount of money is less important than the habit of connecting present choices with future goals.
Setting Financial Goals With Children
Children can learn to set simple financial goals.
A goal might involve:
- Saving for a toy
- Buying a book
- Contributing toward a gift
- Saving for an activity
- Building a small reserve
- Purchasing something they genuinely value
Parents can help children make the goal specific.
Instead of saying, “I want to save money,” a child might say:
“I want to save $25 for a bicycle accessory.”
The child can then track progress toward that target.
This introduces a basic principle used throughout adult financial planning: specific goals are easier to monitor than vague intentions.
For families looking to apply this concept more broadly, How Families Can Set, Prioritize and Achieve Household Financial Goals explores how financial goals can be organized and pursued at the household level.
Allowances Can Provide Practical Experience
An allowance can give children an opportunity to make small financial decisions with money that is actually theirs to manage.
There is no single correct allowance system.
Some families provide money regularly without requiring specific tasks. Others connect some payments to additional responsibilities. Some families combine a basic allowance with opportunities to earn additional money.
The important part is that children have an opportunity to practice managing a limited amount of money.
How Children’s Allowances Can Work provides a broader look at different ways families can structure allowances.
Should Allowances Be Tied to Chores?
Families approach this question differently.
One approach is to treat household responsibilities as something everyone contributes toward without payment, while providing an allowance separately.
Another approach is to connect additional earnings to specific tasks beyond ordinary responsibilities.
Either system can become a financial learning opportunity if children understand the reasoning behind it.
The larger lesson is that money can be connected to work, responsibility, and value.
Teaching Children How People Earn Money
Children often understand that adults go to work, but they may not fully understand the relationship between work and income.
Parents can explain that people earn money in different ways.
Examples include:
- Salaried employment
- Hourly work
- Self-employment
- Business ownership
- Freelancing
- Commissions
- Professional services
- Creative work
As children get older, conversations can also introduce the idea that income can vary depending on skills, experience, education, industry, demand, working hours, and other factors.
This can help children understand that money generally comes from economic activity rather than appearing automatically.
Teaching the Difference Between Income and Wealth
Income and wealth are not the same thing.
Income is money received, such as wages or business earnings.
Wealth generally refers to accumulated assets and financial resources after considering liabilities.
A person can have a high income without building significant wealth if they spend most of what they earn.
Similarly, someone with a more modest income can potentially accumulate assets over a long period by consistently saving and investing within their circumstances.
Children do not need a detailed lesson in wealth management at an early age, but teenagers can gradually begin understanding that earning money and building financial resources are related but different concepts.
Children Can Learn Through Everyday Shopping
Shopping creates natural opportunities to discuss money.
Parents can show children how to:
- Compare prices
- Look at quantities
- Identify promotions
- Distinguish price from value
- Make a shopping list
- Avoid unnecessary purchases
- Consider quality and durability
For example, two products might have different prices but different quantities.
A child can learn that the cheapest package is not always the lowest cost per unit.
These simple observations help develop practical financial thinking.
Advertising Can Shape Children’s Spending Habits
Children are exposed to marketing from a young age.
Advertisements can make products seem exciting, necessary, fashionable, or socially important.
Teaching children about advertising can help them become more thoughtful consumers.
Parents can ask questions such as:
- What is this advertisement trying to make you feel?
- Why does the company want you to buy this product?
- Do you actually need it?
- What information does the advertisement leave out?
- Would you still want it if you had to use your own money?
These conversations can help children distinguish between wanting something and needing something.
Teaching Children About Digital Money
Today’s children may grow up using money in forms that are very different from physical cash.
Payments can involve:
- Debit cards
- Mobile payments
- Online banking
- Digital wallets
- Contactless payments
- Online shopping
Because digital payments do not always provide a physical reminder that money is leaving an account, they can be harder for children to visualize.
Parents can explain that digital money is still real money.
A card transaction or mobile payment reduces available funds just as a cash purchase does.
This can help children understand that convenience does not remove the need for budgeting.
Introducing Budgeting to Children
Budgeting can be explained simply.
A budget is essentially a plan for how available money will be used.
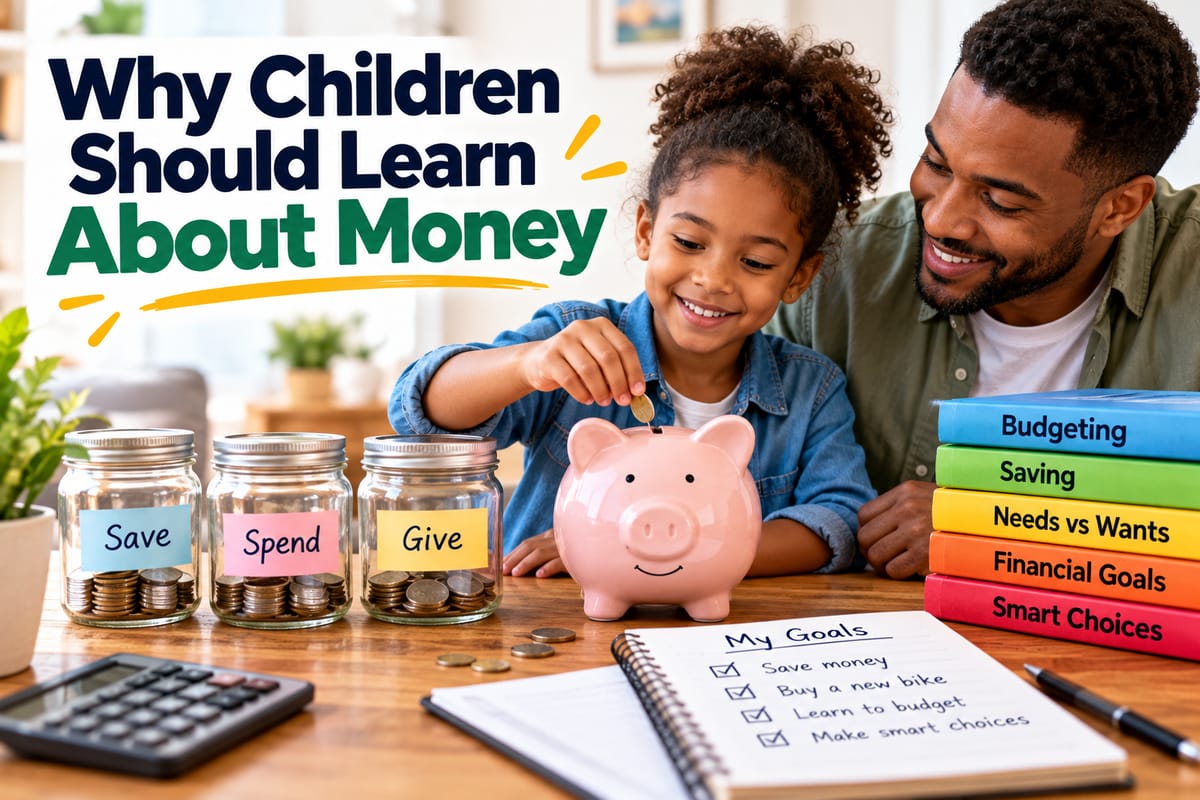
For a child, a basic budget might divide money into:
- Spending
- Saving
- Giving
For example, a child receiving $20 might decide to:
- Save $8
- Spend $10
- Give $2
The exact amounts are less important than understanding that money can be divided among different priorities.
As children become older, budgeting can include more categories.
Money Management Tools Can Support Learning
Children and teenagers can eventually learn how financial tools help people track and organize money.
Depending on their age, this might involve:
- A simple savings chart
- A spreadsheet
- A budgeting worksheet
- A bank account
- A financial tracking application
- A goal-tracking system
For adults and older teenagers, understanding financial technology can become increasingly useful. The Complete Guide to Money Management Tools provides a broader overview of tools people can use to organize financial information and manage money.
The goal should be understanding rather than simply using an application.
A tool is useful when the person understands what the information means and how it supports better decisions.
Teaching Children About Bank Accounts
Older children can gradually learn what a bank account does.
Parents can explain concepts such as:
- Deposits
- Withdrawals
- Account balances
- Transfers
- Interest
- Statements
- Account security
A savings account can provide a practical example.
A child might deposit money and periodically check how the balance changes.
As teenagers approach adulthood, parents can introduce more advanced concepts such as checking accounts, debit cards, online banking, and account security.
Interest Can Be a Powerful Lesson
Interest provides an opportunity to explain how money can grow or become more expensive depending on the situation.
When a savings account earns interest, the account holder receives additional money according to the account’s terms.
Borrowing money can work differently because the borrower may pay interest to the lender.
This creates an important distinction:
Saving can potentially earn interest.
Borrowing generally costs interest.
Teenagers can gradually learn that interest rates and time can significantly affect financial outcomes.
Teaching Children About Debt
Debt is another concept children eventually need to understand.
A simple explanation is that borrowing allows someone to use money now and repay it later, often with additional costs.
As children become teenagers, parents can explain:
- Loans
- Credit cards
- Interest
- Minimum payments
- Repayment periods
- Late fees
- Credit history
The goal is not to make children afraid of borrowing.
Instead, they should understand that borrowed money creates an obligation.
Before taking on debt, a person needs to consider whether the future repayment will fit within their financial resources.
Financial Mistakes Can Become Learning Opportunities
Children will sometimes make poor financial decisions.
A child may spend all their money immediately and later regret it.
Instead of automatically replacing the money, parents can use the situation as a learning opportunity.
Questions might include:
- What happened?
- How do you feel about the decision now?
- What would you do differently next time?
- Was there another choice you could have made?
- What did you learn?
Allowing children to experience relatively small consequences can help them develop judgment before they face much larger financial decisions as adults.
Teaching Children to Think Before Spending
A simple pause before purchasing can become a useful habit.
Parents can encourage children to ask:
- Do I need this?
- Do I really want it?
- How much does it cost?
- What else could I do with the money?
- Will I still want it later?
- Am I buying it because I actually want it or because someone influenced me?
These questions encourage thoughtful decision-making without requiring complicated financial knowledge.
Money Lessons Can Teach Responsibility
Managing money gives children opportunities to practice responsibility.
If a child has control over a small amount of money, they can experience the consequences of choices.
They may learn that:
- Saving requires consistency.
- Spending reduces available money.
- Goals require planning.
- Mistakes have consequences.
- More money does not automatically mean better decisions.
- Waiting can sometimes produce a better outcome.
These lessons can extend beyond finance into broader decision-making skills.
Teaching Children About Giving
Money education does not have to focus exclusively on earning and spending.
Families can also discuss generosity.
Children can learn that people may choose to use some of their resources to help:
- Family members
- Friends
- Charitable organizations
- Community projects
- Other people in need
Giving can be approached according to the family’s values and circumstances.
The important lesson is that money can serve purposes beyond personal consumption.
Financial Education Can Encourage Long-Term Thinking
Children naturally tend to focus on immediate experiences.
Financial education can gradually introduce longer time horizons.
A child saving for a toy is already thinking beyond the present moment.
A teenager saving for education, transportation, a computer, or another major goal is taking that concept further.
Eventually, adults need to plan for goals that may be years or decades away.
Learning to connect present decisions with future outcomes is therefore one of the most valuable skills financial education can provide.
Children Can Learn That Financial Circumstances Differ
Families have different incomes, expenses, responsibilities, opportunities, and financial pressures.
Children may notice that their friends have things their own family does not have, or vice versa.
Parents can explain that financial circumstances differ without turning the conversation into comparisons about who has more.
This can teach children that:
- Spending power differs between households.
- People have different priorities.
- Income does not tell the entire story.
- Families make different financial decisions.
- Material possessions do not necessarily represent someone’s overall financial situation.
These conversations can help children develop a more realistic understanding of money.
Teaching Children About Financial Goals
A financial goal gives money a purpose.
For a child, the goal may be relatively small.
For a teenager, it could involve saving for:
- A computer
- A bicycle
- Education
- A trip
- A driving-related expense
- A first vehicle
- Future housing
Parents can help children break larger goals into smaller steps.
For example:
Goal: Save $240.
Monthly contribution: $20.
Estimated time: 12 months.
This transforms an abstract goal into a manageable process.
Children Should Learn That Money Is a Tool
Money itself is not the final objective of every financial decision.
It is a tool people use to meet needs, pursue goals, exchange value, manage uncertainty, and make choices.
Teaching children this broader perspective can prevent financial education from becoming solely about accumulating as much money as possible.
Money can help provide:
- Food and housing
- Education
- Transportation
- Security
- Opportunities
- Experiences
- Support for others
- Long-term financial flexibility
How someone uses money depends on their circumstances, values, and goals.
How Parents Can Make Money Conversations Normal
Financial education does not need to be a formal weekly class.
Parents can introduce money concepts during everyday situations.
For example:
At the grocery store: Compare prices.
When receiving an allowance: Discuss saving and spending.
Before a family purchase: Explain planning.
When paying a bill: Explain that household services have costs.
When planning a trip: Discuss saving and budgeting.
When a child makes a purchase: Discuss the trade-off.
These small conversations can add up over many years.
What Children Should Eventually Understand
By the time a young person approaches adulthood, they should ideally have at least a basic understanding of several financial concepts.
These can include:
- How income is earned
- How spending works
- Why budgeting matters
- How to save
- How to set financial goals
- How bank accounts work
- How digital payments work
- How interest works
- How borrowing creates obligations
- Why debt needs to be managed carefully
- Why emergency savings can matter
- How financial decisions involve trade-offs
- Why financial information should be protected
- How to recognize suspicious financial offers
They do not need to master every concept immediately.
Financial knowledge develops over time.
Avoid Making Money a Source of Fear
Financial education should be realistic without making children unnecessarily anxious.
Children do not need to carry adult financial responsibilities.
Parents can explain that money requires planning while reassuring children that adults are responsible for household financial decisions.
The goal is to build confidence and understanding, not fear.
Age-appropriate conversations can help children see financial management as a practical life skill rather than a subject that is mysterious or intimidating.
Creating a Family Culture of Financial Learning
Families can make money education part of ordinary life.
That might involve:
- Setting savings goals together
- Discussing needs and wants
- Planning family purchases
- Reviewing simple budgets
- Comparing prices
- Encouraging children to track their savings
- Talking about financial mistakes without shame
- Explaining financial decisions in age-appropriate language
The approach can change as children grow.
A five-year-old and a fifteen-year-old should not receive the same financial lesson.
But both can begin developing the habit of thinking carefully about resources and choices.
Preparing Children for Financial Independence
Eventually, children become adults who must make financial decisions without their parents standing beside them.
They will need to decide how to use income, manage expenses, choose financial products, handle unexpected costs, evaluate borrowing, and pursue their own goals.
No parent can predict every financial decision a child will face.
What parents can provide is a foundation of knowledge and habits.
That foundation can make unfamiliar financial situations easier to understand and evaluate.
Turning Everyday Choices Into Financial Education
Children do not need large amounts of money to learn meaningful financial lessons.
A small allowance can teach budgeting. A savings goal can teach patience. A grocery trip can demonstrate price comparison. A conversation about advertising can encourage critical thinking. A discussion about a family purchase can show how priorities influence spending.
Over time, these ordinary experiences can build a much broader understanding of personal finance.
Teaching children about money is ultimately about preparing them to make thoughtful choices with limited resources. The lessons can start with simple concepts and become more sophisticated as children mature, giving them the knowledge, habits, and confidence they need to navigate financial decisions throughout adulthood.