**How Families Can Set, Prioritize and Achieve Household Financial Goals
Household finances often involve competing priorities. Families may want to build emergency savings, pay down debt, purchase a home, fund education, replace an aging vehicle, prepare for retirement or simply create more financial breathing room.
Trying to accomplish everything at once can make financial planning feel overwhelming. A more practical approach is to identify the household’s most important goals, establish priorities and turn those goals into manageable actions.
Financial goals become much easier to pursue when everyone understands what the family is working toward and how everyday spending decisions contribute to those objectives.
What Are Household Financial Goals?
Household financial goals are specific outcomes a family wants to achieve with its money.
They can be short-term, medium-term or long-term.
Examples include:
- Building an emergency fund
- Paying off credit card debt
- Saving for a vehicle
- Preparing for a home purchase
- Funding children’s education
- Saving for retirement
- Reducing monthly expenses
- Building investments
- Creating a larger cash reserve
- Saving for a family vacation
A financial goal becomes more useful when it is specific enough to measure.
“Save more money” is a general intention. “Save $6,000 over the next 12 months” provides a measurable target and a timeframe.
Why Families Need to Prioritize Goals
Not every financial objective has the same level of urgency.
A family facing high-interest debt may need to address that obligation before aggressively saving for a discretionary purchase. A household without accessible emergency savings may need to establish a financial cushion before taking on additional long-term commitments.
Prioritizing goals does not mean abandoning everything else. It means deciding which objectives should receive the greatest attention and resources first.
A useful priority framework considers:
- Urgency — Does the goal address an immediate financial risk?
- Importance — How significant is the goal to the family’s overall well-being?
- Time sensitivity — Does the family have a fixed deadline?
- Financial impact — What happens if the goal is delayed?
- Affordability — Can the household realistically fund it?
- Dependencies — Does achieving one goal make another easier?
Start With the Family’s Current Financial Position
Before setting ambitious goals, families need to understand where their money is currently going.
This means reviewing income, recurring expenses, variable spending, debts, savings and other financial commitments.
A household may discover that its biggest obstacle is not insufficient income but a collection of small recurring expenses that have accumulated over time.
A clear financial snapshot provides a starting point for deciding what can realistically change.
Build a Household Budget
A budget connects financial goals with everyday spending decisions.
Families can begin by listing regular sources of income and categorizing expenses such as:
- Housing
- Utilities
- Food
- Transportation
- Insurance
- Debt payments
- Childcare
- Education
- Entertainment
- Subscriptions
- Savings
- Investments
The How to Build a Family Budget guide provides a broader framework for organizing household income and expenses.
Once the budget is established, families can determine how much money is available for financial goals each month.
Separate Needs, Obligations and Wants
Not every expense should be treated equally.
Essential household costs generally need to be covered before discretionary spending. Debt obligations may also require priority because missed payments can result in fees, penalties or other financial consequences.
Discretionary expenses, meanwhile, may offer opportunities for adjustment if the family needs to create additional room for savings.
This does not mean eliminating every enjoyable expense. Sustainable financial planning usually works better when families create a realistic balance between current quality of life and future objectives.
Create a List of Financial Goals
Once the household’s current finances are understood, each family member can contribute ideas about what they want the household to accomplish.
A goal list might include:
| Goal | Target Amount | Timeframe | Priority |
|---|---|---|---|
| Emergency savings | $5,000 | 12 months | High |
| Vehicle replacement | $15,000 | 3 years | Medium |
| Home down payment | $40,000 | 5 years | High |
| Family vacation | $3,000 | 18 months | Lower |
| Retirement savings | Ongoing | Long term | High |
The exact targets will differ from household to household.
The purpose of the exercise is to make competing priorities visible.
Make Goals Specific and Measurable
A strong financial goal usually answers four basic questions:
What are we saving for?
How much do we need?
When do we need it?
How much should we set aside regularly?
For example, suppose a family wants to save $12,000 for a major purchase in two years.
Ignoring investment returns, the household would need to save approximately:
$12,000 ÷ 24 months = $500 per month
That monthly target makes the goal much easier to incorporate into a budget.
Divide Large Goals Into Smaller Milestones
Large financial targets can seem intimidating when viewed as a single number.
Breaking them into milestones makes progress easier to track.
Instead of focusing only on a $20,000 savings target, a family could establish milestones at:
- $1,000
- $5,000
- $10,000
- $15,000
- $20,000
Each milestone provides a measurable indication that the household is moving toward its larger objective.
This can also make long-term financial planning feel more manageable.
Prioritize Emergency Savings
Unexpected expenses can disrupt even a carefully designed household budget.
A vehicle repair, temporary loss of income, urgent home expense or other financial emergency can force a family to borrow money if there is insufficient cash available.
The appropriate emergency-fund size depends on factors such as household income stability, essential expenses, insurance coverage and the family’s circumstances.
Families can explore How Much Emergency Savings Should Families Have? for a broader discussion of emergency savings.
An emergency fund can also protect other financial goals by reducing the need to divert money from long-term savings when an unexpected expense occurs.
Consider High-Interest Debt
Debt can compete directly with savings goals.
High-interest balances can become particularly expensive because interest charges increase the amount required to eliminate the debt.
Families should therefore understand the interest rates, minimum payments, balances and repayment terms associated with their debts.
A household may decide to prioritize paying down expensive debt while maintaining appropriate emergency savings.
The right balance depends on the family’s financial circumstances and the terms of its obligations.
Plan for Major Purchases
Major purchases can become financial goals in their own right.
A family might be preparing to purchase:
- A home
- A vehicle
- Major appliances
- Furniture
- Educational equipment
- A family business asset
Instead of relying entirely on credit when the purchase arrives, families can estimate the future cost and save gradually.
The How Families Can Plan Financially for Major Purchases guide explores this type of planning in greater detail.
Planning ahead also gives households more time to compare options and adjust the purchase if the original target proves unrealistic.
Coordinate Financial Goals Between Partners
When two adults share financial responsibilities, disagreements can arise if each person has different priorities.
One partner might prioritize retirement savings while the other wants to save for a home or eliminate debt.
These differences do not necessarily indicate a financial problem. They can reflect different experiences, preferences and expectations.
Regular conversations can help couples understand what matters most to each person and determine which goals should be pursued together.
The Complete Guide to Couples and Money Management provides additional guidance on coordinating financial decisions within a relationship.
Give Every Goal a Place in the Budget
A financial goal is easier to pursue when it has a defined place in the household budget.
For example, a family might allocate monthly money toward:
- Emergency savings
- Retirement
- Education
- Debt repayment
- A major purchase
- Short-term family activities
Automating transfers where appropriate can make saving more consistent because the money is moved toward its intended purpose before it is accidentally spent elsewhere.
Use Separate Savings Categories
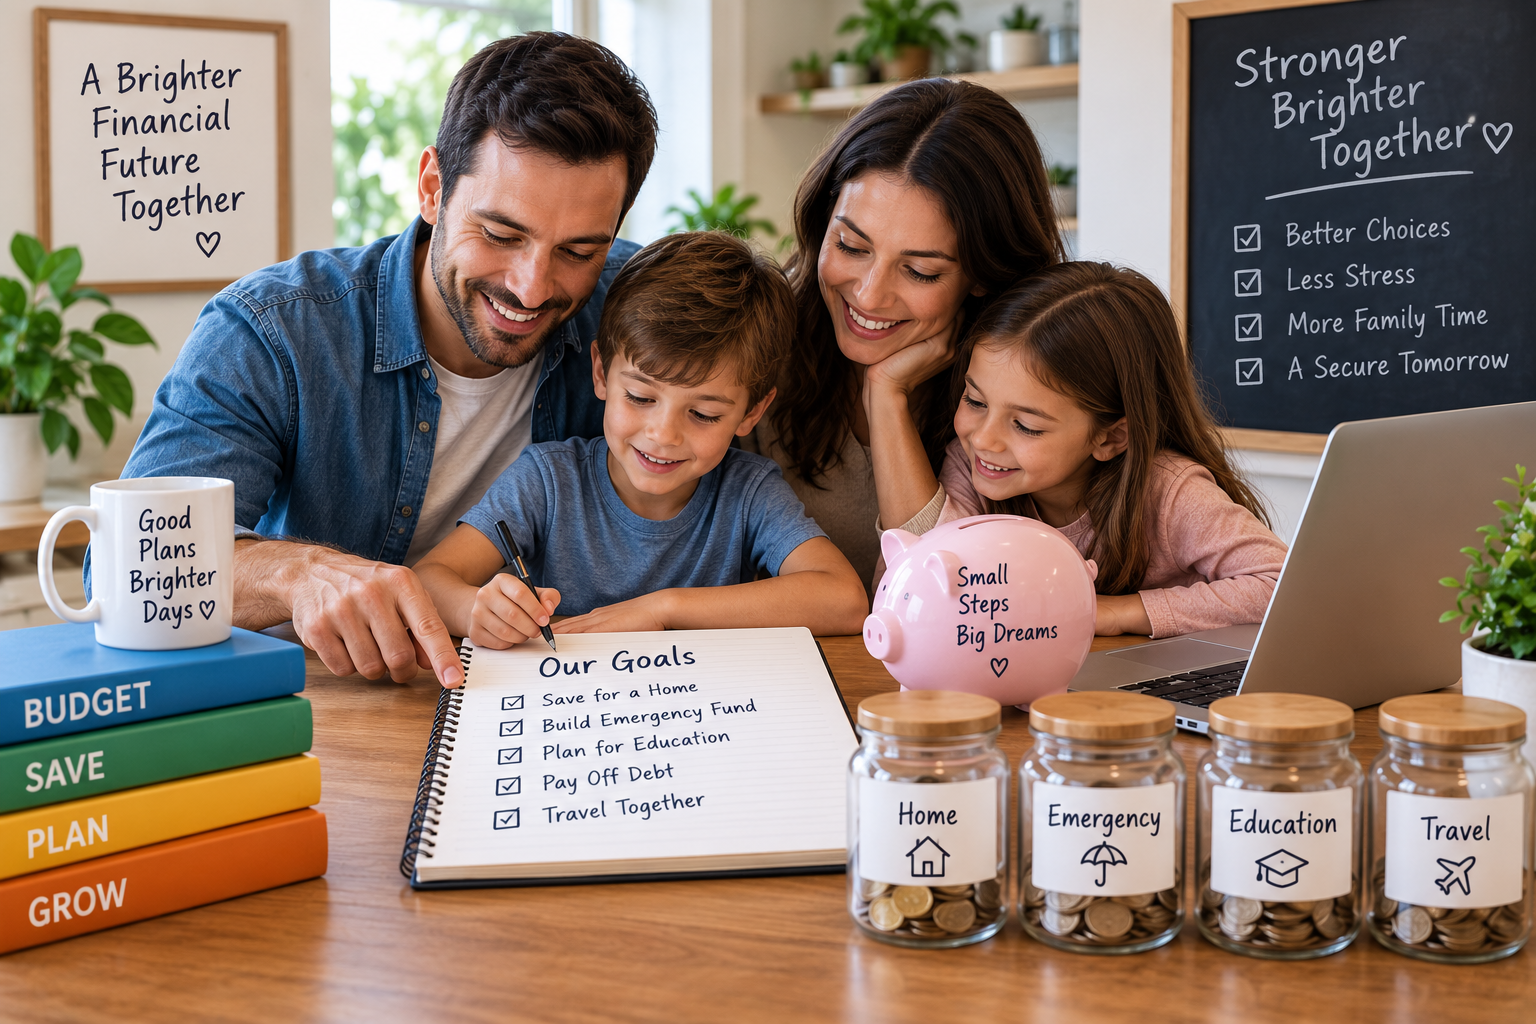
Families pursuing several goals may find it useful to separate their savings into different accounts or clearly defined categories.
For example:
Emergency fund: Unexpected expenses
Home fund: Future down payment
Education fund: School-related costs
Vehicle fund: Replacement or major repairs
Travel fund: Planned vacations
The specific account structure is less important than being able to distinguish money intended for different purposes.
This reduces the risk of treating all savings as one interchangeable pool.
Adjust Goals When Circumstances Change
Financial goals should not be treated as permanent contracts.
Income can change. A child may begin school. Housing costs may increase. A family member may change jobs. An unexpected expense may require immediate attention.
When circumstances change, the household can review its priorities and adjust its plan.
Changing a target does not necessarily mean the original plan failed. It can simply reflect new information.
Track Progress Regularly
Families do not need to monitor their finances constantly.
A monthly review can be enough for many households.
During the review, family members can ask:
- How much did we save?
- Did we stay within our budget?
- Did debt balances decrease?
- Did an unexpected expense affect our plan?
- Are our targets still realistic?
- Has anything become more urgent?
- What should we change next month?
Regular reviews turn financial planning into an ongoing household habit.
Measure Progress With Useful Numbers
Simple measurements can make progress visible.
For a savings goal, families can calculate:
Progress percentage = Amount saved ÷ Target amount × 100
If a household has saved $4,000 toward a $10,000 goal:
$4,000 ÷ $10,000 × 100 = 40%
The percentage provides a straightforward way to see how far the household has progressed.
Other useful measurements might include debt balances, monthly savings rates and the number of months of essential expenses covered by emergency savings.
Avoid Setting Too Many Priorities
A long list of financial goals can make it difficult to make meaningful progress on any of them.
Families may benefit from selecting a small number of primary goals and maintaining secondary objectives that receive smaller amounts of money.
For example, a household could prioritize:
- Building emergency savings
- Paying down expensive debt
- Saving for a major purchase
Retirement contributions and other long-term goals might continue according to the household’s existing plan while the primary objectives receive additional attention.
The exact order depends on individual circumstances.
Make the Plan Realistic
A financial plan that requires unrealistic sacrifices is difficult to maintain.
Suppose a household determines that it needs to save $1,500 each month to achieve a target but has only $800 available after essential expenses and debt payments.
Simply setting the $1,500 target does not solve the problem.
The family may instead need to extend the timeline, reduce the target, increase income, lower expenses or reconsider other financial priorities.
Realistic planning is more sustainable than relying on temporary enthusiasm.
Look for Ways to Increase Financial Capacity
Families can create additional room for financial goals in several ways.
They may review recurring subscriptions, insurance costs, transportation expenses, dining expenses or other discretionary categories.
Increasing income can also change the equation. Additional work, freelance income, business revenue or other legitimate sources of earnings may provide more capacity for savings.
The goal is not necessarily to minimize every expense. It is to create enough financial flexibility to support the household’s most important objectives.
Include Children in Age-Appropriate Conversations
Children can also learn useful financial habits through everyday household decisions.
Parents can explain concepts such as saving, spending, planning and delayed gratification in ways that match the child’s age.
For older children, families might involve them in discussions about saving for specific purchases or planning the cost of activities.
The objective is not to make children responsible for adult financial decisions. It is to help them understand that money involves choices and trade-offs.
Distinguish Short-Term and Long-Term Goals
Financial goals often operate on different timelines.
Short-Term Goals
These may include:
- Building an initial emergency fund
- Paying an upcoming bill
- Saving for a holiday
- Replacing a household appliance
Medium-Term Goals
These might include:
- Buying a vehicle
- Building a larger cash reserve
- Saving for education
- Preparing for a home purchase
Long-Term Goals
These can include:
- Retirement
- Long-term investments
- Paying off a mortgage
- Funding future education
Separating goals by timeframe helps families determine which resources should remain accessible and which may be appropriate for longer-term planning.
Protect Financial Progress
Achieving a financial goal is only part of the process.
Families also need to protect their progress from avoidable setbacks.
This can involve maintaining appropriate insurance, keeping emergency savings accessible, reviewing major recurring expenses and avoiding unnecessary high-cost debt.
Financial protection becomes especially important after a household has accumulated significant savings or assets.
Celebrate Milestones Without Derailing the Plan
Financial discipline does not require ignoring progress.
Families can acknowledge milestones in ways that fit their budget.
For example, reaching a savings target might be recognized with an inexpensive family activity rather than a large purchase that reverses months of progress.
Celebrating milestones can make long-term financial planning feel like a shared family project rather than an endless exercise in restriction.
What to Do When a Goal Falls Behind
A missed monthly target does not necessarily mean the entire financial plan has failed.
Families can examine what caused the shortfall.
Was there an unexpected expense? Did income change? Was the original savings target unrealistic? Did discretionary spending exceed the budget?
Once the cause is understood, the family can determine whether to increase future contributions, extend the timeline or adjust another part of the plan.
The key is to respond to the setback rather than abandoning the goal entirely.
Create a Household Financial Routine
A simple routine can keep financial goals visible.
For example, once a month the household could:
- Review income and expenses.
- Check savings balances.
- Review debt balances.
- Measure progress toward major goals.
- Discuss upcoming expenses.
- Adjust the next month’s budget.
- Confirm automatic savings and payments.
This does not need to become a lengthy meeting. Even a short, consistent review can help keep the household aligned.
Build Goals Around What Matters Most
Money is ultimately a tool for supporting the family’s priorities.
Different households will define financial success differently. One family may place greater emphasis on homeownership, another on flexibility and travel, while another may focus heavily on education or long-term financial security.
The important part is connecting financial goals to the things the household actually values.
When goals reflect shared priorities, it becomes easier to understand why certain spending decisions are being made.
Turning Financial Intentions Into Household Progress
Setting household financial goals is less about creating a perfect plan and more about establishing a practical system that the family can maintain.
Start with a clear picture of current finances. Identify the goals that matter most. Put them in a sensible order, assign specific amounts and deadlines, and connect those targets to the household budget.
Then review the plan regularly and adjust it as circumstances change.
With clear priorities and consistent follow-through, large financial objectives become a series of manageable decisions. Over time, those individual decisions can build emergency reserves, reduce debt, fund major purchases and move the household toward the financial future it wants to create.