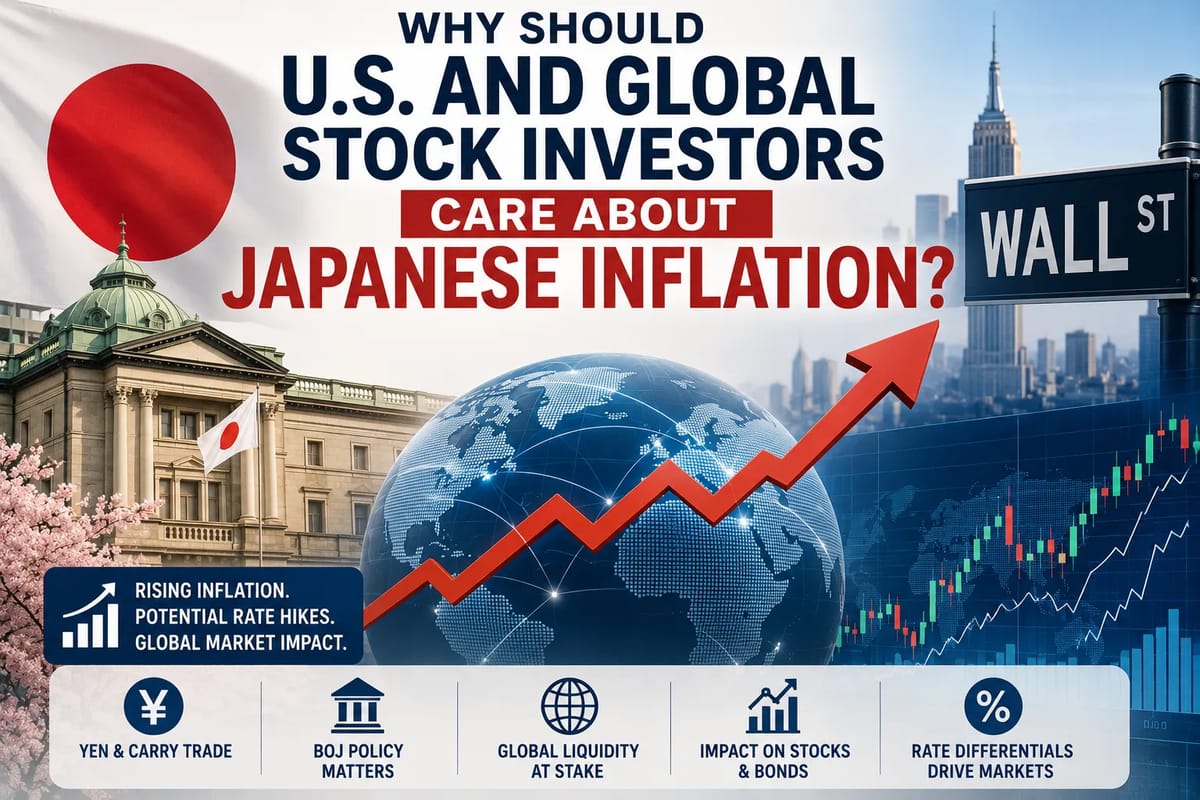
Why Should U.S. and Global Stock Investors Care About Japanese Inflation?
For investors focused on Wall Street, Europe or emerging markets, Japanese inflation can seem like a distant economic statistic.
It is not.
Japan has spent decades operating with exceptionally low interest rates, making the yen an important source of relatively cheap funding for global investors. As Japanese inflation becomes more persistent, the Bank of Japan (BOJ) has more reason to raise interest rates and reduce monetary accommodation.
That matters far beyond Tokyo.
Higher Japanese rates can influence the yen, Japanese government bonds, global bond yields and the enormous pool of capital that Japanese investors and international traders have deployed overseas. In an increasingly interconnected financial system, a change in Japan’s monetary regime can alter the conditions under which investors price everything from U.S. technology stocks to emerging-market currencies.
The issue is becoming more relevant now. The BOJ raised its policy rate to around 1% in June 2026, while recent data show continued price pressure. On August 13, Japan reported July producer-price inflation of 7.2% year over year, while Tokyo’s core consumer inflation accelerated to 1.9%. Recent developments strengthened expectations for another BOJ rate increase in September.
So why should an investor sitting in New York, London, Nairobi or Singapore care?
Because Japanese inflation can change the global price of money.
For a broader framework on how inflation, interest rates, employment, GDP and other economic indicators interact, see the Complete Guide to Economic Indicators.
Japan Is No Longer the Deflation Story Investors Once Knew
For much of the past several decades, Japan was associated with weak inflation, stagnant wages and extremely low interest rates.
That environment allowed the BOJ to maintain unusually loose monetary policy for an extended period.
The investment consequences were significant.
Japanese investors faced relatively unattractive returns on domestic bonds, while global investors could borrow yen cheaply and invest the proceeds in assets offering higher yields elsewhere.
That helped create the famous yen carry trade.
But the economic environment has changed.
The BOJ says underlying inflation has been approaching its 2% price-stability target and has indicated that it will continue adjusting monetary accommodation in response to economic and price developments.
The central question for markets is therefore no longer simply whether Japan can generate inflation.
It is whether inflation becomes persistent enough to force the BOJ to normalize rates further.
What Is the Yen Carry Trade?
The concept is relatively simple.
An investor can borrow money in a currency with a low interest rate, convert it into another currency and invest in an asset offering a higher return.
For years, the yen was one of the world’s most important funding currencies.
A simplified example:
- Borrow ¥100 million at a relatively low interest rate.
- Convert the yen into U.S. dollars.
- Buy higher-yielding bonds or other assets.
- Earn the difference between the investment return and the borrowing cost.
- Convert the proceeds back into yen later.
The strategy works particularly well when the yen remains stable or weak.
But it becomes much less attractive if Japanese interest rates rise sharply or the yen appreciates.
That is where Japanese inflation becomes important.
Inflation Can Push the BOJ Toward Higher Rates
Central banks generally do not raise interest rates simply because prices increase temporarily.
They look at whether inflation is becoming persistent and whether it is spreading through wages, services and broader price-setting behavior.
That distinction matters in Japan.
The BOJ’s April 2026 outlook projected consumer inflation excluding fresh food at 2.8% for fiscal 2026, with inflation expected to move toward roughly 2% over subsequent years. The central bank also said it would continue raising the policy rate and adjusting monetary accommodation if its economic and price outlook materializes.
Recent developments have complicated that outlook.
Japan’s July producer prices rose 7.2% from a year earlier. Higher metal prices, energy costs and strong demand related to artificial intelligence infrastructure were contributing to producer-price pressure.
If businesses continue passing higher costs to consumers and wages remain supportive, the BOJ has more justification for further rate increases.
The relationship between inflation and central-bank decisions is also important in other economies, making How Monetary Policy Affects Financial Markets useful context for investors assessing the broader policy transmission mechanism.
Higher Japanese Rates Could Strengthen the Yen
Interest rates are only one factor affecting currencies, but they matter.
If Japanese rates rise relative to U.S. and other developed-market rates, the incentive to borrow yen and invest abroad becomes smaller.
At the same time, higher Japanese yields can make yen-denominated assets more attractive.
That can create demand for the yen.
A stronger yen can then create a feedback loop for leveraged investors:
BOJ tightening → Japanese yields rise → yen strengthens → carry-trade returns deteriorate → investors reduce positions → demand for yen increases further.
This does not mean every BOJ rate increase will trigger a global sell-off.
The interest-rate gap between Japan and other major economies remains important, and investors can hedge currency exposure.
But when markets are heavily positioned for a weak yen, even a relatively modest currency move can cause significant adjustments.
Why U.S. Technology Stocks Could Be Vulnerable
The connection between Japanese monetary policy and U.S. technology stocks may seem strange.
It becomes clearer when viewed through liquidity.
Investors do not operate in isolated national markets. Capital moves between currencies, bonds, equities and other assets according to expected returns and risk.
For years, cheap yen funding has been part of the global liquidity environment.
If financing conditions change, leveraged investors may reduce exposure to riskier assets.
That could disproportionately affect parts of the market where valuations depend heavily on expectations of future earnings.
Technology and growth stocks are particularly sensitive to interest rates because a larger portion of their perceived value can come from cash flows expected far into the future.
When discount rates rise, those future cash flows become less valuable in today’s terms.
Japan therefore matters to U.S. technology investors through both liquidity and interest-rate channels.
U.S. Treasury Investors Should Pay Attention Too
Stocks are not the only asset class affected.
Japan is one of the world’s major holders of U.S. government debt, and Japanese institutional investors have historically allocated substantial capital overseas.
If Japanese government bonds become more attractive relative to foreign bonds, Japanese investors may have less reason to allocate additional money abroad.
In some circumstances, investors could also repatriate existing foreign holdings.
That does not mean Japanese investors will automatically sell U.S. Treasuries every time the BOJ raises rates.
Currency-hedging costs, relative yields, portfolio requirements, liquidity and risk considerations all matter.
But a sustained shift in Japanese yields can change the relative attractiveness of global fixed-income markets.
That is important for U.S. investors because Treasury yields influence borrowing costs across the economy, including:
- Mortgages
- Corporate bonds
- Consumer loans
- Government financing
- Equity valuations
Japan’s bond market can therefore have implications for the global bond market.
The Yen Could Matter More Than the Inflation Number
Investors should avoid focusing exclusively on Japan’s CPI or producer-price statistics.
The more important chain may be:
Inflation → BOJ policy → Japanese yields → yen → global capital flows.
This is why a seemingly modest change in Japanese inflation expectations can produce a disproportionately large reaction in financial markets.
Suppose investors previously expected the BOJ to keep rates unchanged for an extended period.
Then inflation data come in stronger than expected.
Markets may immediately reassess:
- The probability of a rate hike
- Japanese bond yields
- The yen
- Carry-trade profitability
- Japanese equities
- Global bond yields
- Risk appetite
The actual rate increase might occur months later.
Markets can begin adjusting immediately because financial assets are priced on expectations.
Japan’s Inflation Story Is Also a Currency Story
The yen has been under significant pressure in 2026.
Recent reporting put the currency near the psychologically important ¥160 per dollar level, prompting renewed attention from Japanese and U.S. authorities. The yen’s weakness has increased import-price pressure, with Japan’s yen-based import-price index up 29.1% year over year in July.
A weak yen makes imported goods and energy more expensive.
That can increase inflation.
But inflation can also encourage the BOJ to raise rates.
Higher rates can support the yen.
This creates an important policy tension:
Japan wants to prevent excessive yen weakness without tightening monetary policy so aggressively that it damages economic growth.
That balancing act is now closely watched by global investors.
What Happens If the Yen Carry Trade Unwinds?
The phrase “carry-trade unwind” sounds dramatic, but the mechanics are straightforward.
Imagine thousands of investors have borrowed yen and bought foreign assets.
Then the yen suddenly strengthens.
The value of their yen liabilities increases relative to their foreign investments.
Some investors may respond by:
- Selling foreign assets.
- Converting the proceeds into yen.
- Repaying yen borrowing.
- Reducing leverage.
If many investors do this simultaneously, the move can reinforce itself.
Foreign assets fall.
The yen rises.
More investors face pressure.
More positions are closed.
This is why currency movements can sometimes become much larger than expected.
The August 2024 Market Shock Is a Useful Reminder
Investors do not need to imagine what a sudden yen and carry-trade adjustment could look like.
The global market turmoil of August 2024 demonstrated how quickly changes in Japanese monetary expectations could spread through international markets.
The episode was not caused by Japan alone, and markets have changed since then.
But it highlighted a key principle:
Global portfolios can contain hidden exposure to Japanese monetary policy.
An investor may believe they own a diversified collection of U.S. technology stocks, bonds and emerging-market assets without realizing that some of the liquidity supporting those markets can be connected to global funding conditions involving the yen.
That is why Japanese policy deserves attention even when the investment itself is not Japanese.
Japanese Inflation Could Affect Emerging Markets
Emerging markets may be particularly sensitive to changes in global liquidity.
Countries with:
- High external debt
- Large foreign-currency liabilities
- Vulnerable currencies
- High dependence on foreign portfolio flows
can be affected when global investors reduce risk.
If a carry-trade unwind causes investors to move toward safer assets, emerging-market currencies and equities could experience pressure.
Higher global bond yields can also make emerging-market assets less attractive relative to developed-market alternatives.
For investors holding emerging-market ETFs or individual stocks, Japan therefore belongs on the macroeconomic dashboard.
Japanese Stocks Are a Different Story
Japanese inflation is not automatically bad for Japanese equities.
In fact, a controlled transition from deflation to sustainable inflation can be positive.
Companies may gain pricing power.
Nominal revenues can rise.
Wages can increase.
Consumers may become less inclined to postpone purchases.
Banks and financial companies can benefit from higher interest rates.
A stronger domestic economy can also improve corporate earnings.
The problem arises when inflation becomes too high or monetary tightening becomes too aggressive.
Then:
- Borrowing costs increase
- Consumer purchasing power can weaken
- Corporate financing becomes more expensive
- Equity valuations can fall
For investors in Japanese stocks, the question is therefore not simply:
“Is inflation rising?”
It is:
“Is inflation rising in a way that supports sustainable nominal growth, or in a way that forces the BOJ into aggressive tightening?”
Financial Stocks Could Benefit From Higher Japanese Rates
Japanese banks have historically operated in an environment where extremely low interest rates compressed lending margins.
A gradual rise in rates can improve the economics of traditional banking.
That creates a potential sector benefit from monetary normalization.
However, investors must consider the other side.
Rapidly rising bond yields can produce losses on existing bond portfolios, while excessively tight monetary policy can weaken loan demand and economic activity.
The pace of normalization matters as much as the direction.
Japanese Exporters Face a Different Currency Equation
A stronger yen can create pressure on Japanese exporters because overseas revenue translates into fewer yen.
Industries with substantial foreign sales may therefore react negatively to yen appreciation.
A weaker yen can have the opposite effect.
This creates an interesting divergence within the Japanese stock market.
Banks and financial companies may welcome higher rates.
Export-heavy companies may prefer a weaker currency.
Domestic companies may benefit from stronger household purchasing power if wage growth keeps pace with inflation.
Investors should therefore avoid treating the Nikkei or Japanese market as a single trade.
Inflation Expectations Matter More Than One Data Point
One month’s inflation number rarely determines the direction of global markets.
Investors should watch the trend.
Important indicators include:
- Consumer inflation
- Core inflation
- Producer prices
- Wage growth
- Services inflation
- Inflation expectations
- Household spending
- Business pricing behavior
- The yen
- Japanese government bond yields
- BOJ guidance
The interaction among these indicators is more informative than any individual statistic.
What Is the BOJ Watching?
The BOJ’s own communications provide clues about what policymakers consider important.
Governor Kazuo Ueda has highlighted the relationship between wages and prices and said underlying CPI inflation is expected to move toward a level consistent with the 2% target. He has also warned that geopolitical developments, energy prices and supply-chain disruptions could alter the outlook.
The BOJ has also specifically pointed to foreign-exchange developments as a risk to Japan’s inflation and economic outlook.
For investors, this means the yen itself is becoming increasingly important to Japanese monetary policy.
Why the U.S. Federal Reserve Matters to the Story
Japan cannot be analyzed in isolation from the Federal Reserve.
Suppose the Fed is cutting interest rates while the BOJ is raising them.
The U.S.-Japan interest-rate gap could narrow quickly.
That would potentially increase demand for the yen and reduce the attractiveness of yen-funded investments.
Now consider the opposite scenario.
If the Fed maintains relatively high rates while the BOJ raises rates only slowly, the interest-rate differential may remain wide.
The carry trade could remain attractive despite Japanese tightening.
This is why investors should monitor both central banks simultaneously.
The Current U.S. Inflation Picture Adds Another Layer
U.S. inflation remains above the Federal Reserve’s long-term target.
July 2026 U.S. CPI increased 3.4% from a year earlier, while core CPI rose 2.5%. The data reduced immediate expectations of a September Fed hike but did not eliminate uncertainty about future policy.
This matters because the relative paths of the Fed and BOJ help determine currency and bond-market dynamics.
If U.S. rates remain high while Japanese rates rise, the gap narrows gradually.
If the Fed cuts aggressively while the BOJ continues tightening, the gap could narrow much faster.
Either scenario could influence the yen and global capital flows.
For additional perspective on how changing inflation affects households, rates and purchasing power, see Inflation Is Cooling but Savers Still Need to Protect Their Purchasing Power.
What Investors Should Watch Next
For the remainder of 2026, several indicators deserve particular attention.
1. Japanese Inflation
Watch whether price increases remain broad-based or begin to fade.
2. Japanese Wage Growth
Persistent wage gains would make sustained inflation more credible.
3. BOJ Rate Decisions
The market is increasingly focused on whether the BOJ raises its policy rate above the current 1% level.
4. The Yen
USD/JPY is arguably one of the most useful real-time indicators of changing expectations.
5. Japanese Government Bond Yields
Rising JGB yields can change the relative attractiveness of Japanese versus foreign assets.
6. U.S. Treasury Yields
Large changes can reveal whether global capital is being repositioned.
7. U.S. Technology Stocks
High-duration growth stocks can be sensitive to changes in liquidity and interest rates.
8. Emerging-Market Currencies
These can provide clues about global risk appetite and liquidity conditions.
What a Bullish Scenario for Global Investors Could Look Like
Japanese inflation is not necessarily a threat.
There is a more constructive scenario.
Japan could experience:
- Sustainable wage growth
- Moderate inflation around the BOJ’s target
- Gradual rate increases
- A stable yen
- Stronger domestic consumption
- Improved corporate profitability
In that environment, monetary normalization would happen gradually.
Markets would have time to adjust.
The result could be healthier Japanese economic growth without a disorderly global liquidity shock.
What a Bearish Scenario Could Look Like
The bigger risk would be a sudden acceleration in inflation accompanied by sharp yen weakness.
That could force the BOJ to tighten faster than investors expect.
If the yen then strengthens rapidly, highly leveraged carry trades could become unprofitable.
Investors could respond by selling foreign assets.
That could create pressure across:
- U.S. equities
- Global bonds
- Emerging markets
- Commodities
- High-beta assets
The danger is not simply “Japanese inflation.”
It is the possibility of Japanese inflation triggering a sudden repricing of global funding conditions.
Does This Mean Investors Should Sell U.S. Stocks?
Not necessarily.
It would be a mistake to interpret Japanese inflation as a simple sell signal for American equities.
U.S. corporate earnings, productivity, AI investment, consumer demand, fiscal policy, Fed policy and valuation remain much more direct drivers of U.S. stock prices.
Japan is one piece of the puzzle.
The more useful lesson is diversification and awareness of macroeconomic linkages.
Investors should understand how changes in:
- Currency
- Interest rates
- Liquidity
- Bond yields
- Leverage
can affect their portfolios.
Long-Term Investors Should Think in Scenarios
Rather than trying to predict the exact next BOJ decision, investors can consider several possible outcomes.
| Scenario | Yen | Japanese Rates | Global Risk Assets |
|---|---|---|---|
| Inflation cools gradually | Stable/weak | Gradual increases | Potentially supportive |
| Inflation remains persistent | Stronger risk | Faster increases | More volatility |
| Inflation accelerates sharply | Potentially volatile | Aggressive tightening | Higher downside risk |
| Japanese growth weakens | Potentially weaker | Slower tightening | Mixed |
| Fed cuts while BOJ hikes | Yen potentially stronger | Japan-U.S. gap narrows | Liquidity conditions tighten |
These are scenarios, not forecasts.
The objective is to understand what could happen to the portfolio under different conditions.
Why Currency Hedging Matters
International investors sometimes focus on the return of the underlying asset while overlooking currency exposure.
Suppose a U.S. investor buys Japanese stocks.
The investor has exposure to:
- The Japanese stock market.
- The yen-dollar exchange rate.
A Japanese stock can rise in yen terms while the investor’s dollar-denominated return is much smaller if the yen weakens.
The reverse can also happen.
Currency movements can therefore materially change international investment outcomes.
Japan Is a Reminder That Markets Are Connected
One of the most important lessons from the Japanese inflation story is that geographic diversification does not eliminate macroeconomic interdependence.
A U.S. investor can own an S&P 500 index fund.
A European investor can own global equities.
An emerging-market investor can own a local stock index.
All three can still be affected by:
- Japanese interest rates
- U.S. Treasury yields
- The yen
- Global liquidity
- Central-bank policy
Financial markets are connected through capital flows.
That connection is easy to ignore when markets are calm.
It becomes much more obvious when funding conditions change rapidly.
The Japan Indicator Global Investors Shouldn’t Ignore
Japanese inflation matters because Japan sits at an important intersection of currencies, bonds, central-bank policy and global capital flows.
The country’s transition away from ultra-low interest rates has been gradual, but it is changing the assumptions that investors have relied on for years.
The BOJ currently targets a policy rate around 1%, and its own guidance indicates that further normalization remains possible if the economic and inflation outlook develops as expected. Meanwhile, July producer-price inflation of 7.2% and renewed pressure on the yen have put Japanese monetary policy back into the global market spotlight.
For U.S. and global stock investors, the key issue is therefore not whether Japanese inflation is “good” or “bad.”
It is whether inflation causes a controlled normalization of Japanese monetary policy or a much faster repricing of the yen, Japanese bonds and global funding trades.
That distinction could determine whether Japan remains a background macroeconomic story—or becomes a significant driver of volatility across global portfolios.
This article is for general information and education, not personalized investment advice. Market conditions can change quickly, and investors should consider their own objectives, risk tolerance and financial circumstances before making investment decisions.