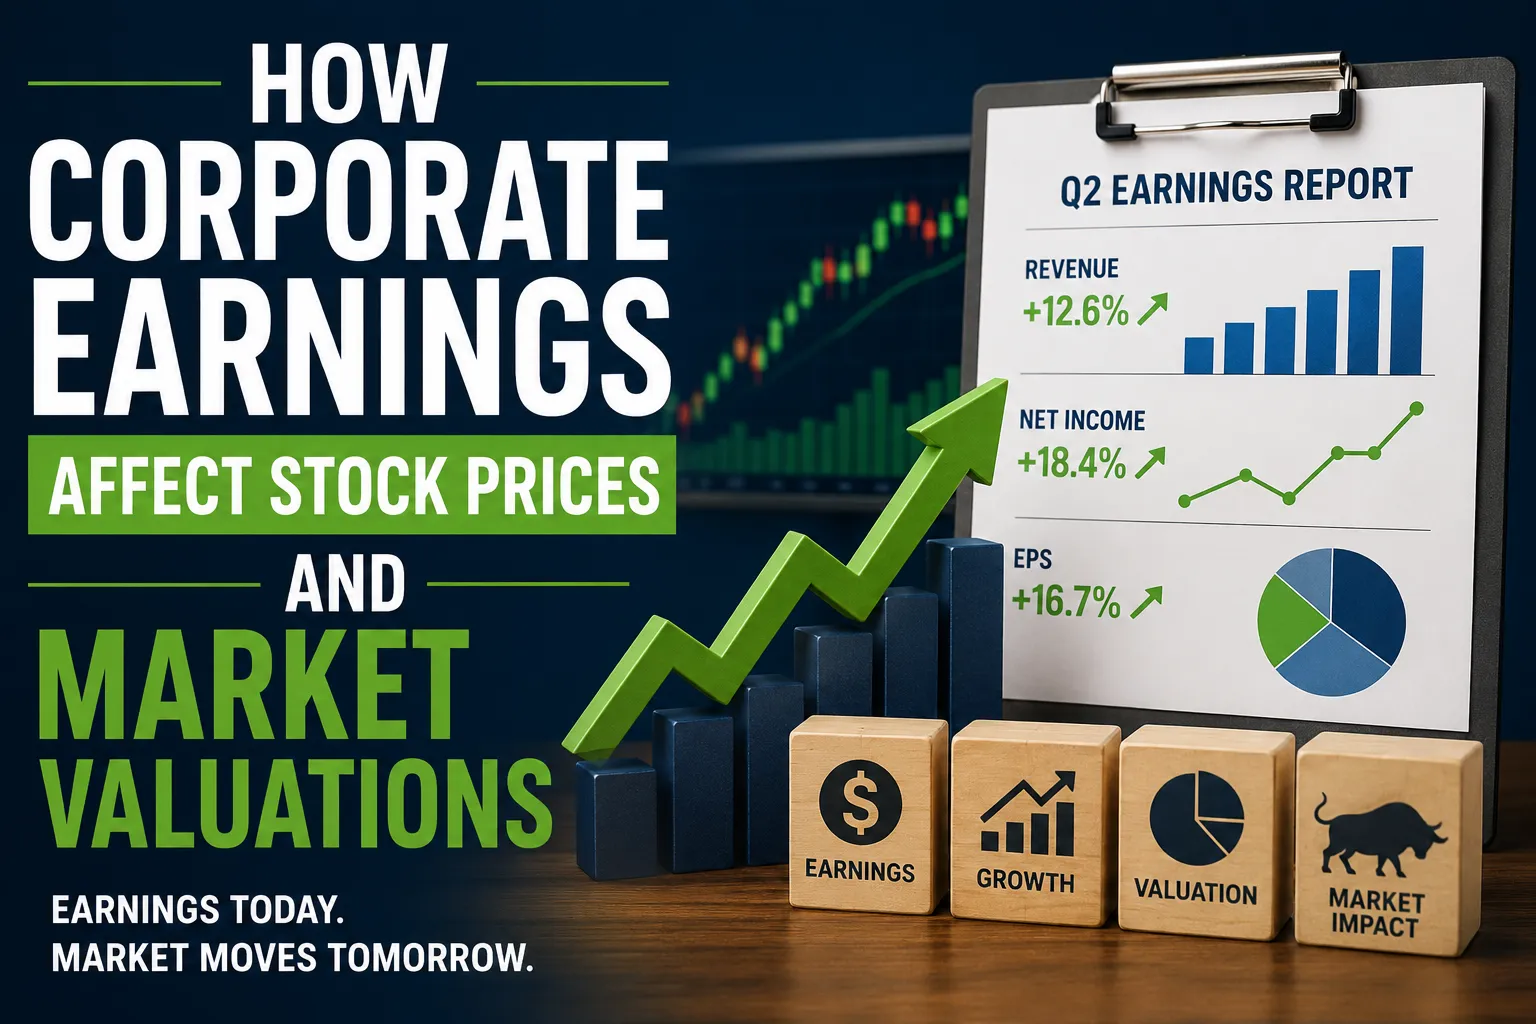
How Corporate Earnings Affect Stock Prices and Market Valuations
Corporate earnings are among the most closely watched numbers in financial markets. Every quarter, investors examine company revenue, profits, margins and forecasts to determine whether a business is performing better or worse than expected.
The reaction can sometimes appear surprising. A company can report higher profits and still see its stock price fall. Another company can post a loss and watch its shares rise.
The reason is that stock prices reflect expectations about the future, not simply what happened during the most recent quarter.
Understanding the relationship between earnings, expectations and valuation helps explain why corporate results can move individual stocks and, when the companies involved are large enough, influence entire markets.
For a broader explanation of how stocks, bonds and other markets fit together, see the complete guide to financial markets and how they work.
What Corporate Earnings Actually Tell Investors
Corporate earnings generally refer to the profit a company generates over a specific period.
Investors typically examine several related measures, including:
- Revenue
- Operating income
- Net income
- Earnings per share
- Gross margin
- Operating margin
- Free cash flow
- Guidance for future periods
Each measure provides a different perspective.
Revenue shows how much money a company generated from its operations, while earnings indicate how much remains after expenses and other costs are accounted for.
Earnings per share, or EPS, divides applicable profit among the company’s shares and is one of the most widely followed figures in quarterly reporting.
Why Earnings Matter to Stock Prices
At a basic level, investors buy shares because they expect a company to generate cash and profits in the future.
If a company’s expected future earnings increase, investors may be willing to pay more for its stock.
If expected earnings decline, investors may be willing to pay less.
This creates a simplified relationship:
Higher expected future earnings → potentially higher stock value
Lower expected future earnings → potentially lower stock value
But the actual relationship is more complicated because investors constantly compare current results with what was already expected.
Expectations Often Matter More Than the Headline Number
Suppose analysts expect a company to earn $2.00 per share.
The company reports $2.20.
At first glance, that looks positive.
But imagine investors were expecting $2.40 by the time the results were released.
The company technically exceeded the original forecast but still delivered a result below the market’s latest expectations.
The stock could fall.
This is why financial markets often react to the surprise in an earnings report rather than simply the absolute level of profits.
Earnings Estimates Are Built Into Stock Prices
Before a company reports results, investors form expectations about what it will earn.
Those expectations influence the stock price before the earnings announcement.
If investors already expect exceptionally strong growth, much of that optimism may already be reflected in the share price.
When the actual results arrive, the company must often exceed those elevated expectations to produce a strong positive reaction.
This helps explain why a company can report record profits while its stock declines.
The market may have expected even more.
Guidance Can Be More Important Than Past Results
Quarterly earnings describe what has already happened.
Investors, however, are generally more interested in what comes next.
That makes management guidance particularly important.
Companies may provide expectations for:
- Future revenue
- Earnings
- Profit margins
- Capital spending
- Demand
- Hiring
- Product launches
- Full-year performance
If management reduces its forecast, investors may interpret the change as a warning that future earnings will be weaker.
Even a strong quarter can be overshadowed by cautious guidance.
Revenue Growth Matters
Profit growth receives considerable attention, but revenue is another critical part of an earnings report.
A company can increase profits temporarily by cutting costs, but sustained long-term growth often requires expanding sales.
Investors therefore examine whether revenue is growing and what is driving that growth.
Questions may include:
- Are customers buying more?
- Are prices increasing?
- Is the company gaining market share?
- Is growth coming from acquisitions?
- Is demand weakening in a key market?
Understanding the source of revenue growth can be as important as the growth rate itself.
Profit Margins Can Change the Story
Revenue alone does not determine profitability.
Two companies can generate similar sales but produce very different profits because their costs differ.
Profit margins help investors understand how efficiently a company converts revenue into earnings.
If revenue increases while margins expand, earnings may grow particularly quickly.
If revenue rises but margins contract, the increase in sales may provide less benefit to shareholders than expected.
This is why investors often pay close attention to gross and operating margins during earnings season.
Free Cash Flow Provides Another Perspective
Accounting earnings and cash generation are related but not identical.
Free cash flow can provide insight into how much cash a company generates after necessary capital expenditures.
Strong free cash flow can support:
- Dividends
- Share buybacks
- Debt reduction
- Acquisitions
- Research and development
- Expansion
A company reporting growing earnings but consistently weak cash generation may attract closer scrutiny.
For investors evaluating how profits can ultimately translate into shareholder distributions, dividends and stock ownership explained provides additional context.
Earnings Influence Valuation Multiples
Corporate earnings are also important because they are used in common valuation measures.
One of the best-known is the price-to-earnings ratio, or P/E ratio.
It compares a company’s share price with its earnings per share.
In simplified terms:
P/E ratio = Share price ÷ Earnings per share
For example, if a stock trades at $100 and generates $5 in annual EPS, its P/E ratio would be 20.
Investors can then compare that valuation with the company’s historical levels, competitors and broader market.
A Higher P/E Can Reflect Higher Expectations
A high P/E ratio does not automatically mean that a stock is overpriced.
Investors may be willing to pay a premium for a company they believe can grow earnings rapidly in the future.
Technology companies, for example, may sometimes trade at higher earnings multiples when investors expect substantial long-term growth.
The challenge is that high expectations leave less room for disappointment.
If future growth fails to justify the valuation, the stock can fall even if the business remains profitable.
A Low P/E Is Not Automatically a Bargain
The opposite is also true.
A stock with a low P/E ratio is not necessarily undervalued.
Investors may assign it a low multiple because they expect:
- Falling earnings
- Weak demand
- Competitive pressure
- High debt
- Regulatory problems
- Structural changes in the industry
A low valuation can therefore reflect genuine concerns about the company’s future.
Earnings Growth and Market Valuations Are Connected
Market valuation depends partly on expectations for future earnings growth.
Consider two companies that each earn $5 per share.
If investors expect Company A’s earnings to grow rapidly for many years, they may pay substantially more for its shares than they would for Company B, whose earnings are expected to remain flat.
The difference is not the current earnings figure.
It is the expected future earnings trajectory.
Interest Rates Can Change the Earnings Equation
Corporate earnings do not exist in isolation.
Interest rates can have a major influence on how investors value future profits.
When interest rates rise, future cash flows can become less valuable in present-value calculations.
Higher rates can also increase borrowing costs for companies.
That can reduce profits for businesses with substantial debt or increase the cost of financing new investments.
Conversely, falling interest rates can reduce borrowing costs and potentially make future earnings more attractive to investors.
Inflation Can Affect Corporate Profits
Inflation can influence both revenue and expenses.
Companies may raise prices, increasing nominal revenue.
But they may also face higher costs for:
- Labor
- Raw materials
- Transportation
- Energy
- Rent
- Financing
Whether inflation helps or hurts a company depends partly on its ability to pass higher costs on to customers.
Companies with strong pricing power may be better positioned to protect margins.
Different Industries React Differently
An earnings surprise does not have the same meaning across every industry.
A bank’s results may depend heavily on interest income, credit losses and loan growth.
A retailer may focus on comparable-store sales, inventory and consumer demand.
A technology company may emphasize cloud growth, subscriptions, artificial intelligence spending or operating margins.
An energy producer may be heavily influenced by commodity prices.
Investors therefore need to understand the business model behind the numbers.
Earnings Can Move Entire Sectors
When a major company reports results, the effect can extend beyond its own shares.
If a large semiconductor company reports exceptionally strong demand, investors may become more optimistic about other semiconductor manufacturers.
If a major retailer warns about weak consumer spending, other consumer-facing companies may also experience pressure.
This is known as a read-through effect.
One company’s results can provide clues about conditions affecting an entire industry.
Large Companies Can Influence Major Indexes
The market impact becomes even larger when the company is a major component of a widely followed stock index.
Large companies can have substantial index weights.
A significant move in one of these stocks can therefore influence the overall performance of an index even if most other companies are relatively unchanged.
During earnings season, investors may consequently pay close attention to results from companies with large market capitalizations.
Earnings Season Can Increase Market Volatility
When many major companies report results within a short period, financial markets can become particularly sensitive to new information.
Share prices may move sharply after:
- Earnings releases
- Management conference calls
- Guidance changes
- Analyst revisions
- Unexpected expenses
- Major acquisitions
- Regulatory developments
This does not necessarily mean that the underlying businesses have suddenly changed dramatically.
Markets can move because investors are rapidly adjusting expectations.
For a deeper explanation of the forces behind sharp price movements, see how stock market volatility works and what causes market volatility.
The Conference Call Can Matter as Much as the Report
The earnings release is only part of the information investors receive.
Management usually holds a conference call where executives discuss the results and answer questions from analysts.
Investors listen for clues about:
- Customer demand
- Future growth
- Costs
- Competitive conditions
- Capital spending
- Product development
- Economic trends
A company’s numbers may look strong on paper while management’s comments reveal concerns about the coming quarters.
That can change the market’s interpretation of the report.
Analysts Often Revise Their Forecasts
Following an earnings report, analysts may change their expectations for future earnings.
If several analysts raise their forecasts, investors may begin assigning a higher value to the company.
If estimates are reduced, the stock can come under pressure.
These revisions can affect valuations even when the current quarter’s results remain unchanged.
The reason is simple: valuation depends heavily on expectations about future earnings.
Stock Buybacks Can Affect Earnings Per Share
Companies sometimes use excess cash to repurchase their own shares.
When the number of shares outstanding decreases, earnings per share can increase even if total net income does not rise at the same rate.
Investors therefore need to distinguish between growth in total earnings and growth in earnings per share.
Share repurchases can be beneficial when companies buy shares at attractive valuations, but the financial effect should be considered alongside the price paid and the company’s broader capital-allocation strategy.
One Strong Quarter Does Not Guarantee Long-Term Growth
Investors can become overly focused on quarterly numbers.
A company may benefit from a temporary surge in demand, a favorable currency movement or an unusual cost reduction.
Such factors may not continue.
Long-term investors often look beyond the headline earnings figure to determine whether the company’s competitive position and underlying economics are improving.
Look for the Quality of Earnings
Not all earnings growth is equally valuable.
High-quality earnings growth may be supported by:
- Sustainable revenue growth
- Strong customer demand
- Improving productivity
- Durable competitive advantages
- Healthy cash generation
- Disciplined spending
Investors should be cautious about treating temporary gains as evidence of a permanent improvement in business performance.
What Investors Can Watch During Earnings Season
Reading an earnings report can be overwhelming, but a few questions can provide a useful framework.
1. Did revenue meet expectations?
Look at both the reported figure and the growth rate.
2. Did earnings beat or miss forecasts?
Compare EPS with analyst expectations.
3. Are margins improving?
Revenue growth accompanied by expanding margins can be particularly significant.
4. What happened to guidance?
Forward expectations often matter more than historical results.
5. Is cash flow healthy?
Cash generation can help reveal the strength of reported profits.
6. What did management say?
The conference call can provide important context.
7. Has the valuation changed?
Consider whether the stock price still makes sense relative to expected future earnings.
Why Market Reactions Can Look Irrational
Stock-market reactions can seem disconnected from company performance because investors are constantly repricing expectations.
A company might report excellent results, but if investors expected even better numbers, the stock can fall.
Another company might report disappointing results, but if investors feared an even worse outcome, the stock could rise.
The market is therefore not simply asking:
“Did the company make money?”
It is asking:
“Did the company perform better or worse than what was already reflected in its price, and what does this imply about the future?”
Earnings Are One Piece of the Valuation Puzzle
Corporate earnings are essential to understanding stock prices, but they are not the only factor.
Investors also consider:
- Interest rates
- Inflation
- Economic growth
- Competitive conditions
- Management quality
- Debt levels
- Industry trends
- Cash flow
- Future growth opportunities
- Investor sentiment
A company’s share price reflects the interaction of these factors rather than a single financial statistic.
The Bigger Picture Behind Quarterly Results
Corporate earnings provide one of the clearest windows into the financial health of publicly traded businesses.
Strong results can support higher valuations when they improve expectations for future profits. Weak results can pressure valuations when they suggest that growth or profitability may deteriorate.
But the market’s response depends heavily on expectations.
The most important earnings number is often not the number a company reports—it is the gap between that number and what investors believed they would see.
For investors trying to understand market movements, that distinction is crucial. Earnings tell us what happened. Guidance, valuation and expectations help explain what the market thinks will happen next.